
CrownPoint Partners Closes $9.2 Million Five-Property Michigan Dental Portfolio Sale-Leaseback
Source: PR Newswire
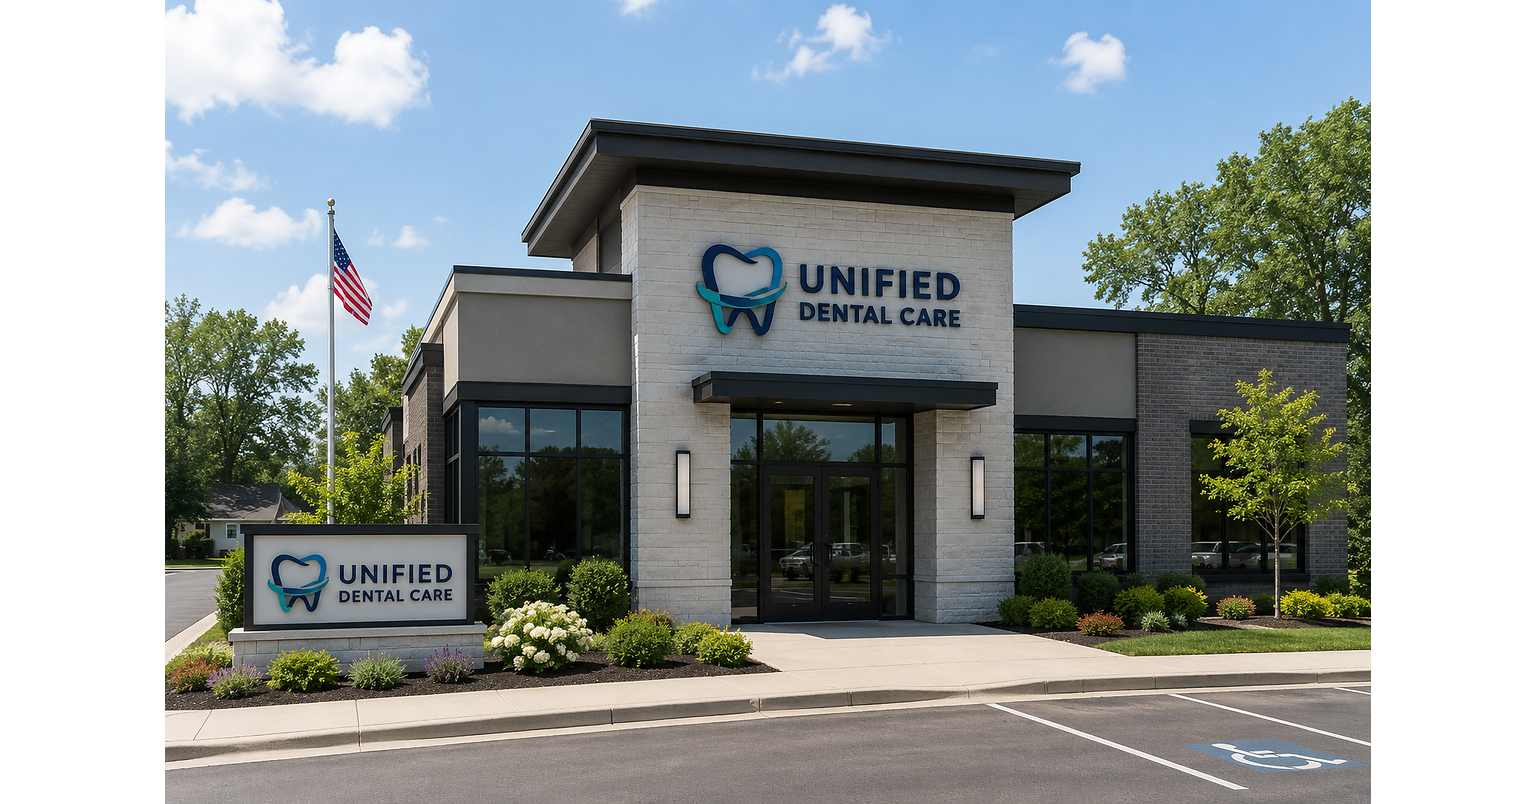
CrownPoint Partners closed a $9.2 million sale-leaseback portfolio of five Michigan dental properties totaling 35,212 square feet, representing both seller and buyer. The properties were leased under new 15-year absolute net leases with 2% annual rent increases; the transaction closed 42 days after contract. The deal adds to CrownPoint’s healthcare-focused sale-leaseback activity but is a limited-scale transaction.
Analysis
The transaction is too small and lacks buyer, seller/operator, and cap-rate disclosure to support a direct earnings or valuation read-through for public equities. Its useful signal is narrower: a 15-year lease with fixed 2% annual bumps transfers property-cost certainty to the buyer but converts the operator’s real estate into a long-dated fixed obligation. That structure is attractive only if the dental business sustains rent coverage through reimbursement pressure, labor inflation, and practice-level volatility; otherwise, the real estate remains secure in form but tenant-credit risk can dominate the headline lease term.
The reported 42-day close is evidence of execution speed, not proof of broadening capital availability or attractive pricing. For net-lease REITs such as Realty Income (O), NNN REIT (NNN), and Agree Realty (ADC), this is not material absent a repeatable pipeline, disclosed yields, and tenant credit data. A contrarian read: investors may overinterpret a broker’s single transaction as evidence of durable healthcare-property demand; equally, the undisclosed pricing prevents concluding that financing conditions are restrictive. Over 1–3 months, verify operator identity, rent coverage, lease guarantees, and capitalization rate. Over 6–18 months, the key risk is whether sale-leasebacks fund growth or merely defer balance-sheet strain by adding fixed charges.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Key Decisions for Investors
- No trade on the announcement alone; do not infer a valuation or financing-market signal without the cap rate, buyer identity, and operator-level credit information.
- Add a watch item for any disclosed operator or guarantor: assess rent-to-EBITDAR coverage, same-store growth, and debt obligations before treating the 15-year lease as creditworthy income.
- For O, NNN, and ADC, treat this only as a sector datapoint—not a catalyst. Reassess if several comparable healthcare deals disclose attractive yields and repeat buyers, or if REIT acquisition guidance changes.
- Falsify the constructive demand interpretation if follow-on transactions slow, disclosed cap rates widen materially, or the operator reports weaker practice economics or reduced guidance.
More News
- Why is SK Hynix stock gaining today?
- Former world No. 1 Jon Rahm's lawyer tells court Spaniard is done with LIV Golf after three seasons
- Anthropic will be 'most ridiculous IPO' of year, analyst says
- Levi Strauss hikes profit guidance after tariff refunds, but its sales outlook is less optimistic
- Weston Family, Fairfax Financial’s Watsa Acquire Boots in $8.9 Billion Deal
- Brazil is having its Argentina moment. How to play it
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Research Workflows, Report Format Selection, and Interactive Synthesis
- Can ChatGPT Analyze a 10-K? A Verification Workflow