
FF EAI Robotics Ecosystem Inc. (f/k/a AIxCrypto Holdings, Inc.) to Acquire FF Robotics Business for Standalone Listing; Faraday Future Unveils New Execution Plans for "Built In USA" Acceleration Program and Initiates Conditional Approval Application, Will Roll Out New Robot Product in Q1 2027
Source: PR Newswire
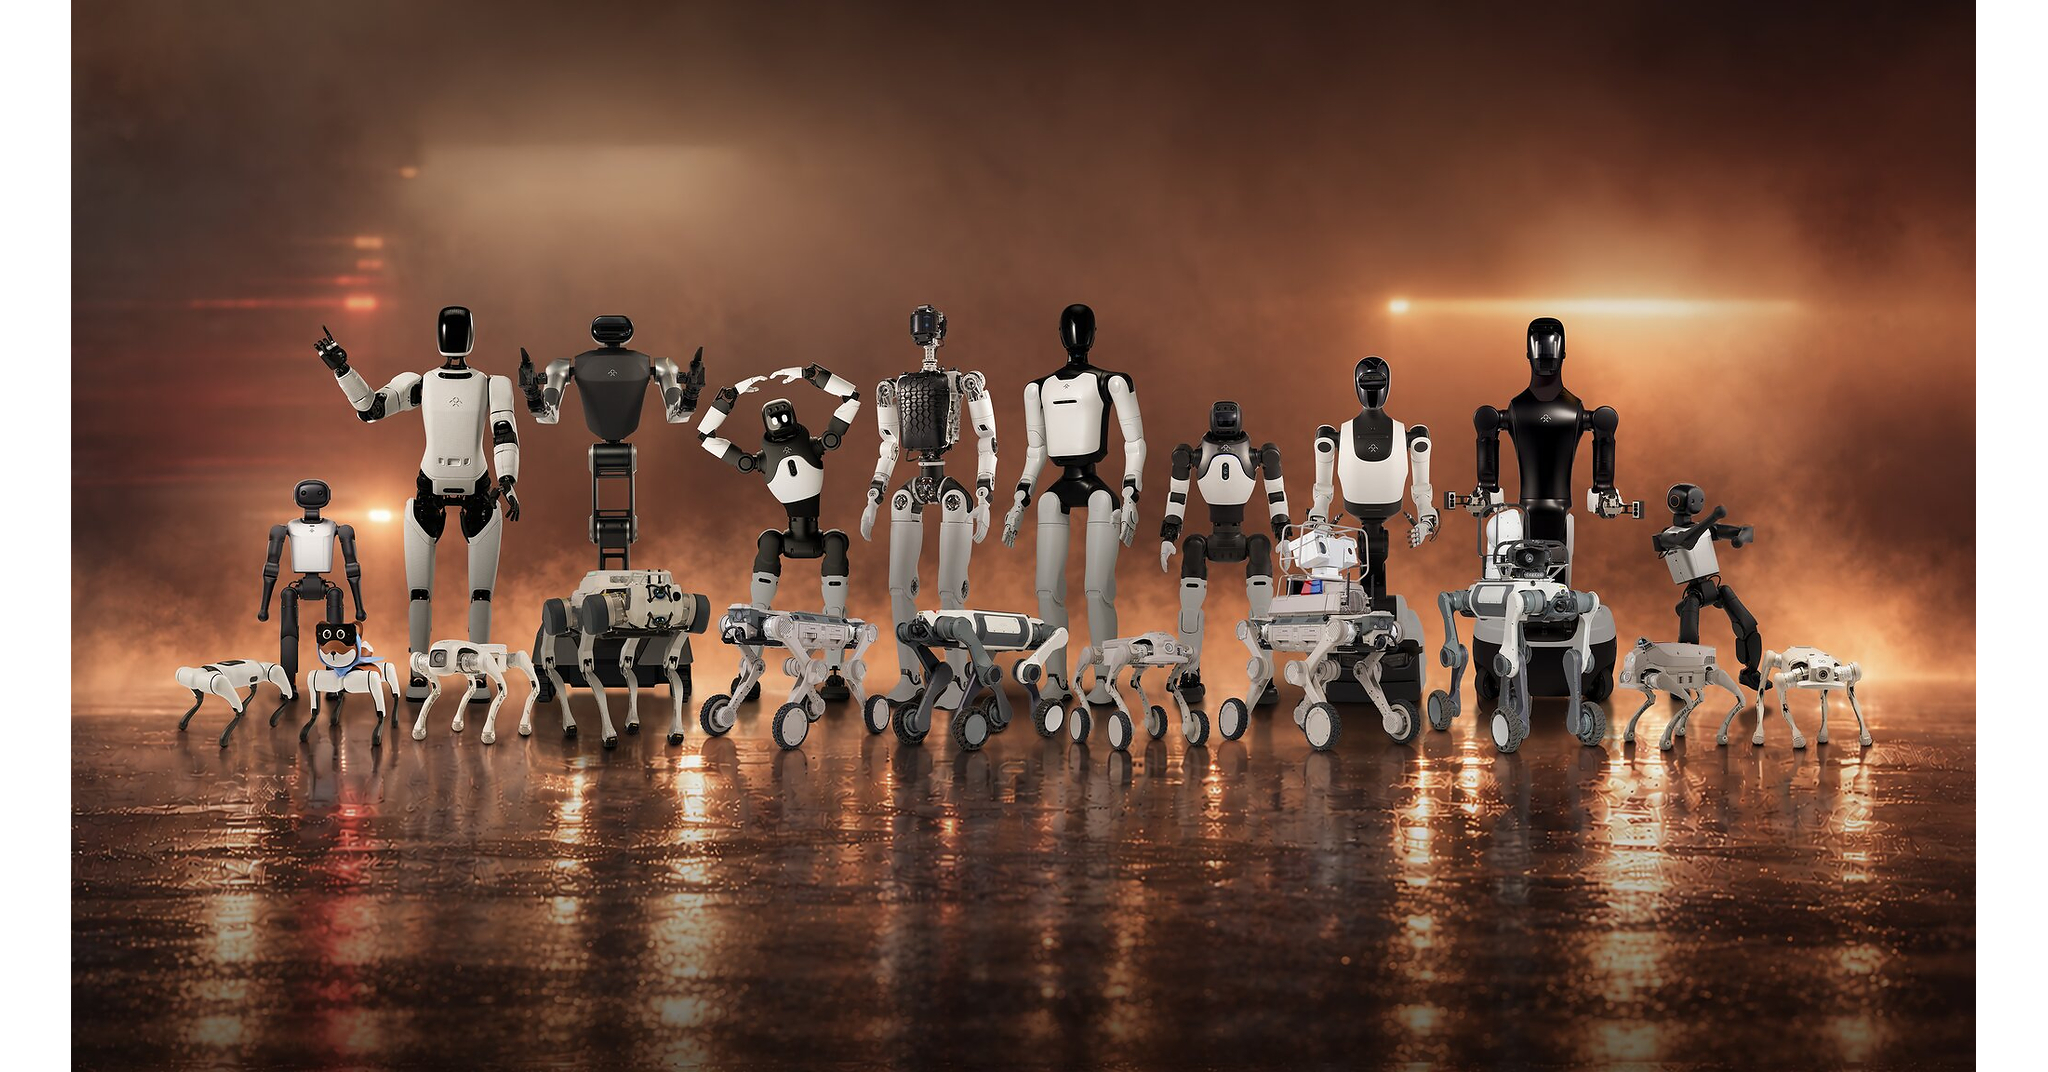
AIxCrypto (to be renamed FF EAI Robotics Ecosystem and retickered FFR) signed a non-binding term sheet to acquire Faraday Future's robotics business in an all-stock deal valued at approximately $200 million, with FFAI retaining control after closing. The robotics business reported $1.52 million of cumulative revenue, 552 cumulative shipments and an unaudited 30.9% Q2 2026 gross margin, while projecting $7.1 million of 2026 revenue, $45.17 million in 2027 and $1.98 billion cumulatively over five years. FF targets U.S. robot-factory operations by year-end and its first newly produced EAI device in Q1 2027, but the transaction remains subject to diligence and approvals amid explicit going-concern, liquidity, dilution and execution risks.
Analysis
This is principally a related-party reverse-merger/financing event rather than a validated robotics commercialization inflection. The proposed asset valuation implies a steep revenue multiple on a business with immaterial current sales, while the consideration structure leaves FFR exposed to a large share issuance, uncertain closing terms, and a controlling seller that retains economic control. For FFR, the ticker change can create a near-term retail/liquidity bid, but the fundamental catalyst is the definitive proxy: share count, exchange ratio, fairness opinion, audited carve-out financials, working-capital commitments, and any concurrent PIPE—not product roadmap claims.
FFAI gains an option-like public valuation marker for a non-core business and may benefit if market enthusiasm for robotics lifts the value of its retained stake. The second-order negative is that separating the asset does not remove FFAI's capital burden if it remains the supplier, guarantor, transition-services provider, or financier of the new entity; disclosures on these arrangements determine whether the transaction actually de-risks FFAI. FFR also inherits execution exposure to U.S. component localization, where batteries, actuators, compute modules, and safety certification can turn modest gross-margin claims into negative contribution margins at low volume.
Near term, expect event-driven volatility around the record-date dividend mechanics and Nasdaq review, with crypto-legacy holders potentially selling into the robotics rebrand. Over 1-3 months, failure to announce committed financing or definitive agreements should compress the transaction premium. Over 6-18 months, the relevant proof points are repeat customer orders, deployed-unit utilization, service/maintenance costs, and independently reported gross margin—not aggregate multi-year projections. Contrarian view: the rebrand may be underwritten as a pure-play AI optionality trade, but control conflicts and financing needs make it more analogous to a dilutive microcap asset injection.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mixed
Sentiment Score
0.08
Ticker Sentiment
Key Decisions for Investors
- Avoid fundamental long exposure in FFR/AIXC before a definitive merger agreement and audited carve-out statements. Treat any rebrand-driven spike as tactical only; a financing announcement with material discounting or warrants would be the key downside catalyst.
- Consider a small short-bias trade in FFR after any momentum-driven extension, subject to borrow availability and hard-to-borrow cost. Target a 20-30% normalization over 1-3 months if no committed capital package or signed definitive agreement emerges; stop on disclosed financing at a premium with credible third-party lead investors.
- Maintain FFAI as a watch rather than a long: reassess only if filings show that the spinout eliminates cash support obligations and monetizes FFAI's retained stake without incremental dilution. Falsifier for the bearish view is a fully funded standalone plan with arm's-length governance and material contracted backlog.
- Monitor SEC filings for pro forma ownership, fully diluted FFR share count, related-party transition agreements, special-dividend record date, Nasdaq listing determination, and the disposition value of remaining digital assets. These data points matter more than shipment or alliance announcements for estimating equity value.
More News
- Asian stocks dip, bonds in focus after torrid September
- Paramount Skydance prices $42 billion debt for Warner Bros deal
- Tencent leases 100,000 chips from Oracle for $7 bln- FT
- California Gov. Gavin Newsom bans AI 'robo bosses' in landmark state law, reversing his earlier veto
- Stocks Jump on inflation Surprise, Apple's Smart-Home Push
- The new and huger Paramount has a new co-CEO