
Starlight Investments Announces Successful Close of UK BTR Fund II
Source: PR Newswire
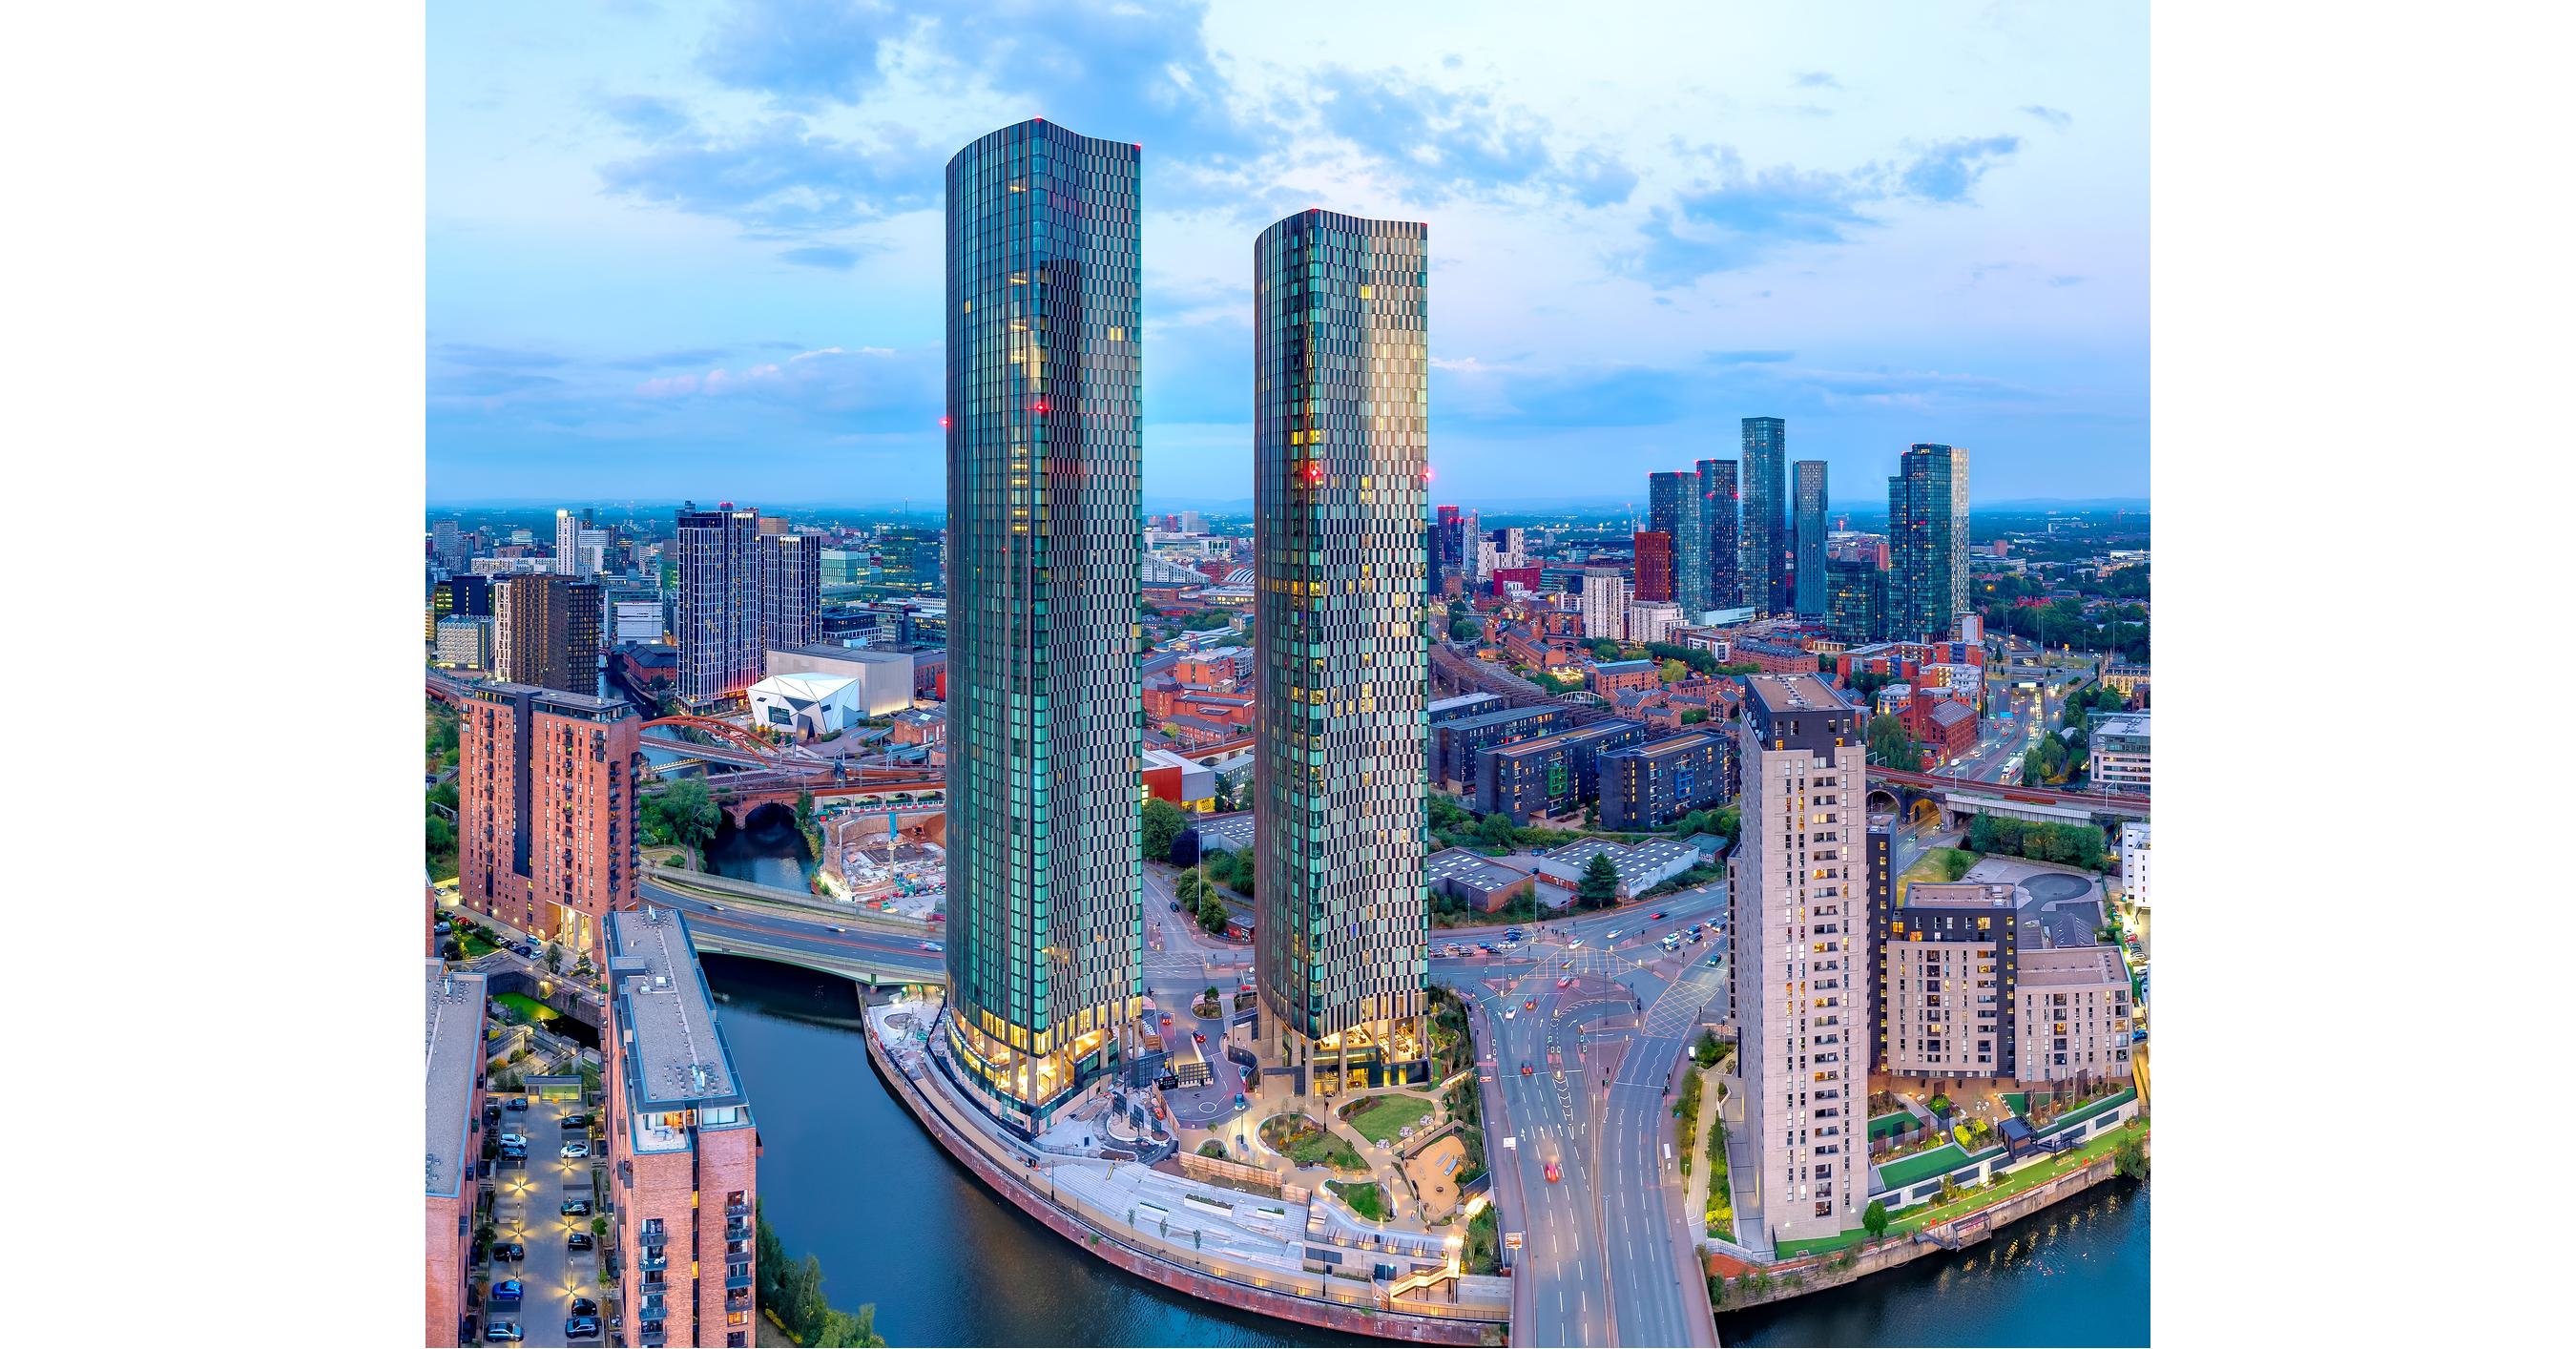
Starlight Investments closed its UK BTR Fund II with £680 million of commitments across the fund and ancillary vehicles, financing the acquisition and delivery of more than 6,000 rental homes. The fund is partially deployed in three communities under construction in Manchester and Basildon and received backing from global institutional investors, including Homes England's National Housing Bank. Starlight expects its expanding 12-community UK pipeline to make it one of the country’s four largest build-to-rent operators by scale.
Analysis
This is a modestly constructive read-through for UK regional residential development funding rather than a public-equity catalyst. The relevant signal is that institutional equity remains available for scaled BTR platforms despite a higher-for-longer rate backdrop; that supports forward land transactions, construction starts, and development-management fees. Manchester and commuter-belt submarkets should see the earliest competitive pressure for development sites, which may raise residual land values before it translates into rents.
The second-order beneficiary is the construction and building-products chain, but only if commitments convert into contracted starts: UK-listed exposure includes Vistry (VTY), Crest Nicholson (CRST), Travis Perkins (TPK), and brick/building-material suppliers such as Ibstock (IBST). The principal loser is smaller, highly levered private developers dependent on bank financing: institutional BTR buyers can selectively acquire their stalled sites, while also competing for the limited pool of construction labor and subcontractor capacity. Public housebuilders have mixed exposure because BTR bulk sales de-risk absorption but typically carry lower gross margins than retail sales.
Near term, this does not change earnings estimates for listed names and should not be chased as a standalone trade. Over 1-3 months, watch whether the fund announces land acquisitions, forward-funding contracts, or major contractor awards; those disclosures would validate capital deployment rather than merely fundraising. Over 6-18 months, sustained institutional BTR fundraising could cap rental-growth upside in the specific regional micro-markets receiving concentrated new supply, while making rental income streams more institutionalized and potentially supporting valuation for listed residential REIT proxies.
The contrarian risk is execution: a closed-end capital pool is not proof of attractive project-level returns. If gilt yields rise, construction inflation re-accelerates, or regional employment weakens, development yields can compress below financing costs and force slower deployment; that would be more negative for smaller developers and contractors with fixed-price exposure than for the asset manager.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.62
Key Decisions for Investors
- No immediate directional trade: treat this as a UK BTR capital-formation watch item, not an earnings catalyst for a listed security.
- Monitor VTY and CRST for disclosed BTR forward-sales or land transactions over the next 1-3 months; consider a tactical long only after a named transaction demonstrates margin-accretive capital recycling, with exit on gross-margin guidance deterioration or cancellation of a major bulk-sale agreement.
- Keep IBST and TPK on a 6-18 month deployment watchlist rather than buying on the announcement. Upgrade only if UK housing-start data and company order books show that institutional-funded projects are converting into incremental volumes, not displacing retail housing activity.
- For UK residential exposure, prefer diversified asset-light or balance-sheet-strong developers over highly levered small-cap builders while 10-year gilt yields remain volatile; the thesis is falsified if funding costs decline materially and bank credit reopens for smaller private developers, reducing institutional buyers' distressed-site advantage.
More News
- Here’s the ‘core economic flaw’ in the AI bull case as stock and bond trades unravel, according to a top economist
- Braskem creditors, shareholders near deal on $11bn debt restructuring
- Instacart reportedly discussed selling itself with DoorDash and Uber
- Nvidia's role as AI financier faces first big test as neoclouds take market hit
- Trump set to announce plan by Audi to build a U.S. factory in Georgia, source says
- Why popular airplanes are getting scrapped years early