
Les salons Furniture China et Maison Shanghai 2026 entament le dernier compte à rebours
Source: PR Newswire
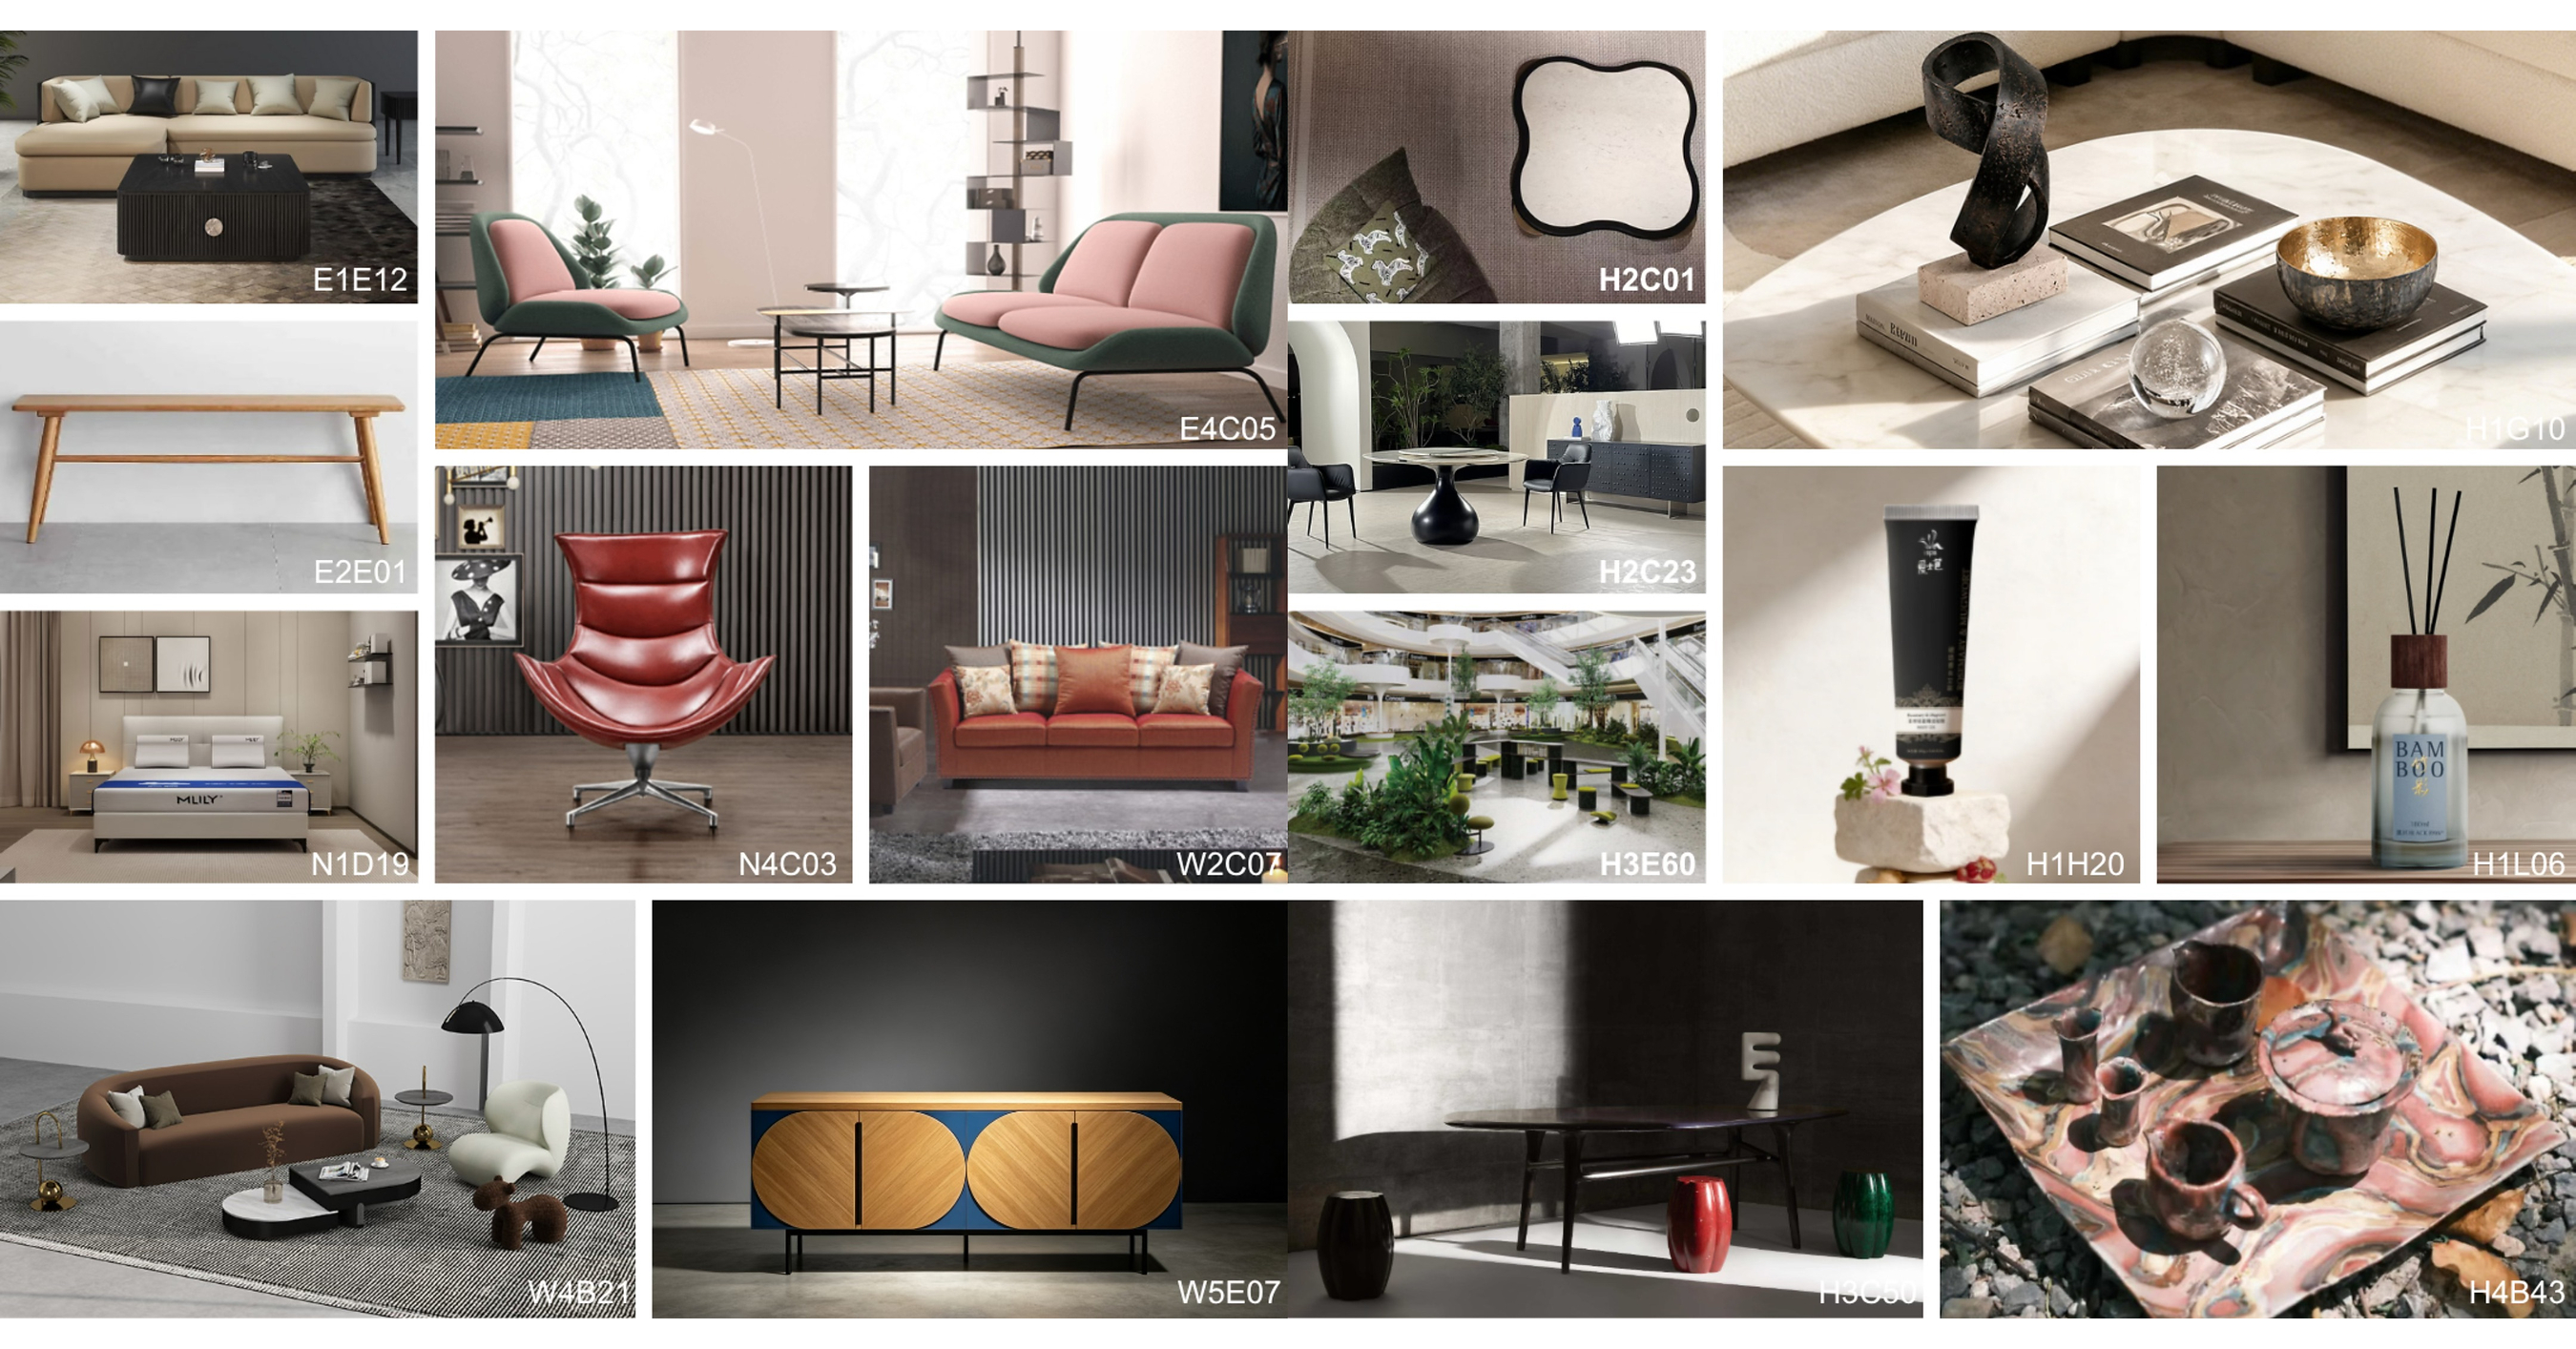
Furniture China (8–11 septembre 2026) et Maison Shanghai (7–10 septembre 2026) reviennent à Shanghai Pudong avec un périmètre “approvisionnement–fabrication–design” sur deux sites. Les salons annonceront plus de 3 200 marques exposantes sur 350 000 m² et visent plus de 200 000 visiteurs professionnels, avec des offres dédiées pour acheteurs étrangers et des services (visa, vols, navettes). L’article est surtout promotionnel et ne signale pas de changement économique mesurable ni de guidance financière.
Analysis
This is more a sentiment read on China’s export-and-procurement ecosystem than a direct earnings catalyst. The real winners are the logistics, hospitality, and transaction rails that monetize business travel and cross-border procurement; for V, the incremental lift is through card spend tied to flights, hotels, and on-site purchases, not the fair itself. Even a strong attendance number would likely be too small to move quarterly payment volume by more than noise-level basis points.
The second-order issue is that trade fairs often act as inventory-clearing venues in soft-demand cycles. If buyers show up but only negotiate on price, smaller furniture manufacturers and component suppliers can see margin pressure even as headline activity looks healthy. That dynamic is bearish for fragmented home-goods supply chains and neutral-to-bearish for China consumer cyclicals unless the event converts into firm orders over the next 1-3 months.
Contrarianly, the market may overread the optics of a large physical gathering as proof of a demand rebound. The more important tell is post-event order conversion, export bookings, and any change in Chinese outbound travel/payment data in October. For V specifically, this is a watch item, not a stand-alone catalyst; the thesis would be falsified if cross-border volume growth does not improve into Q3/Q4 despite the event calendar.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.00
Key Decisions for Investors
- No immediate trade in V: the incremental cross-border spend from this event is too small to justify a position absent confirming data on international travel and payment volumes over the next 4-8 weeks.
- Set a watch alert on V into the Q3 print: only reconsider if cross-border volume or international card spend inflects by at least low-single digits versus the prior quarter; otherwise the event is noise.
- Avoid buying China home-goods or furniture suppliers on the headline alone; wait for post-show order data before taking any exposure to XHB or named furnishings suppliers, because fair attendance can mask discounting and margin compression.
- If looking for a tactical China travel rebound expression, prefer a broader travel/hospitality basket only after September outbound travel data confirms the trend; this is a higher-conviction monetization path than V.
More News
- ‘Indentured servants’: US green card move will hit thousands of IT workers
- Delta Air Lines cuts 2026 forecast on fuel surge, but CEO says demand is still strong
- Is AI the new China Shock?
- Why is T-Mobile stock tumbling today?
- India calls JD Vance's comments about immigrants 'deeply offensive'
- Why is Verizon stock sliding today?