
Bitmine Immersion Technologies (BMNR) gibt bekannt, dass der ETH-Bestand 5,98 Millionen Token erreicht hat und sich der Gesamtbestand an Kryptowährungen sowie Barmitteln auf 17,1 Milliarden US-Dollar beläuft
Source: PR Newswire
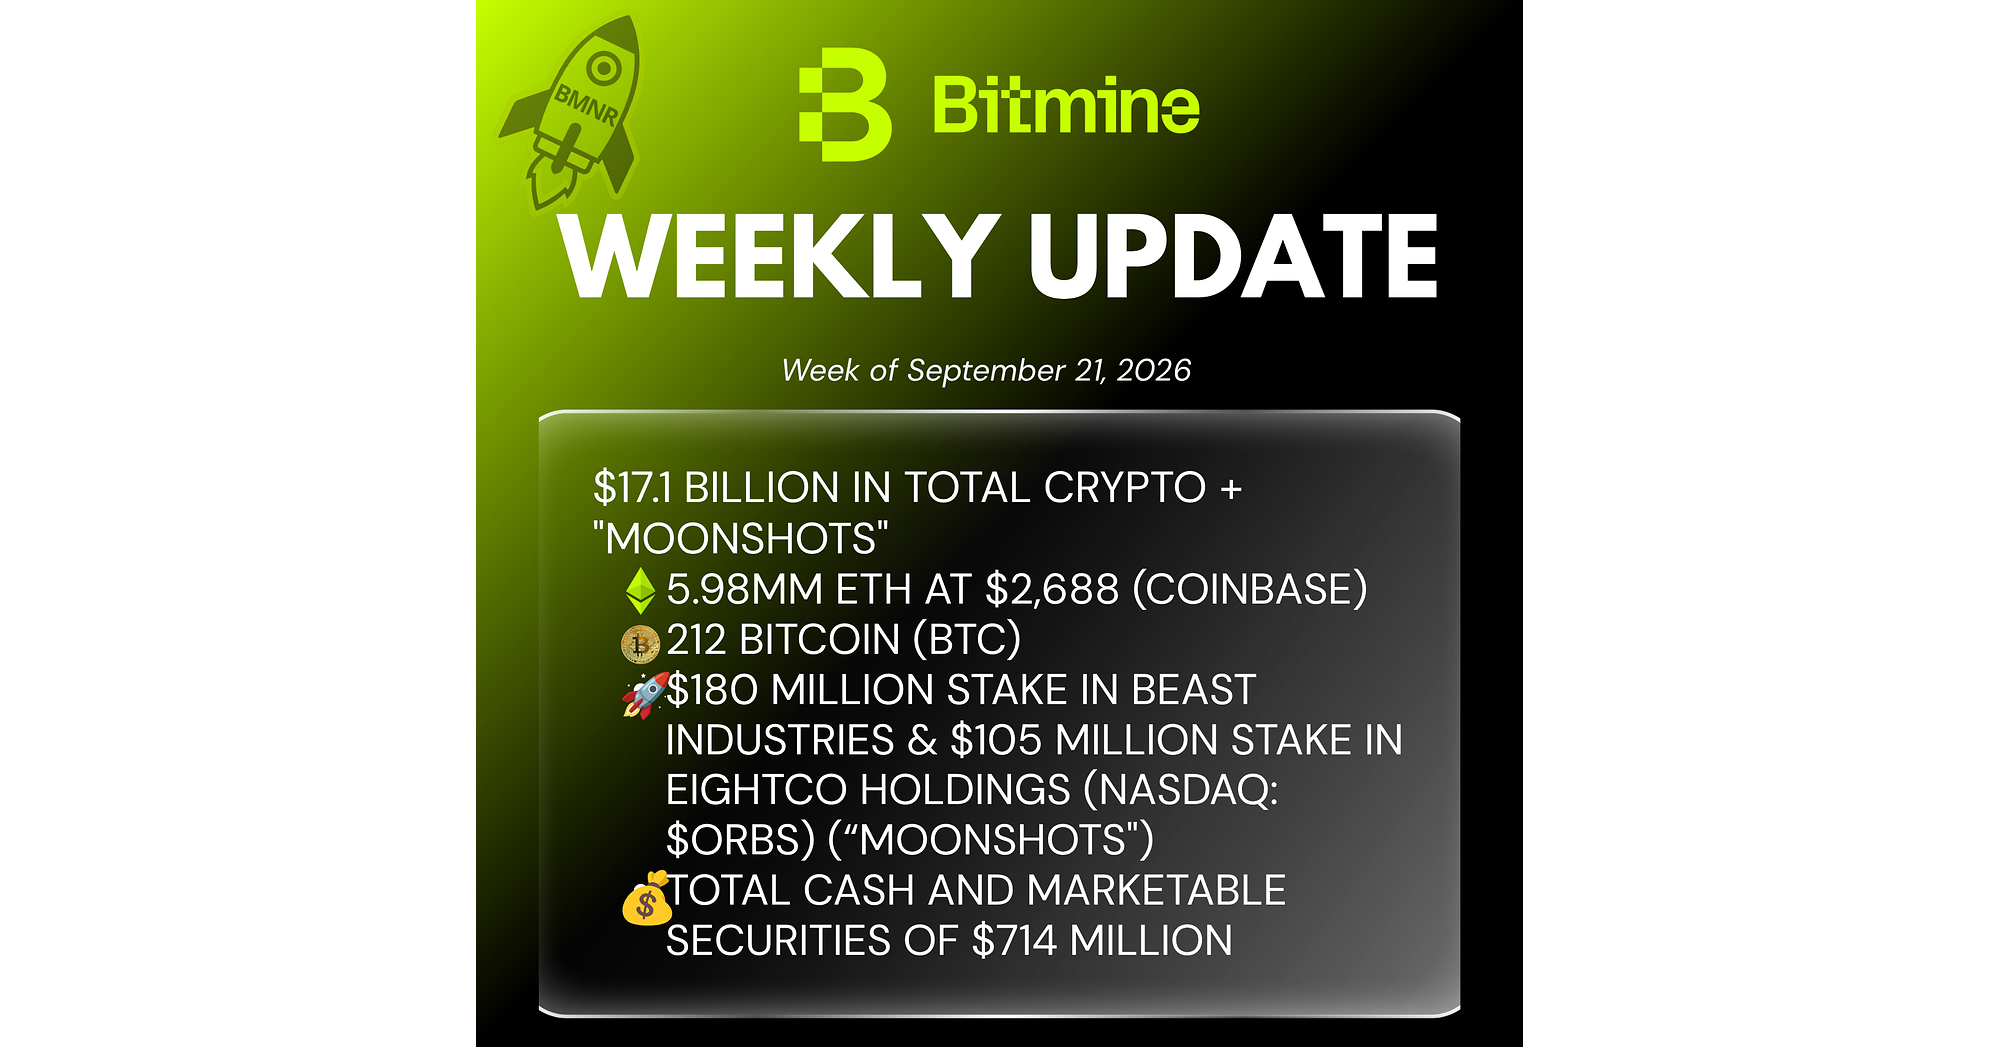
Bitmine reported total crypto, cash, marketable securities and venture holdings of $17.1 billion, including 5.98 million ETH worth about $16.1 billion and representing 4.9% of Ethereum's 122.1 million-token supply. The company bought 27,562 ETH in the past week and has staked 5.07 million ETH, or 85% of its holdings, with estimated annualized staking revenue of $357 million; management projects $421 million at full deployment. Management expects ETH's 6,519bp Q3 outperformance versus the S&P 500 to continue into Q4 as institutions potentially increase crypto allocations, though this outlook is highly dependent on volatile ETH prices and staking yields.
Analysis
BMNR is evolving from an ETH beta vehicle into a highly concentrated, yield-bearing closed-end balance sheet. The key equity variable is not the reported asset value but the premium/discount to realizable NAV after accounting for financing terms, preferred-stock seniority, custody constraints and the liquidity cost of unwinding a multi-million-token position. A large staked allocation reduces immediately saleable inventory; that supports recurring yield, but makes BMNR more reflexive in an ETH drawdown because its equity can de-rate simultaneously with the underlying asset.
The stated staking run-rate should be discounted materially: annualizing a seven-day validator yield ignores protocol reward variability, downtime/slashing exposure, validator economics and operating costs. Even a $350-420m gross annual yield would be low-single-digit relative to the crypto asset base, so it cannot by itself justify a persistent large NAV premium. The more consequential 6-18 month issue is concentration: an entity controlling roughly 5% of supply creates governance, regulatory and market-structure scrutiny, while sustained treasury purchases may tighten liquid ETH float and amplify both upside squeezes and downside liquidity gaps.
Near-term, the September 30 public appearance is a sentiment catalyst rather than a fundamental one; the more tradeable catalyst over 1-3 months is whether capital raising and weekly acquisition activity continue without diluting per-share ETH exposure. COIN and GLXY are cleaner beneficiaries if institutional crypto allocations broaden, since they monetize volumes, custody and capital-markets activity without BMNR's single-asset balance-sheet discount risk. The contrarian view is that the market may be pricing the treasury accumulation story twice—through ETH appreciation and an equity premium—despite a business whose recurring earnings contribution remains modest versus NAV volatility.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.62
Ticker Sentiment
Key Decisions for Investors
- Do not chase BMNR solely on the asset-value disclosure. Monitor daily disclosed NAV per diluted common share, BMNP liquidation preference/dividend terms, and the common-share premium to NAV; consider a tactical short or premium-compression hedge only if BMNR trades at a material premium to independently marked NAV and ETH momentum stalls.
- For a 1-3 month institutional-adoption expression, prefer long COIN and/or GLXY over BMNR: both retain upside to higher crypto activity while avoiding concentrated ETH treasury and staking-liquidity risk. Falsify if spot ETH advances but exchange volumes, custody balances and capital-markets issuance fail to improve over the next two reporting periods.
- Use a relative-value watch: long COIN or GLXY versus short BMNR only after confirming BMNR's NAV premium and borrow availability. The thesis is a narrowing premium rather than an outright ETH decline; close if BMNR demonstrates accretive financing that increases ETH per diluted share or if the premium remains supported through the next earnings/update cycle.
- Treat ORBS as a high-volatility look-through exposure, not a validated AI proxy. Avoid assigning strategic value to the mark until the underlying investment is independently valued and liquidity, lockups, and any economic linkage to OpenAI are disclosed; a mark-down would disproportionately challenge the quality of BMNR's non-ETH NAV.
More News
- U.S. regulators rush to write crypto rulebook after Clarity Act stalls in Senate
- Bitcoin surges past $85k as Strategy buys more coins
- ‘We believe in college’: inside Andreessen Horowitz’s $42m unaccredited academy that will charge Harvard prices without degrees
- Microsoft and Coinbase probe leads to arrest of crooks behind ‘EvilTokens’, a DIY phishing network powered by AI
- Quantum computing stocks vs. crypto stocks: a value comparison
- Strategy's Stock Has Soared 40% in the Past Month as It's Buying Bitcoins Again
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Research Workflows, Report Format Selection, and Interactive Synthesis
- Can ChatGPT Analyze a 10-K? A Verification Workflow