
Walovi Accelerates Global Push with WALOVI Singapore HQ Launch and Trio of Southeast Asia Deals
Source: PR Newswire
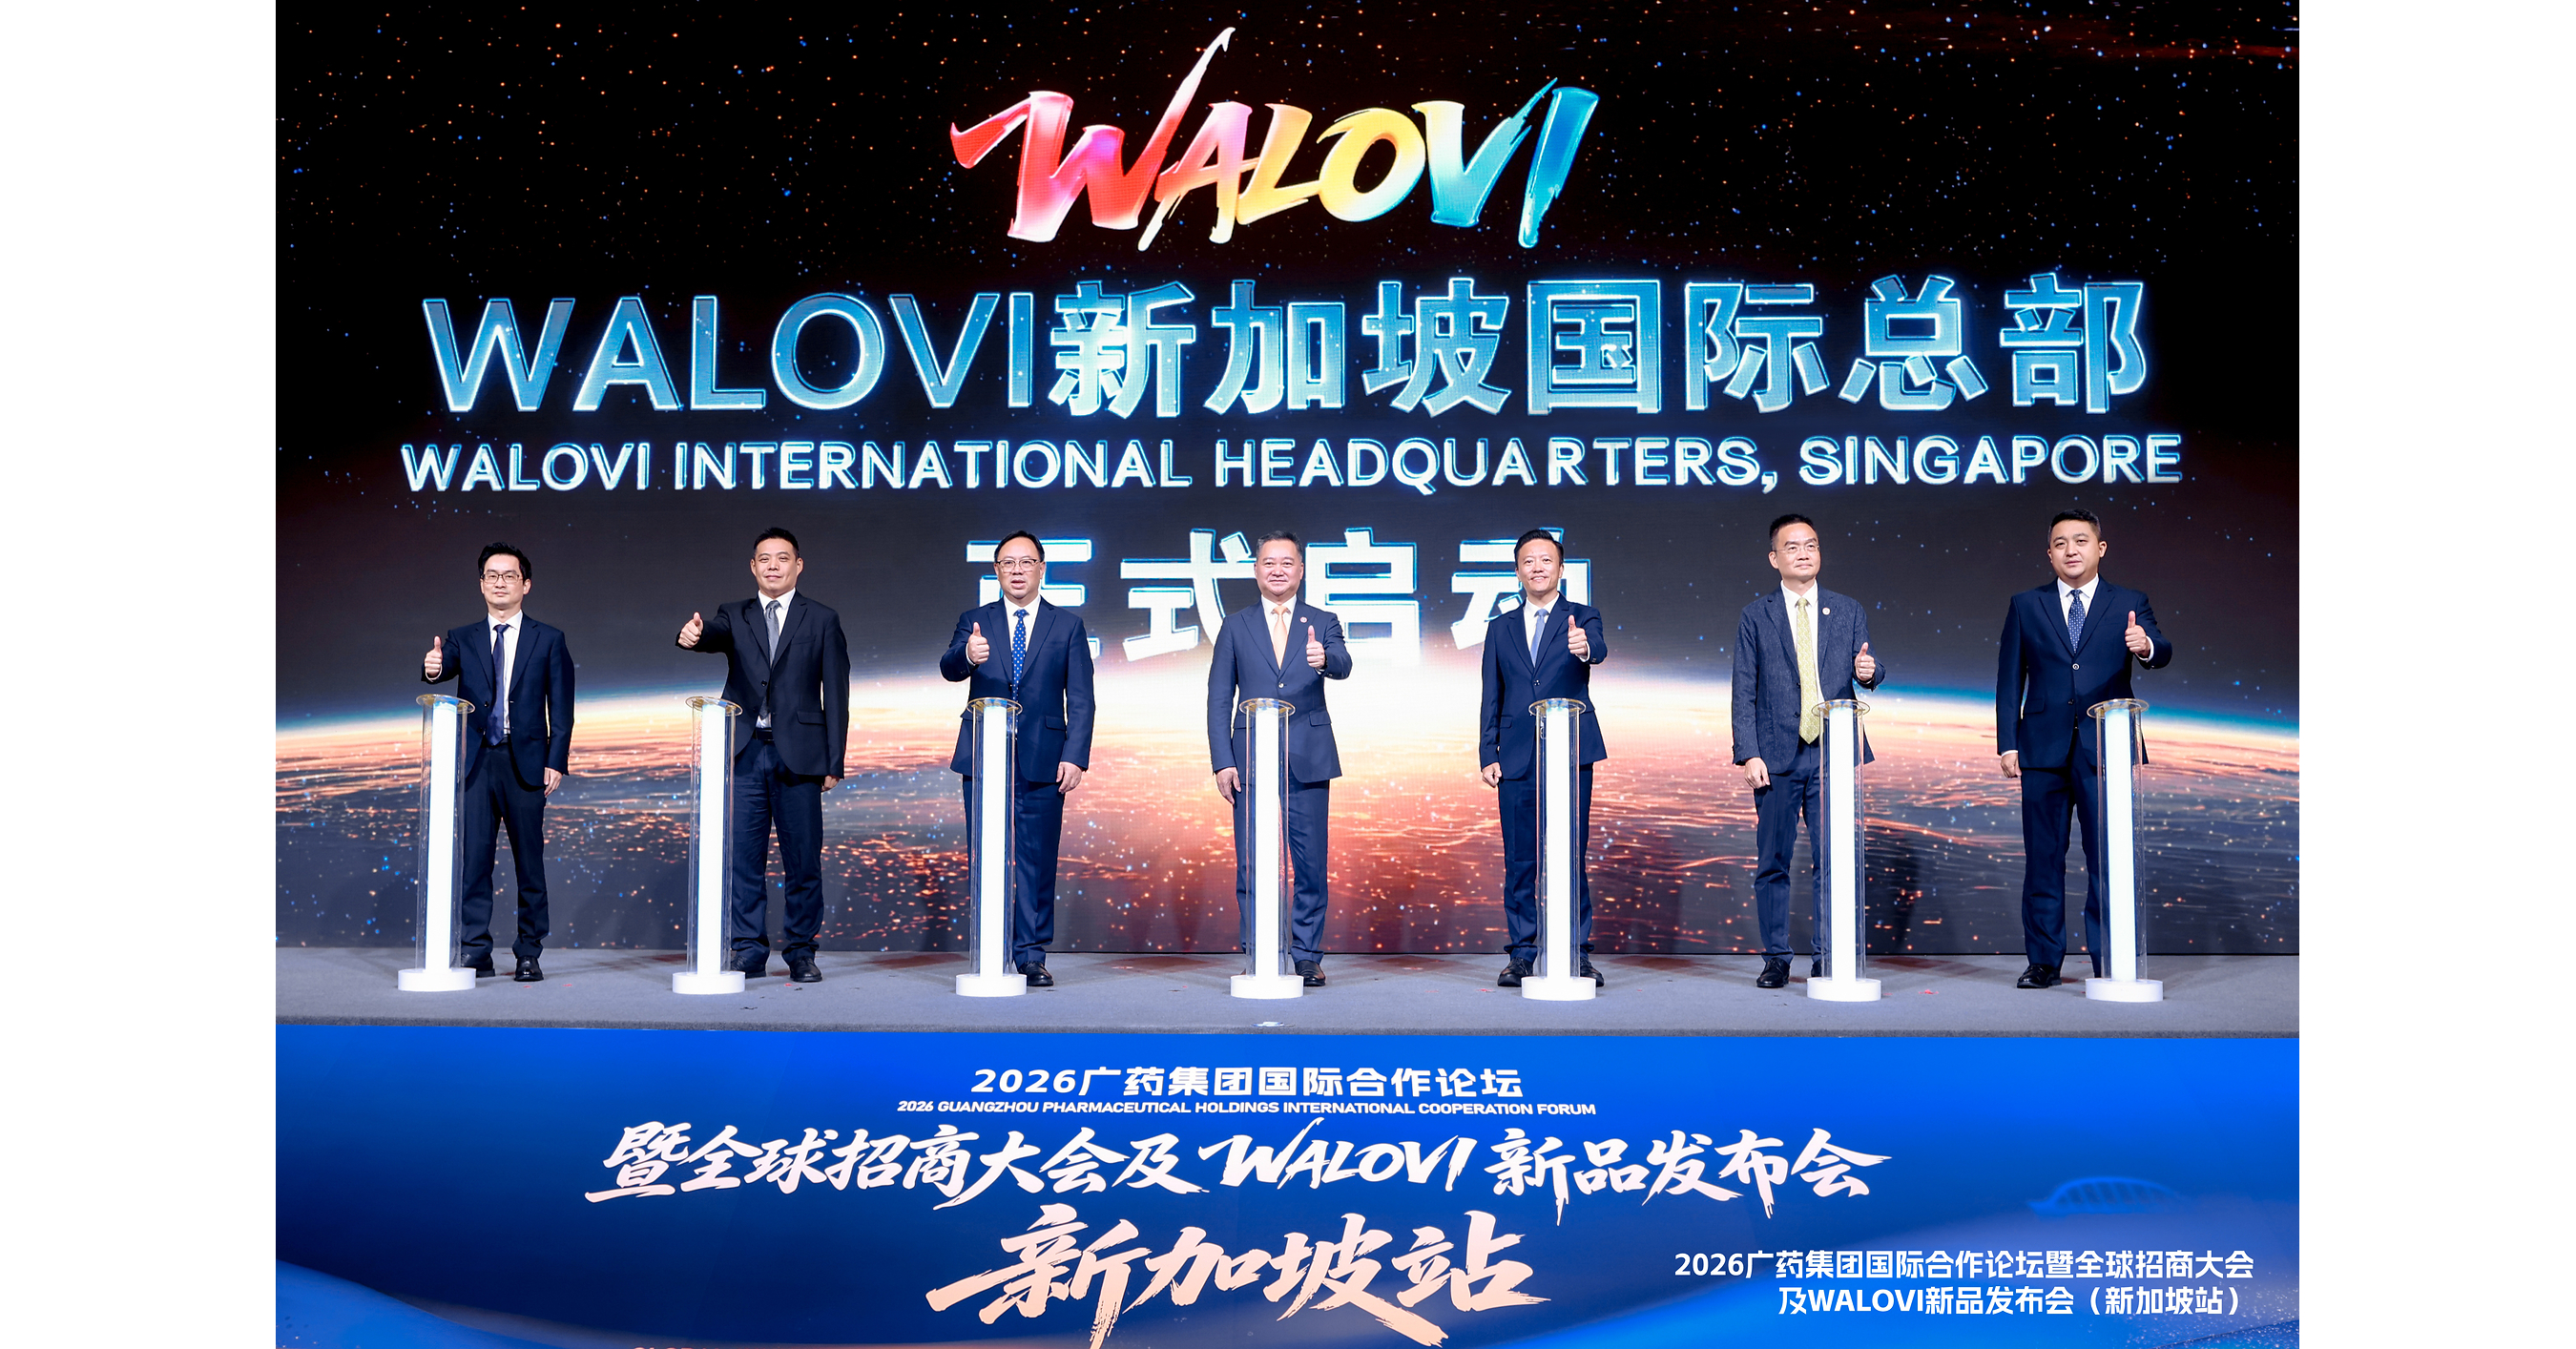
Walovi launched its WALOVI Singapore International Headquarters and introduced X-Hero, a natural energy electrolyte drink, outside China, alongside three Southeast Asia partnerships. The company cites 100% YoY export growth in Vietnam, Cambodia, and Malaysia in H1 2026 and sustained 25%+ CAGR in international sales, while positioning X-Hero for a US$21.8B functional drink market. Agreements include NTU research support, Baosteel Packaging co-manufacturing across Vietnam/Malaysia/Cambodia, and Sheng Sheng Food for Singapore retail distribution, supporting its global PCBCI expansion model.
Analysis
The investable angle is not the product launch; it is the attempt to convert a China-centric brand into a Southeast Asia operating platform. If the Singapore hub actually enables local filling and shorter replenishment cycles, the first-order benefit is lower logistics drag and better inventory turns, with a plausible 100-200 bps gross margin lift over 2-4 quarters — but only if repeat orders materialize faster than marketing spend.
Competitive impact is more likely felt by regional distributors, co-packers, and niche functional-drink entrants than by the large global beverage incumbents. For KO, PEP, and MNST, this is too small to move category share now; the more relevant second-order effect is that successful localization could pressure smaller SEA brands on shelf space and promo intensity, especially in tropical markets where functional drinks are purchased on impulse and chilled visibility matters.
The main risk is that this is a narrative-heavy expansion before proof of unit economics. Watch for working-capital creep, related-party production terms, and whether the Singapore structure adds overhead faster than it adds revenue; if SEA growth slows below high-double-digits or margins do not expand by year-end, the market should de-rate the story quickly. The contrarian view is that "natural/clean-label" is now a crowded claim set, so endorsements and university partnerships are not durable moats without demonstrable repeat consumption and channel productivity.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.22
Ticker Sentiment
Key Decisions for Investors
- No immediate trade in KO/PEP/MNST on this headline; the share-revenue impact is too small to justify factor risk.
- Put ASGXF on a watchlist only; require Q3 evidence of SEA revenue mix, gross margin expansion, and stable inventory days before taking exposure.
- If ASGXF pulls back 10-15% post-announcement and borrow/liquidity are workable, consider a starter long with a tight stop; the risk/reward is acceptable only if the market gives back the initial sentiment pop.
- Set an alert for any disclosed co-manufacturing economics in Vietnam/Malaysia/Cambodia; if fulfillment costs fall but SG&A rises faster, treat the expansion as value-destructive and avoid the name.
- Use a sell-the-rally mindset unless management can show repeat purchase data within 1-3 months; otherwise this remains a story stock, not a fundamentals trade.
More News
- Nvidia GPUs are everywhere. Here are the ways companies are accessing them
- Bank of America is bullish on these top stocks ahead of earnings
- As companies pour billions into Earth-based AI infrastructure, Google is taking the data center race off-planet
- AI's Supercharging a Scam Economy Bigger Than the Cocaine Trade
- How U.S. know-how is fracking Australia into a gas boom, from Texas oilmen to Trump’s energy secretary
- The world needs Ukraine’s grain. Its farmers are running out of reasons to plant