
Markets Bet Bank of Canada’s Macklem Has More Rate Hikes to Do
Source: Bloomberg
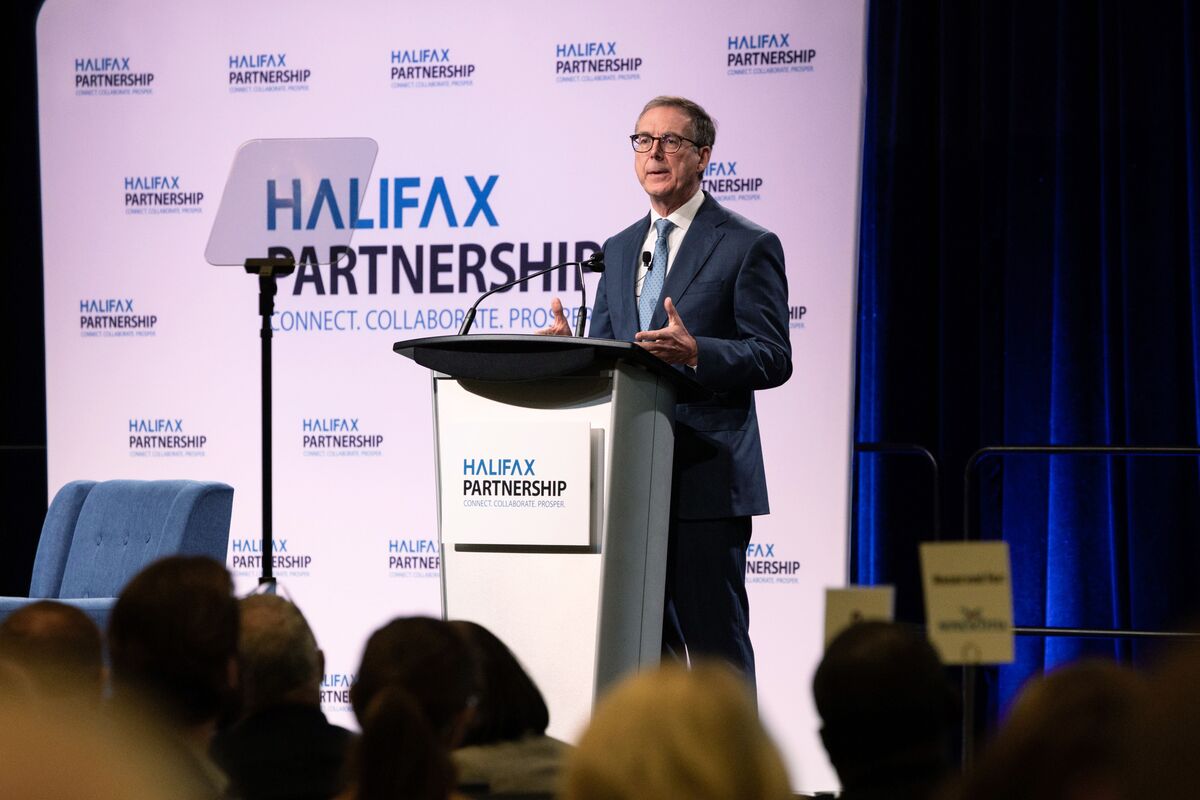
Bank of Canada Governor Tiff Macklem said his tenure has faced “one damn thing after another,” citing the pandemic, an inflation surge, a historic monetary-tightening cycle and tariffs. The accumulation of shocks complicates the Bank’s rate-setting outlook and underscores ongoing uncertainty for Canada’s inflation and growth trajectory.
Analysis
The investable issue is not the next policy meeting itself, but a widening Canadian risk premium: tariff-related price pressure can keep front-end yields elevated even as trade uncertainty weakens growth-sensitive earnings. That combination is most damaging to highly levered domestic cyclicals, residential real-estate vehicles and bank loan growth, while limiting the usual valuation support that lower rates provide. CAD is vulnerable if markets price a slower easing path without a corresponding improvement in Canada-U.S. growth differentials.
For the next 1-3 months, the key catalyst is whether core inflation, wage growth and inflation expectations decelerate enough to offset tariff pass-through. A restrictive hold accompanied by downgraded growth forecasts would be a stagflationary signal: negative for EWC and Canadian small caps, but not necessarily positive for CAD because terms-of-trade and export uncertainty matter more. Conversely, a benign CPI sequence and a clearly dovish policy pivot would favor duration-sensitive Canadian REITs and utilities, but that trade requires confirmation rather than anticipation.
Consensus may overstate the direct benefit of eventual rate cuts to Canadian banks. Lower funding costs help, but mortgage repricing, weaker consumer credit and slower loan formation can delay net-interest-income recovery by several quarters; RY, TD, BMO and CM remain more exposed to credit-loss provisions and capital-markets activity than to a simple policy-rate beta. The thesis is falsified by resilient household credit performance, accelerating mortgage originations and a sustained steepening of the Canadian yield curve.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly negative
Sentiment Score
-0.20
Key Decisions for Investors
- No outright Bank of Canada directional trade before the next Canadian CPI and labor releases; use a 2-year Canada yield move above recent post-CPI highs as an alert for renewed restrictive-policy pricing rather than pre-positioning on incomplete data.
- For a 1-3 month defensive expression, consider long USD/CAD via short FXC only if Canadian core CPI reaccelerates while Canadian growth-surprise indicators weaken; target a 3-5% FXC decline with a 1.5-2% stop, as a dovish surprise would reverse the setup.
- Pair trade watch: short EWC versus long U.S. quality/low-volatility exposure (SPLV) if Canadian growth revisions turn negative while inflation expectations rise. This isolates Canada-specific stagflation risk; cover if Canadian PMIs and bank lending data improve for two consecutive months.
- Avoid adding to RY, TD, BMO or CM solely on prospective easing. Reassess for a long position only after provision-for-credit-loss guidance stabilizes and mortgage/consumer delinquency trends stop worsening; the cleaner confirmed-easing beneficiaries would be Canadian rate-sensitive real estate and utilities proxies such as XRE, FTS and EMA.
More News
- Great Bond Shakeout Locks In a 5% World ‘Until Something Breaks’
- Boom or bust? The case for and against panicking about 5% yields
- Bond market alarms are ringing on Wall Street. Here's what's ahead
- Bonds Stabilize as Oil Retreats
- 10-year Treasury yield hit a 19-year high—and some investors see opportunity to buy bonds
- Warsh's regime change at the Fed pushes ahead – and meets resistance
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Software for Buy-Side Teams: Build the Research Stack
- Augmented Intelligence: AllMind, Elevate Human Judgement With an Accessible, Powerful, Data-Driven Financial AI Toolkit