
Hitachi Energy invests $479 million CAD to bring critical transformer manufacturing capability to Canada
Source: PR Newswire
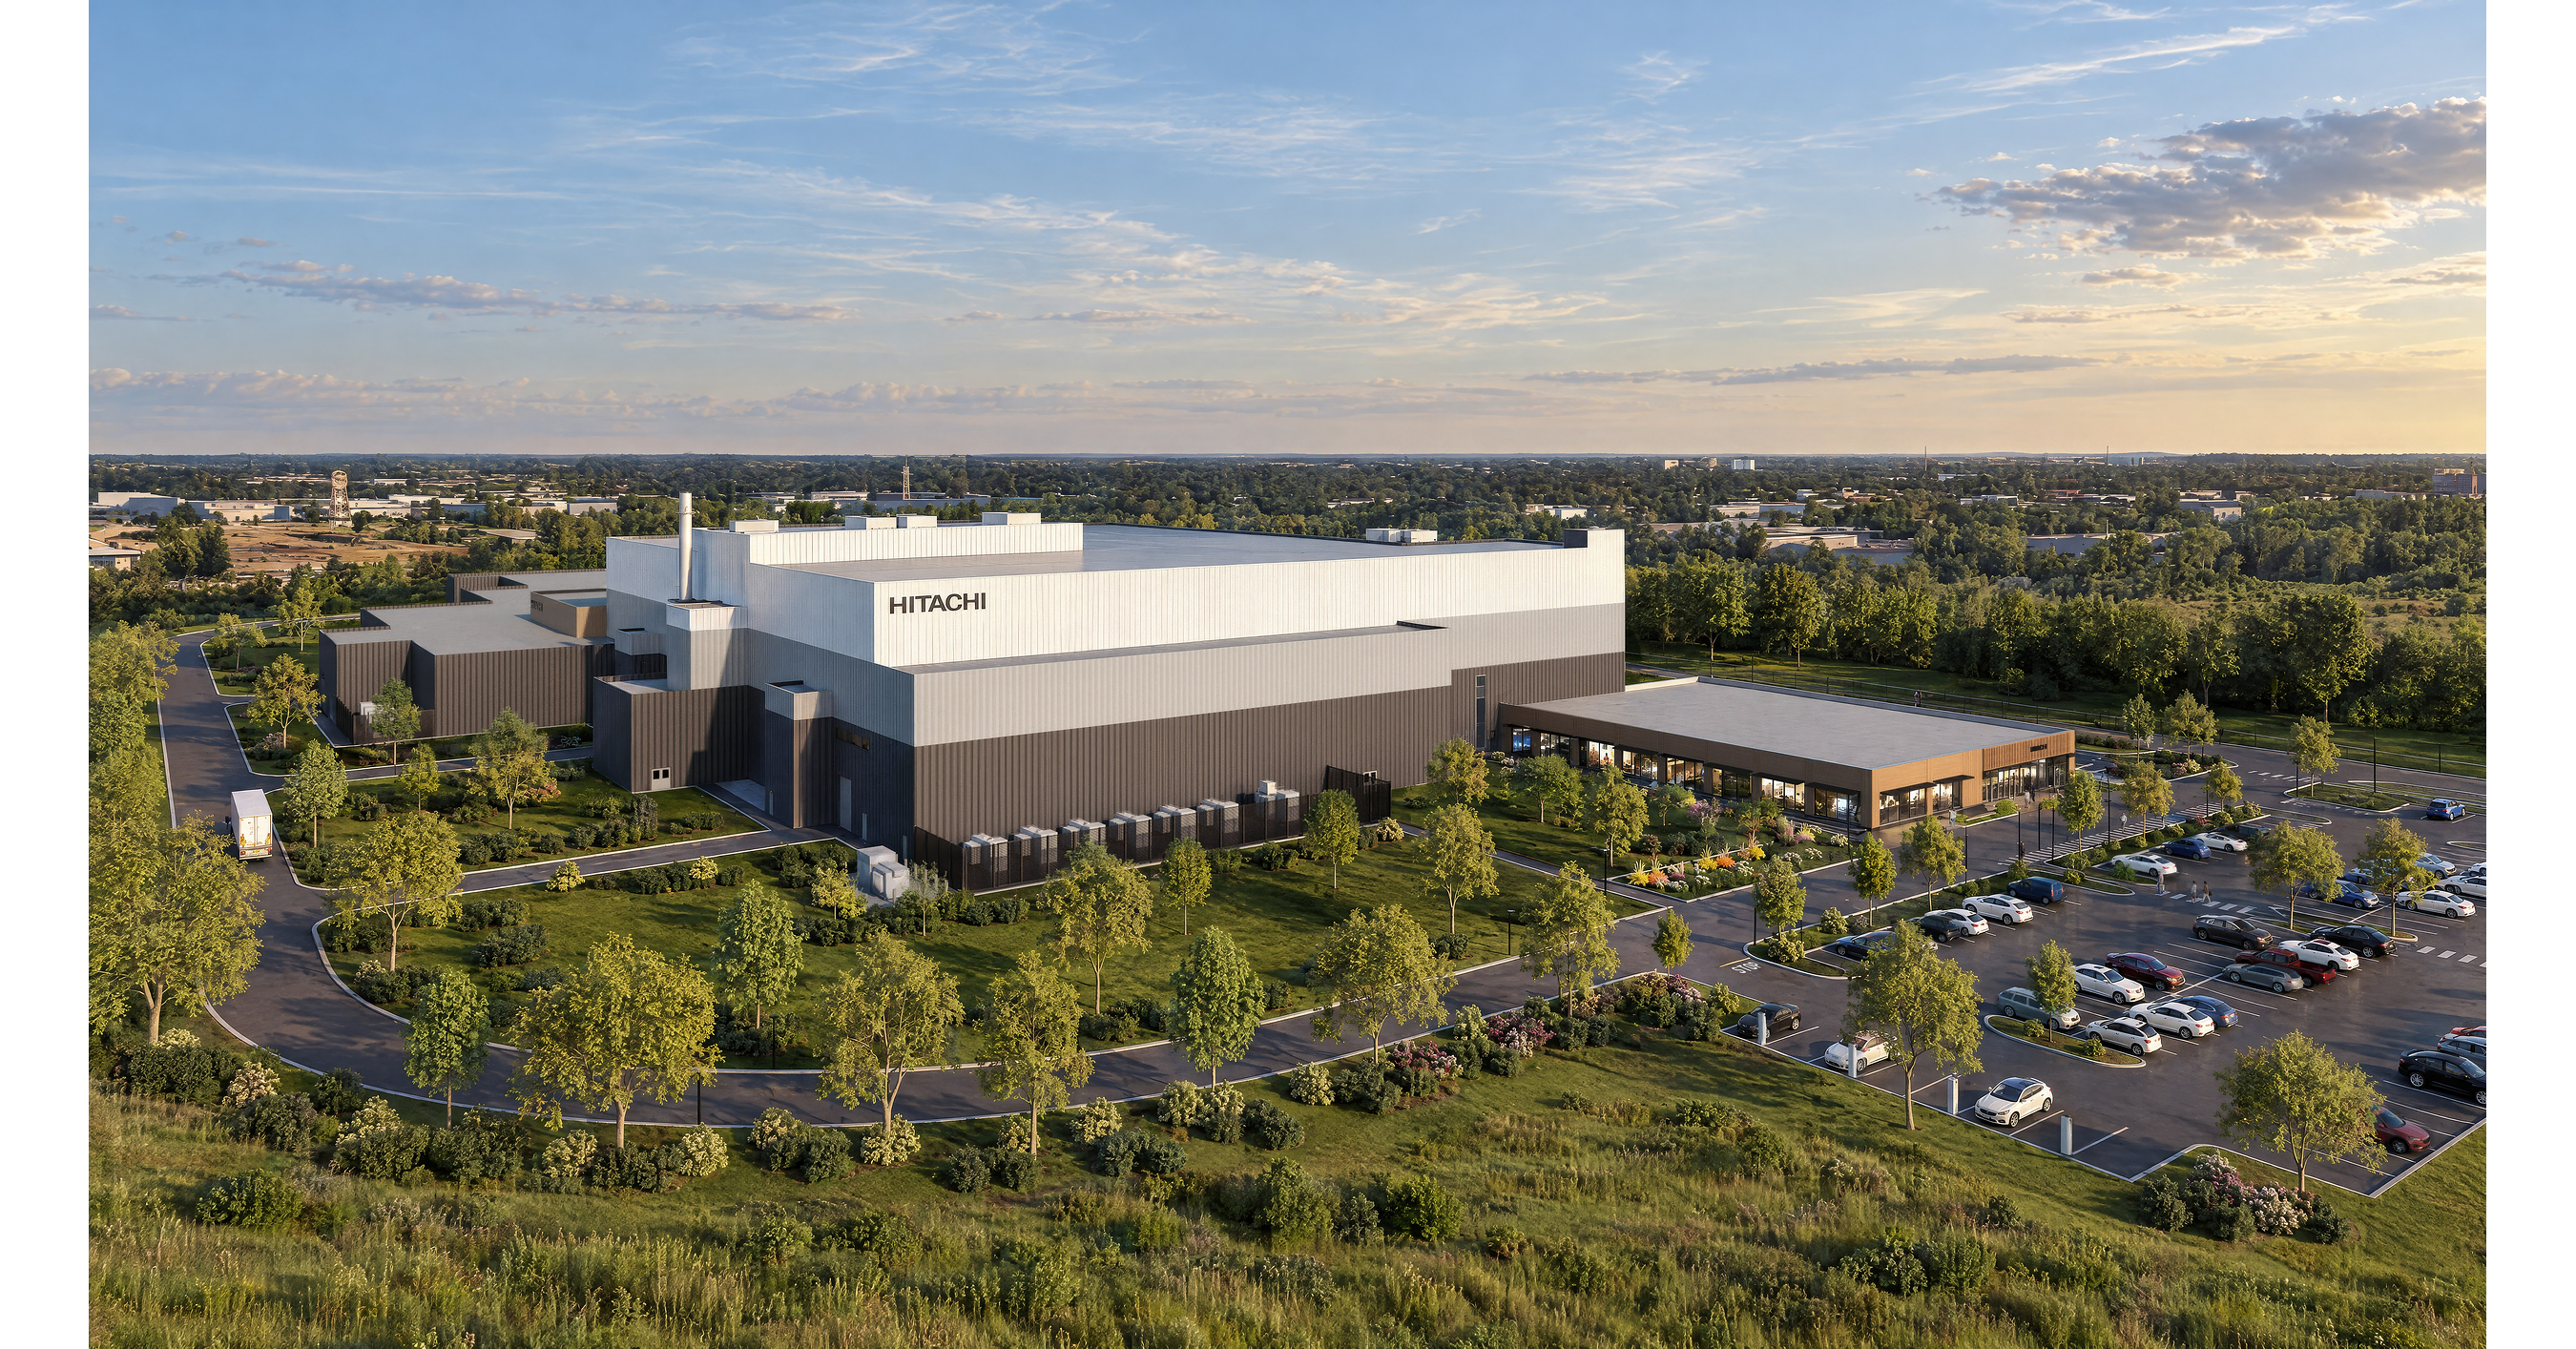
Hitachi Energy will invest CAD 479 million (more than USD 330 million) in a London, Ontario transformer-insulation factory, expected to be completed by 2028 and create over 100 permanent skilled jobs. The facility will establish Canada’s first pressboard manufacturing line, addressing a supply constraint for transformer production; federal and provincial support totals up to CAD 50 million. The project is part of Hitachi Energy’s commitment to invest more than USD 2 billion in North American supply chains through 2027.
Analysis
The market mechanism is supply assurance, not an immediate step-change in transformer output. Pressboard is one constraint among several; without disclosed capacity, customer commitments, and qualification timelines, this project cannot yet be translated into a meaningful reduction in transformer lead times or a revenue uplift for Hitachi Energy. Commissioning is not expected until 2028, so near-term impact for Hitachi, Ltd. is principally execution capex, with operating benefits deferred and immaterial to value absent evidence of scale relative to the parent. Public support partially offsets project cost but does not remove construction, ramp, or utilization risk.
For the next 1–3 months, watch for capacity details, customer offtake, and any update to Hitachi’s investment or return guidance. Over 6–18 months, successful qualification could improve supply reliability for North American transformer makers and reduce exposure to imported insulation; however, it may simply shift the bottleneck to other components, labor, or transformer assembly. Incumbent insulation suppliers could face incremental pricing pressure if new capacity is substantial, but that conclusion depends on undisclosed output and market share.
The contrarian point: domestic-supply-chain language may be priced as broad infrastructure capacity, while this is a single component facility with a long lead time. The thesis strengthens only if commissioning stays on schedule and customers qualify the product; delays, weak utilization, or continued transformer lead-time constraints would falsify the near-term bottleneck-relief case.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.55
Key Decisions for Investors
- No immediate directional trade in Hitachi, Ltd.: the earnings contribution and project scale relative to the parent are not disclosed, while benefits are several years away.
- Add the project to a 2027–2028 supply-chain watchlist. Reassess on disclosed annual capacity, customer qualification/offtake, commissioning milestones, and any change to Hitachi’s capex or return guidance.
- Avoid a broad long on transformer OEMs solely on this announcement. Consider the supply-relief thesis only if transformer lead times or delivery guidance improve; persistent delays despite added insulation supply would indicate other bottlenecks dominate.
- Track incumbent insulation suppliers for pricing or order commentary, but defer any short until capacity, market share, and customer substitution evidence establish a credible earnings threat.
More News
- Why did CoreWeave stock get crushed this week? Look to this corner of the debt market for clues
- AI stock sell-off ramps up over debt-fueled data center spending fears: ‘Full-blown crisis of confidence'
- All the news about the iPhone Duo
- The Tesla Roadster should go into production in 2028, but don't get your hopes up
- Trump rules out using a nuclear bomb on Iran: Why that matters
- Ukraine advances in occupied Donetsk as Trump hands Putin diesel deal
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Introducing AllMind: A New Data & AI Workspace for Institutional Investors
- AI Tools for Private Equity Due Diligence: A Buyer Workflow