
Jung Saem Mool Beauty Marks Sephora Launch with Times Square Takeover and Nationwide Consumer Activations
Source: PR Newswire
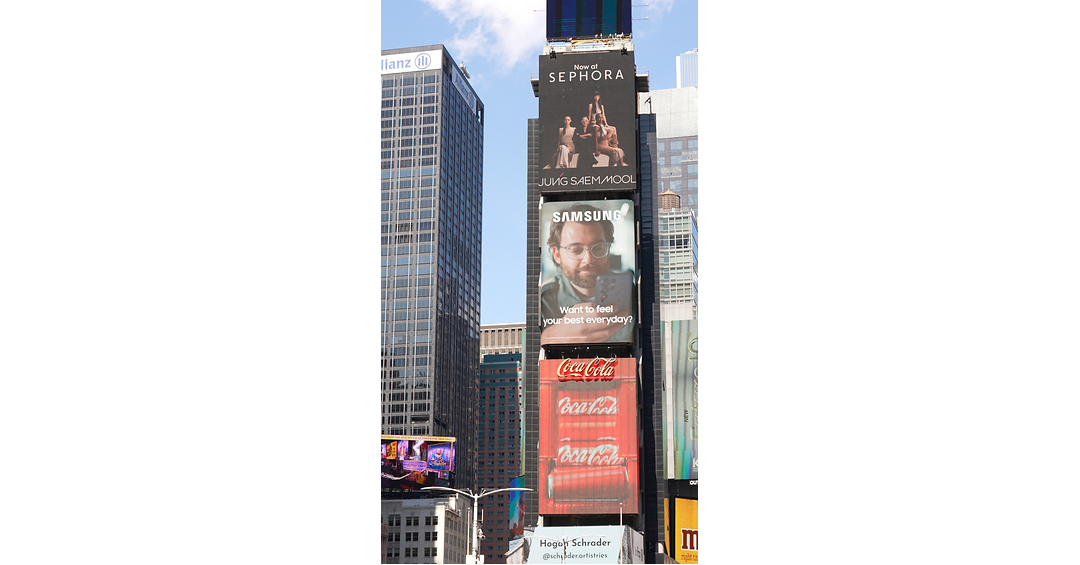
Jung Saem Mool Beauty expands U.S. distribution by launching at Sephora on Aug. 21, 2026, with 10 exclusive cushion shades for the Essential Skin Nuder Cushion and availability across Sephora.com plus 34 Sephora stores. The retailer push is backed by a multi-city marketing campaign including a Times Square digital takeover (Aug. 24–Sep. 20) and in-person activations in New York and Los Angeles (including a Van Leeuwen collaboration and a Sephora x creator master class). The article is promotional and should be incremental for brand awareness rather than a near-term market-moving financial catalyst.
Analysis
Treat this as a brand-credentialing event, not a size-event. The real economic value is in top-funnel awareness and eventual conversion, while the immediate revenue contribution to the listed names is likely immaterial. For AMZN, the only plausible read-through is improved beauty search and marketplace halo: when a niche prestige brand gains a specialty-channel stamp of approval, online conversion often improves because pricing power looks more defensible. COST is a much weaker beneficiary; any spillover into warehouse beauty is delayed by quarters and, if anything, likely comes with more promotional pressure than margin uplift.
The broader mechanism is category migration. Korean complexion brands moving into a premium specialty door tends to force incumbents to widen shade ranges and sharpen claims, which can compress economics for undifferentiated players while rewarding authentic artistry-led positioning. That effect is more likely to show up in sell-through data and assortment changes over the next 1-3 months than in the opening print today. If there is any stock reaction in AMZN or COST, it is more likely sentiment-driven than fundamental.
Contrarian view: the market may be overrating the launch as proof of durable U.S. demand. These campaigns are good at generating trial, but repeat purchase and replenishment are what matter for shelf productivity and eventual reorders. The thesis breaks if the initial spike does not translate into sustained rank or if the brand needs heavy promo support; watch 4-8 week search, ranking, and store-level replenishment metrics as the real confirmation signal.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.12
Ticker Sentiment
Key Decisions for Investors
- Stay flat AMZN and COST for now; the implied earnings impact is too small to justify an event-driven position unless channel data turns up meaningfully over the next 4-8 weeks.
- If forced to express the read-through, use a small long AMZN / short COST pair over 1-3 months: the online marketplace has more optionality from beauty discovery and higher-frequency basket effects, while COST’s beauty shelf is less likely to see incremental margin lift. Keep sizing small and cut if AMZN beauty search/share does not inflect.
- Set an alert on Amazon beauty search rank and third-party seller velocity for comparable premium complexion products; a sustained lift would be the earliest sign that the launch is creating a broader halo. No rank improvement after 30-45 days would falsify the thesis.
- Watch for any follow-on Sephora door expansion or Amazon/Costco assortment changes; that would matter more than the launch itself and would justify revisiting a larger long AMZN thesis or a neutral COST stance.
More News
- ‘Never seen anything quite like it’: How rural Pennsylvania’s $165 million data center fight became representative of the bipartisan battle against AI
- OpenAI Dot vs. Meta Muse: How do these AI agents compare?
- Can the AI industry persuade data center opponents by getting rid of NDAs?
- Forget Chasing Volume. Here's the Most Active Stock I'd Actually Hold for 5 Years.
- As Shoppers Trade Down, These 5 Brands Still Have Pricing Power
- Marvell's Outlook Says Revenue and Earnings Could 10x in 5 Years. Here's Why the Stock's a Bargain Even If It Falls Short.