
Martin Guitar Unveils the Refreshed 16 Series, a Bold New Lineup Built to Command the Stage
Source: PR Newswire
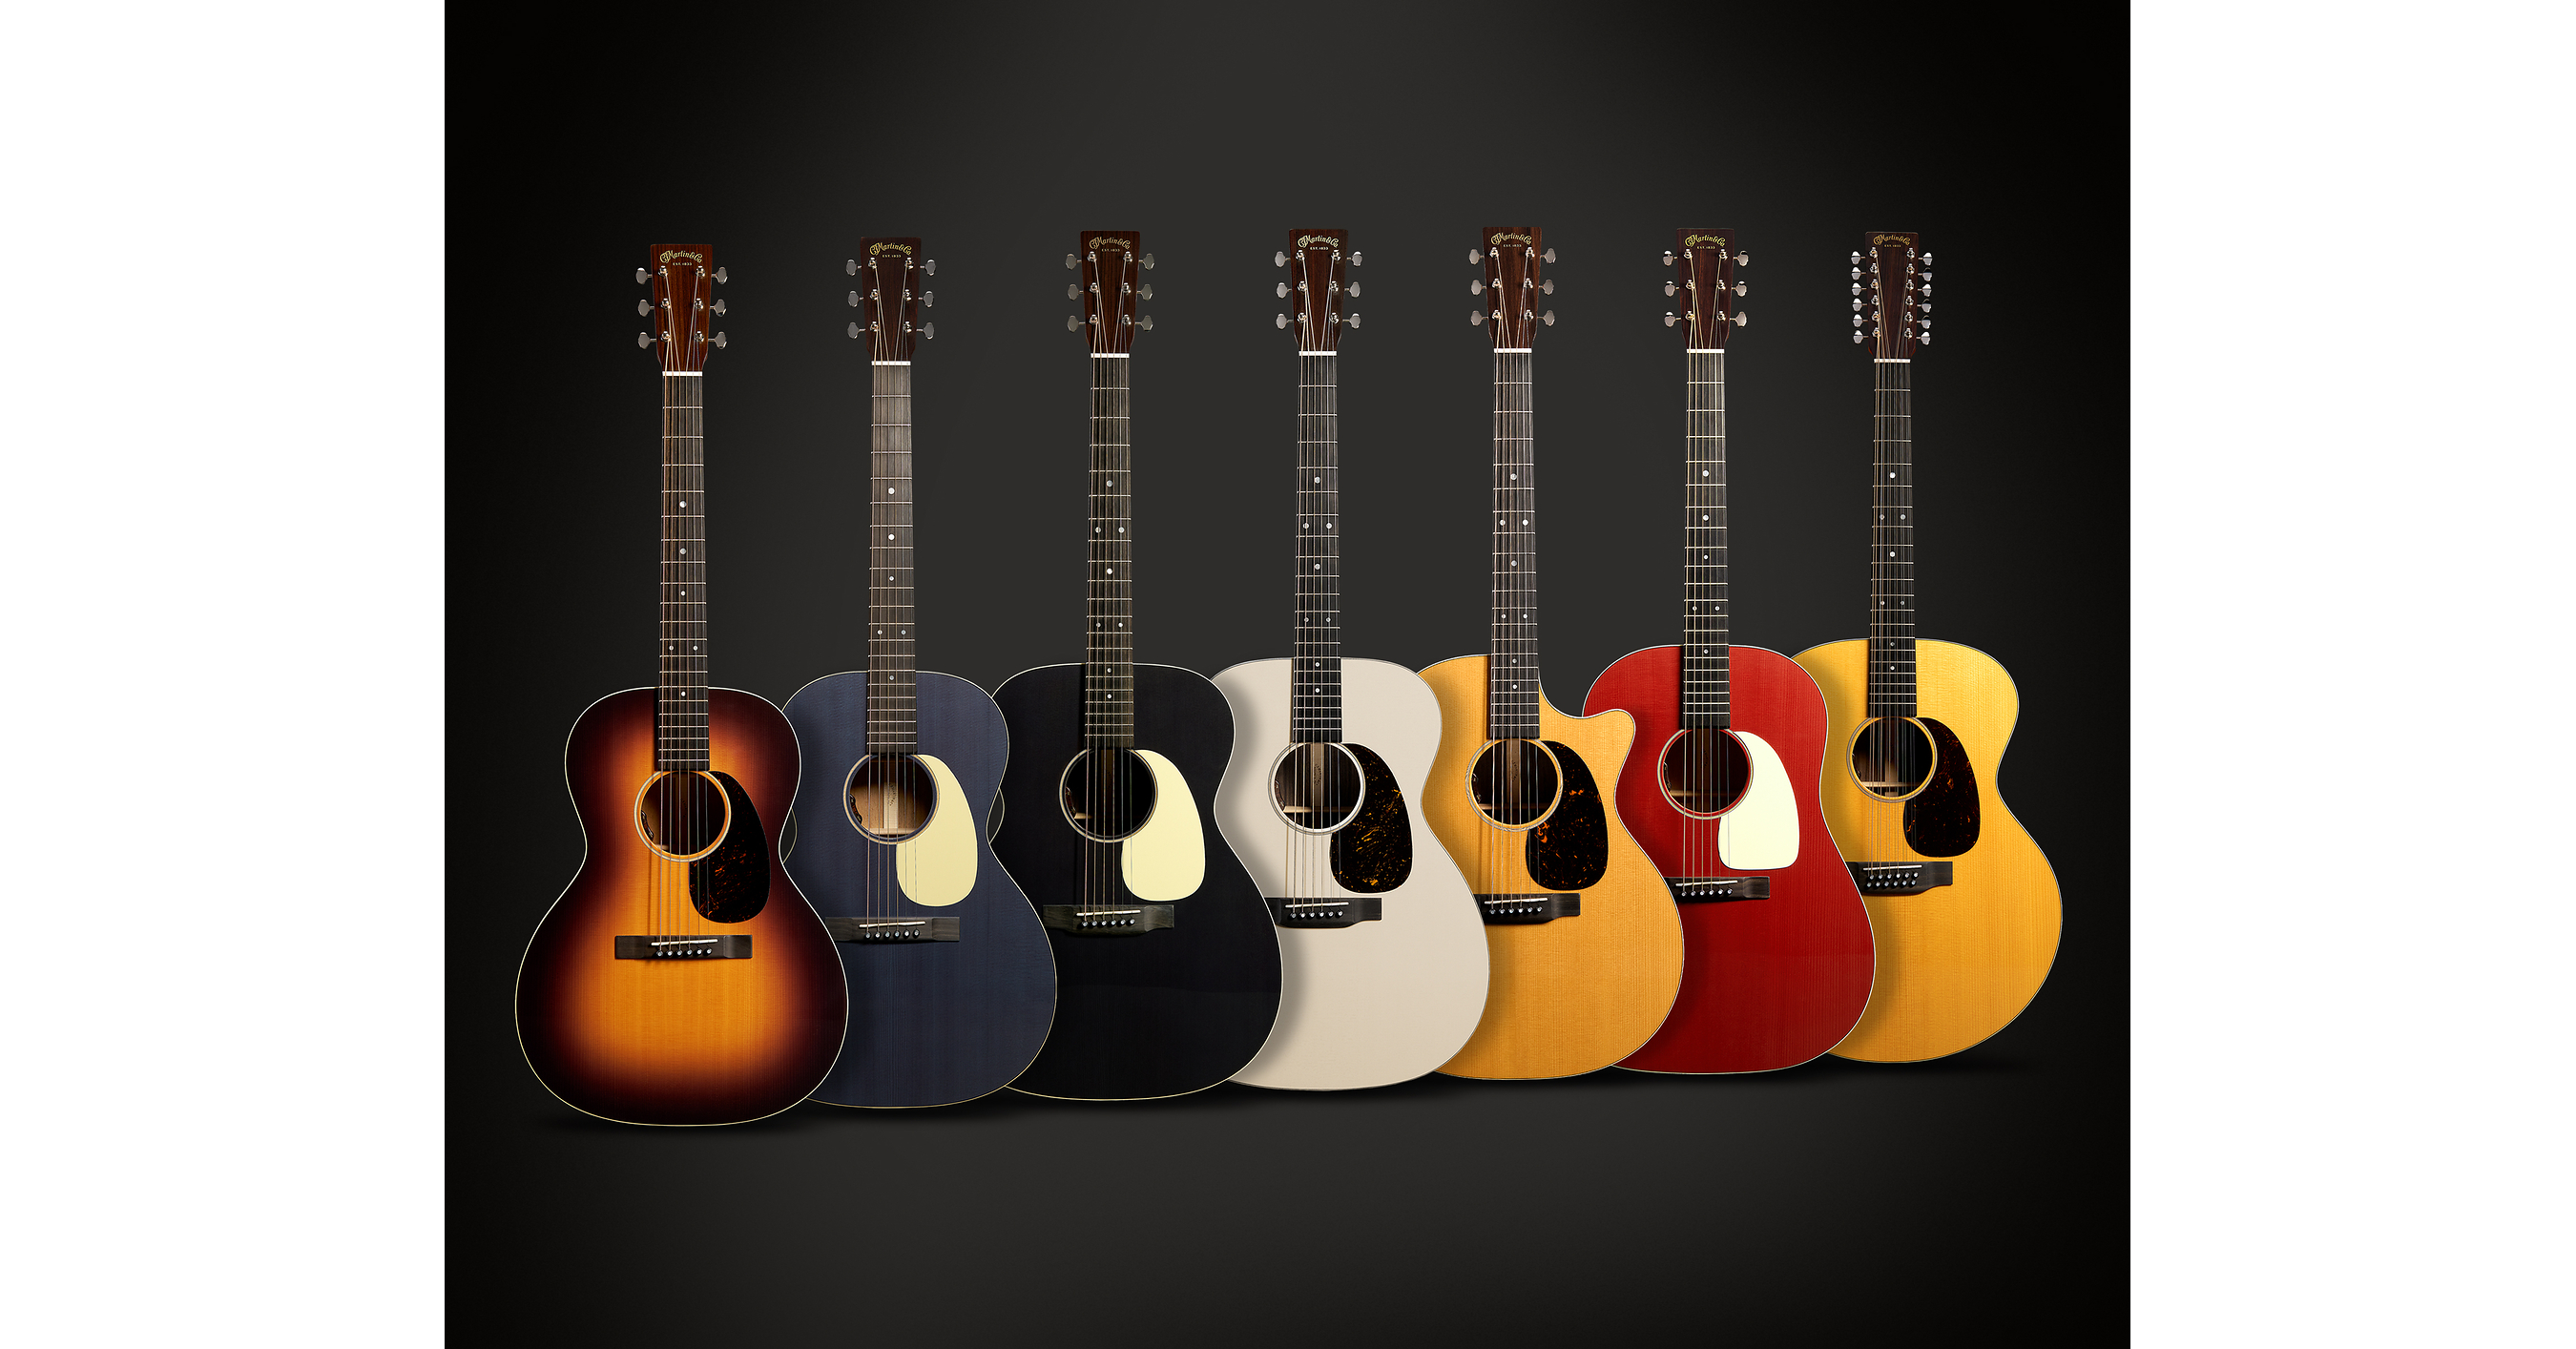
C.F. Martin & Co. launched its refreshed 16 Series of all-solid-wood acoustic-electric guitars on September 15, 2026. The lineup adds new body shapes, including Martin's first short-scale sloped-shoulder Dreadnought, gloss-top color options, and standard L.R. Baggs Element electronics. The release also includes limited accessories and lifestyle merchandise, but provides no pricing, sales outlook, or financial impact guidance.
Analysis
This is not a public-equity catalyst: C.F. Martin is privately held, and the launch provides no disclosed unit, pricing, retailer-order, or margin data. The primary implication is competitive rather than investable—an upgraded mid-premium acoustic offering raises promotional and product-refresh pressure on Fender Musical Instruments (private), Yamaha (7951 JP), Gibson (private), and Roland/BOSS (7944 JP), but the likely revenue effect is immaterial relative to Yamaha and Roland’s diversified bases.
The relevant second-order read-through is whether premium acoustic demand is broadening among hobbyist buyers despite discretionary-spending pressure. All-solid-wood construction and standard onboard electronics increase material and labor intensity; if retail pricing does not rise proportionately, this is more likely a brand-defense move than a margin-accretive one. Sustained discounting at major instrument retailers would instead signal channel inventory risk and weak sell-through.
Over the next 1-3 months, monitor Guitar Center/major dealer availability, advertised discounts, and used-market pricing for comparable Martin, Taylor, and Gibson acoustics. A clean sell-through could support a modest premium-instrument demand narrative, but there is no direct listed-company earnings sensitivity sufficient to justify a position. Over 6-18 months, the more meaningful structural issue is whether differentiated acoustic products can offset substitution toward digital music-production gear, where Roland has more direct exposure.
Contrarian view: visually differentiated product launches can attract attention without expanding the addressable market; they may cannibalize adjacent Martin models. The thesis turns constructive only if independent dealer data show full-price sell-through and replenishment rather than merely broad SKU availability.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Key Decisions for Investors
- No standalone trade recommendation; treat this as an industry-demand watch item, not a catalyst for listed equities.
- Monitor Yamaha (7951 JP) and Roland (7944 JP) quarterly instrument-segment commentary for premium acoustic demand, dealer inventory, and gross-margin trends over the next 1-2 reporting cycles.
- Set an alert for evidence of broad 10%+ retail discounting on new premium acoustic models during the next holiday selling season; that would reinforce discretionary-demand and channel-inventory risk rather than validate a premiumization thesis.
- Only consider a tactical long in Roland if subsequent results show growth in guitars/music-creation hardware with stable gross margin; falsify on guidance reduction or dealer inventory build.
More News
- Grab aims for 'next level' in financial services with purchase of buy-now pay-later platform Atome
- China's AI leaders keep quiet despite U.S. 'publicity' on tech risks
- Exclusive-Malaysia talks to rival airlines as it monitors AirAsia’s financial health, sources say
- China’s slower loan growth is the new normal, central bank governor says
- ‘The end of the keyboard is near’: Christian Klein predicts voice translation will be the next workplace advantage
- Axon prices $1 billion convertible notes offering due 2031