
Spoločnosť Shanghai Electric získala prvú zahraničnú objednávku na vysokovýkonné plynové turbíny pre malajzijský projekt s výkonom 500 MW
Source: PR Newswire
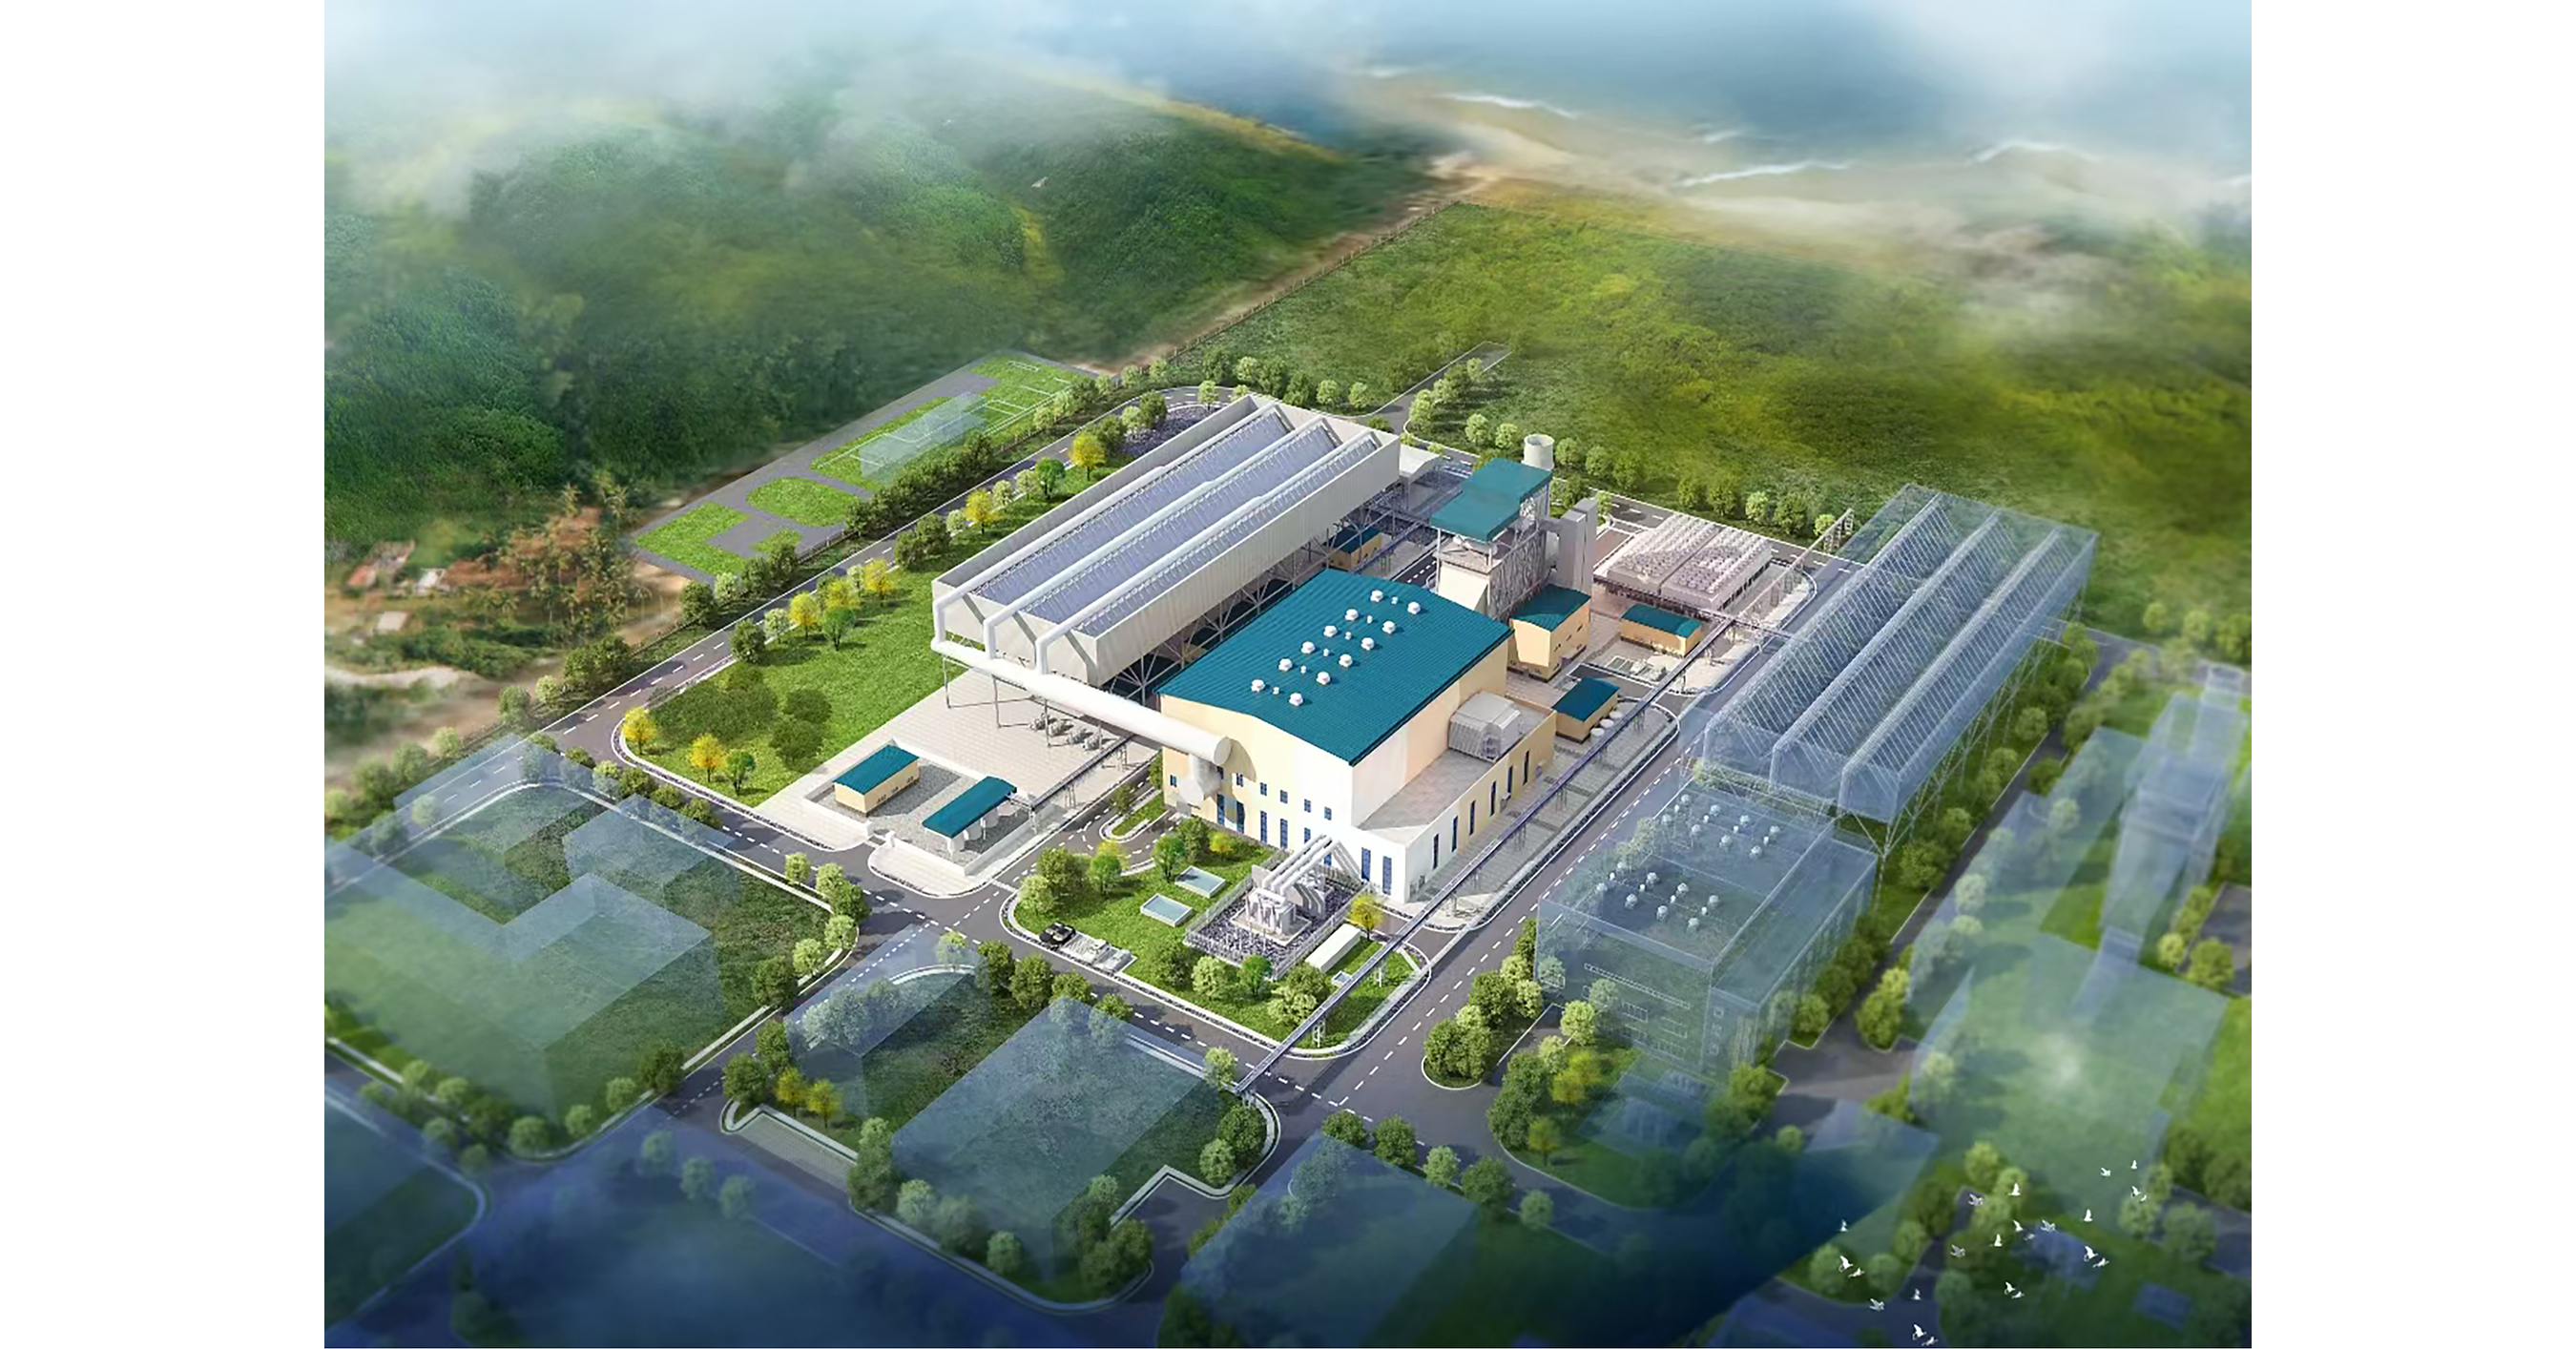
Shanghai Electric won its first overseas order for high-capacity gas turbines, securing the 500MW Unit 3 contract for the Samalaju CCGT project in Sarawak, Malaysia. The turnkey EPC award includes a 25-year long-term service agreement covering key equipment, all of which will be manufactured internally by Shanghai Electric. The company has delivered 103 turbine units totaling more than 21GW and reported additional interest from developers in Indonesia, Thailand, the Philippines and Vietnam, supporting its overseas growth outlook.
Analysis
The economic signal is less the initial EPC award than whether Shanghai Electric can convert a reference project into a Southeast Asian service fleet. A successful commissioning would validate a lower-cost Chinese alternative in a concentrated heavy-duty turbine market, pressuring Siemens Energy (ENR), GE Vernova (GEV) and Mitsubishi Heavy (7011 JP) most in price-sensitive markets. The long-duration service component creates recurring, high-margin revenue only after reliability is demonstrated; near-term project revenue is likely lower-quality EPC revenue with working-capital and execution risk.
For GEV and ENR, the direct earnings effect is immaterial, but the strategic read-through matters over 6-18 months: Southeast Asian CCGT procurement could become more competitive as Chinese financing, equipment integration and local-content packages are bundled. The first pressure point should be new-build equipment pricing rather than incumbent service contracts, where installed-base switching costs and outage-risk aversion remain substantial. Suppliers exposed to Western turbine platforms are more insulated than OEMs, while regional gas and LNG infrastructure beneficiaries could gain if dispatchable gas capacity continues to fill the gap created by intermittent renewable build-outs.
Consensus may overstate immediate disruption. A single overseas project does not establish bankability, especially absent independently verified heat-rate, availability, emissions and forced-outage data over multiple operating seasons. The key 1-3 month catalyst is disclosure of contract value, financing source, guarantees and notice-to-proceed timing; the 2028 delivery target means any meaningful fleet-service economics lie years out. Thesis fails for Chinese entrants if financing or export controls delay execution, or if reliability guarantees force margin provisions and prevent follow-on orders.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.62
Key Decisions for Investors
- No directional trade in Shanghai Electric without contract value, expected gross margin, advance-payment terms and project financing; set an alert for these disclosures and for confirmed Southeast Asian follow-on awards over the next 3-12 months.
- Maintain GEV and ENR exposure only with a watch on Southeast Asia tender outcomes: consider trimming new-build-margin assumptions if Chinese OEMs win two or more additional 200MW+ CCGT contracts before 2028; do not extrapolate from one award into current-year earnings.
- For a 6-18 month thematic expression, prefer a basket long of Asian gas-infrastructure and LNG-regasification beneficiaries against a broad regional utility hedge, rather than shorting turbine OEMs. Use a 10-15% adverse move or evidence that renewable-plus-storage economics displace planned CCGT projects as the risk limit.
- Monitor Malaysian and Indonesian project-finance spreads and gas-supply commitments. Wider funding spreads or uncontracted fuel supply would impair the broader CCGT pipeline and invalidate a regional equipment-order growth thesis before turbine delivery begins.
More News
- Trump says U.S. may keep Iranian oil 'like Venezuela' as Gulf-Iran Hormuz talks stall
- Baker Hughes sees no slowdown in energy projects despite higher rates as AI buildouts stoke LNG demand
- U.S. stock futures slide on calls to slow AI development, M.East escalation
- Diplomacy stumbles with postponement of meeting on Strait of Hormuz proposal
- Oil prices rise after Saudi Arabia shut down critical pipeline that bypasses Strait of Hormuz
- Z.ai shares tumble over 10% after $5 billion fundraising, its second major raise in two months