
Cousins Roofing, Siding & Decks on Pace for $20 Million to $25 Million in 2026 Revenue
Source: PR Newswire
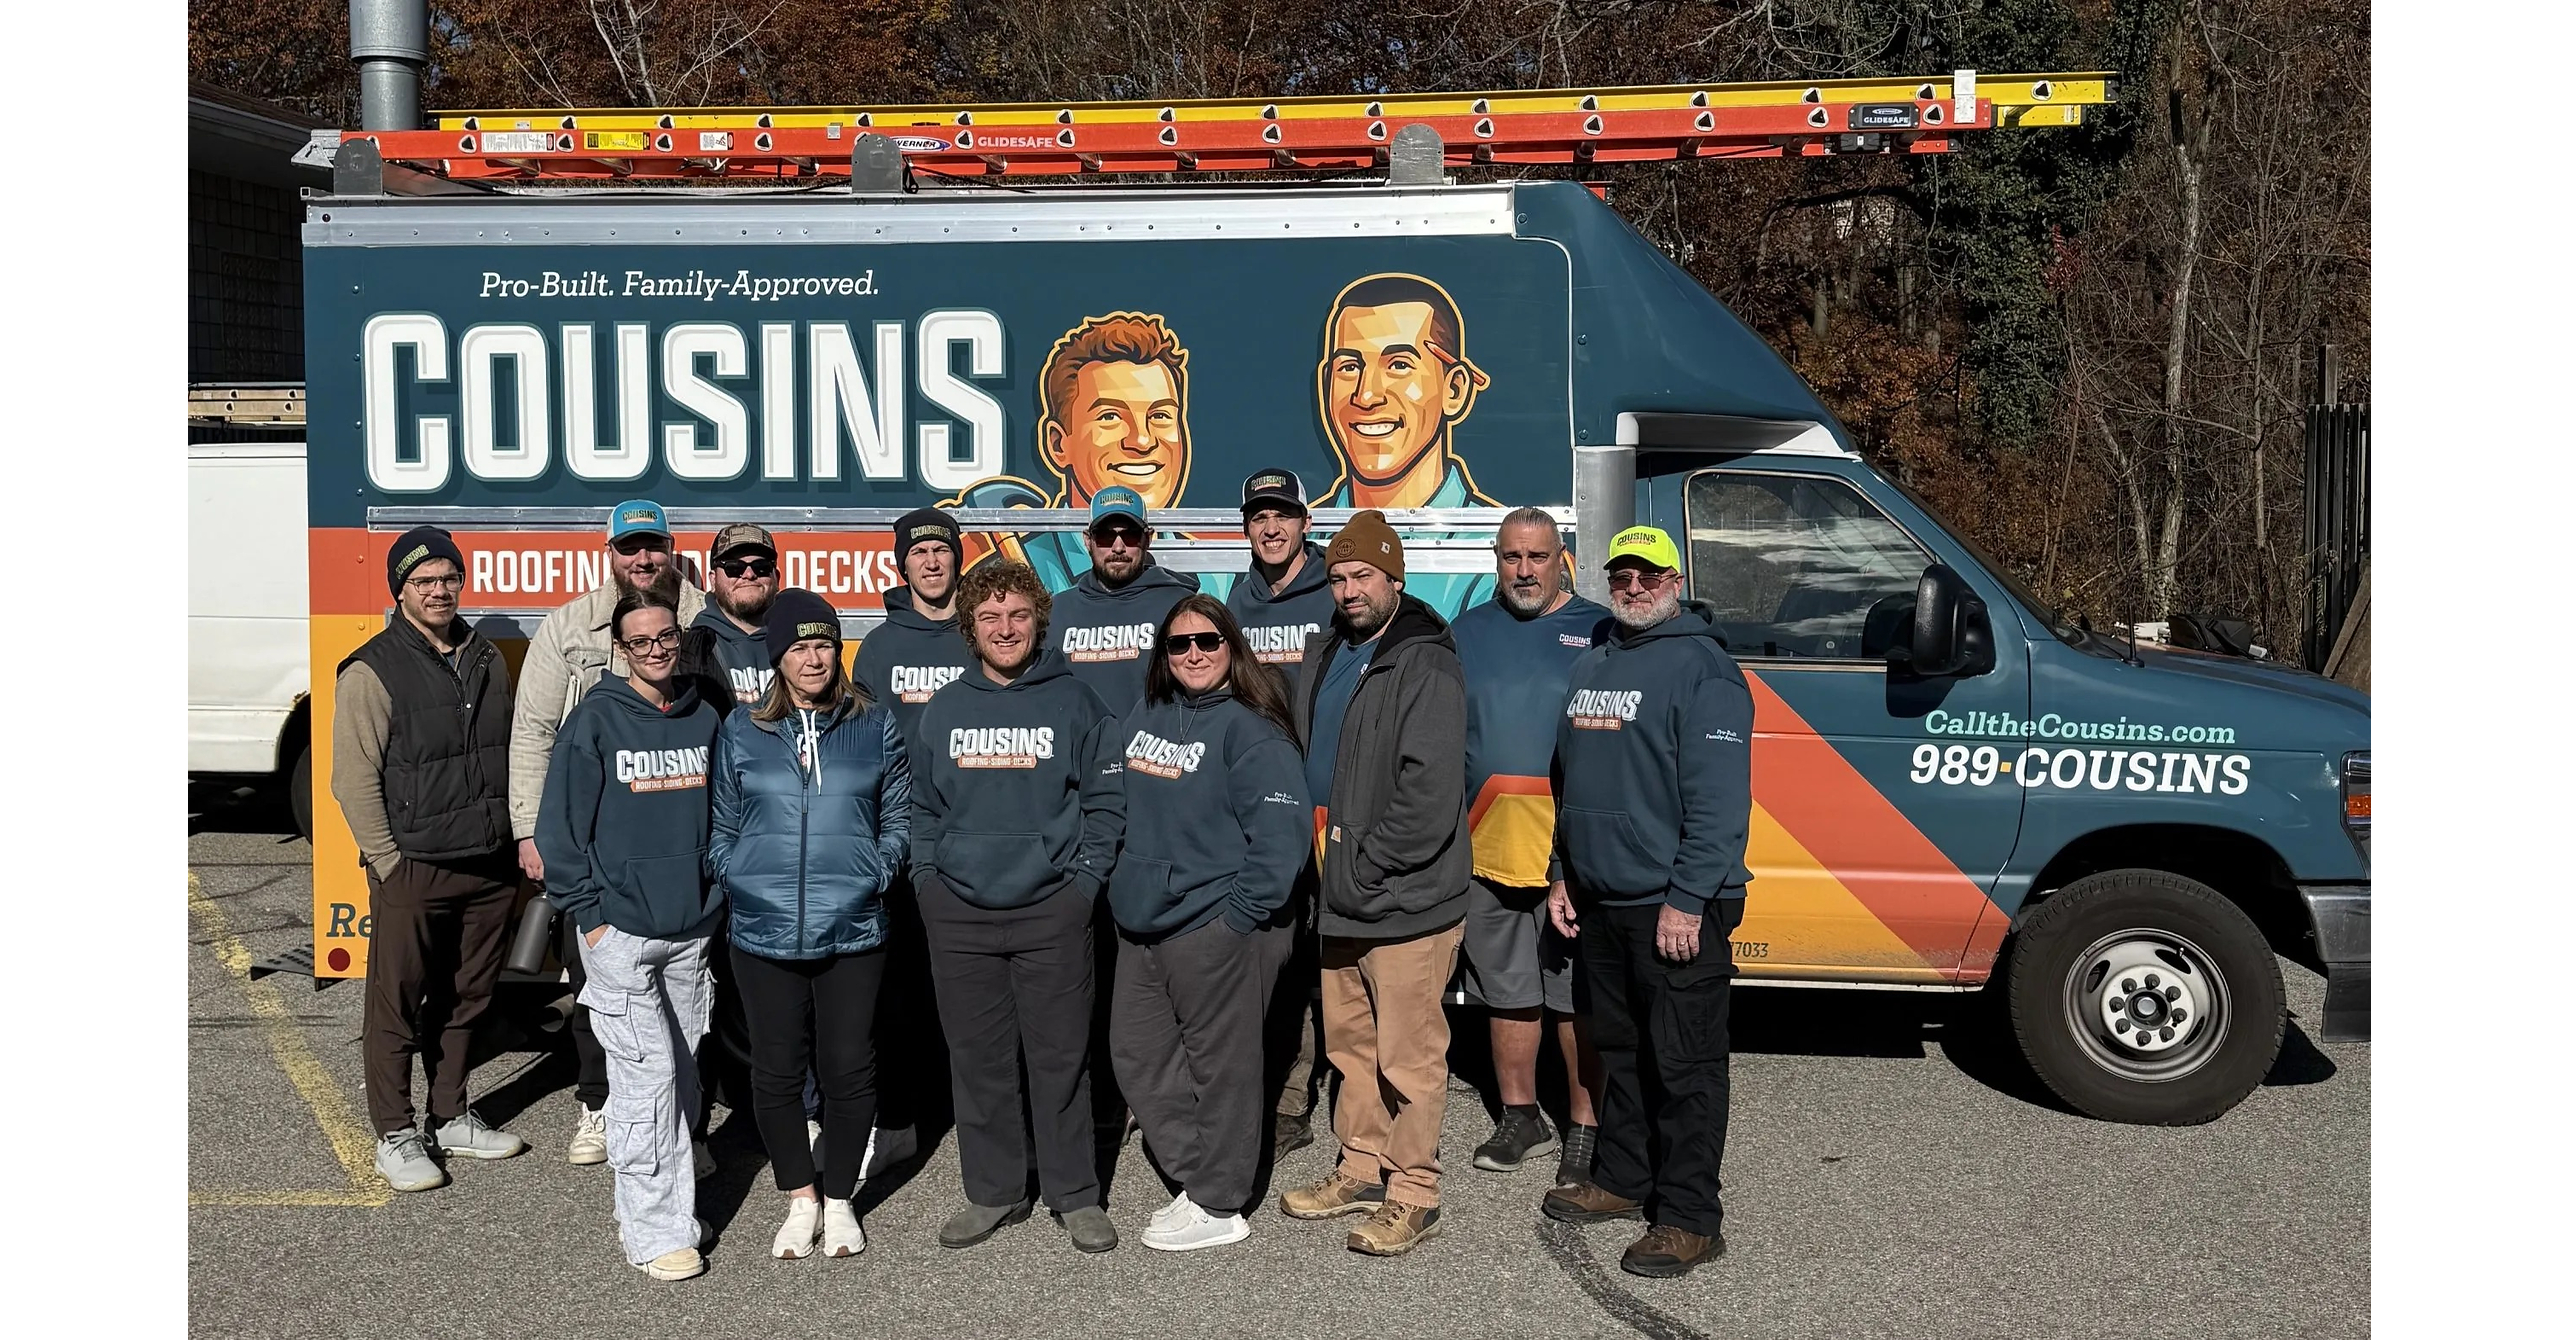
Cousins Roofing, Siding & Decks said it is on pace to generate $20 million-$25 million of 2026 revenue, supported by a workforce of 41 W-2 employees and roughly 1,000 annual exterior-remodeling projects. The Western Pennsylvania contractor has expanded from decking into roofing, siding and outdoor-living services, with offices serving Butler, Washington, Greensburg and Beaver. Management plans to invest further in operations, workforce development and regional coverage while maintaining service quality.
Analysis
This is not a direct catalyst for either listed public security; the relevant read-through is local contractor capacity and lead-generation economics. A scaled installer with a multi-category offering can consolidate homeowner spend and reduce reliance on fragmented subcontractors, modestly improving demand visibility for premium exterior-material vendors such as James Hardie (JHX). At roughly 1,000 annual jobs, however, the implied material volume is immaterial to JHX's consolidated revenue and should not affect estimates.
The more investable second-order signal is competitive intensity in regional home-improvement customer acquisition. Larger operators can bid more effectively on local-search terms, increasing cost-per-lead for smaller contractors and making Google Search monetization resilient even if housing turnover remains subdued. That said, a single privately held contractor's expansion is insufficient evidence of a broader advertising upcycle; track Alphabet's local-services/search commentary and contractor marketing spend in upcoming channel checks.
Over 6-18 months, repair-and-remodel demand is likely to remain more resilient than new construction because aging housing stock, storm repair and deferred maintenance support replacement activity. JHX benefits if contractors continue shifting homeowners toward higher-ticket fiber-cement siding rather than vinyl, but affordability pressure and elevated financing costs could push mix toward repair or lower-cost alternatives. The thesis is falsified by sustained deterioration in remodeling permits, contractor backlogs, or JHX residential revenue/volume guidance rather than by this announcement.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.32
Ticker Sentiment
Key Decisions for Investors
- No standalone trade on this release: the disclosed operator is private and the implied revenue opportunity is too small to alter JHX or GOOG consensus estimates.
- Maintain JHX as a 6-18 month remodeling-recovery watch: initiate only following evidence of stabilizing repair/remodel volumes and management confirmation of residential volume growth; use a 10-12% downside stop or exit on a material cut to North America residential guidance.
- Monitor GOOG local-search monetization into the next earnings print: a broad-based increase in home-services advertiser demand would support Search revenue durability, but treat this as confirming channel evidence rather than a catalyst to add exposure.
- For housing exposure, prefer a selective long JHX versus short a broad housing-sensitive proxy only if remodel activity improves while new-construction indicators remain weak; the pair isolates repair/remodel resilience, with invalidation if mortgage-rate declines revive new-build demand materially.
More News
- Exclusive-Anthropic’s IPO pitch embraces AI’s promise and peril
- Palo Alto Networks’ Nikesh Arora is building a defense against the dark side of AI
- AI market needs to make $6 trillion a year by 2031 to fund its infrastructure habit
- Bernstein Names Top Networking Stocks Led by Celestica
- Wall Street may be sleeping on this networking stock tied to Google and OpenAI
- Reddit is killing RSS feeds and ending public API access because of AI bots