
TECNO Will Bring Next-Gen Bezelless Concept Phone and 360° Hinge MEGABOOK T15 360 Pro to IFA ShowStoppers 2026
Source: PR Newswire
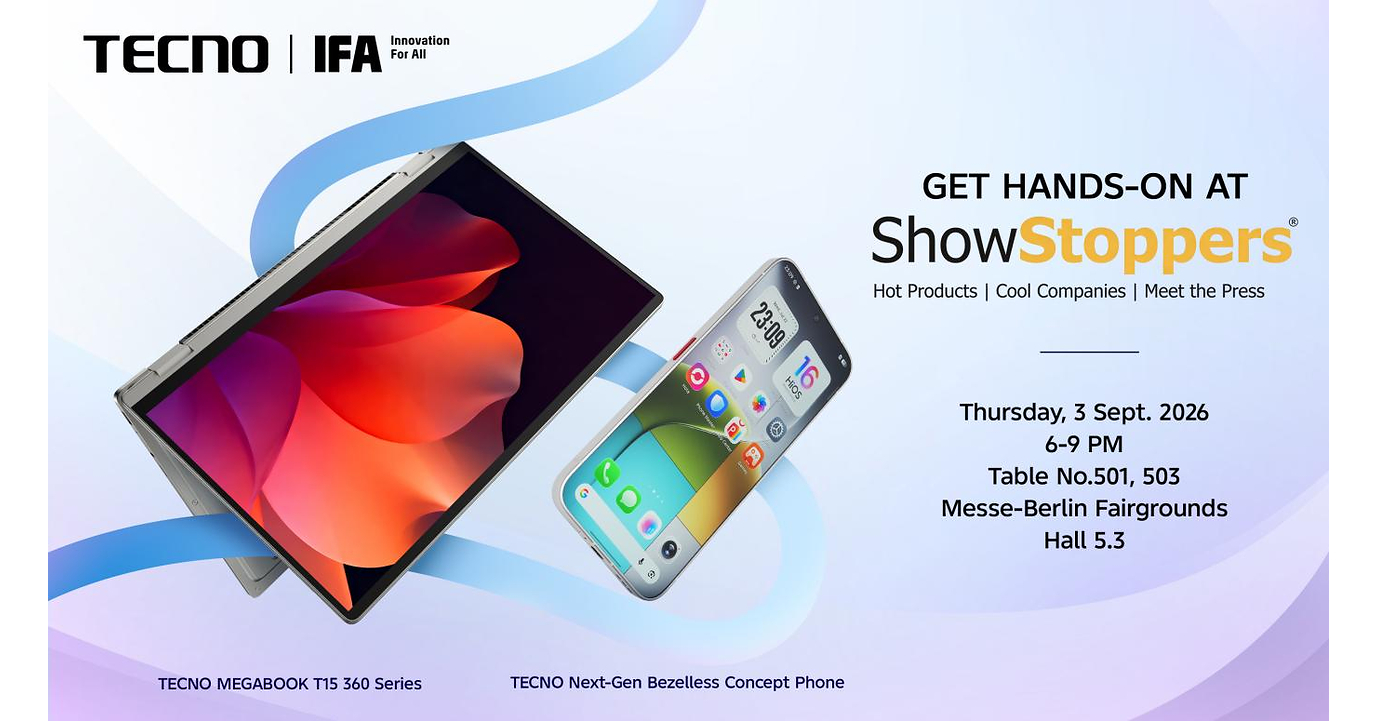
TECNO announced its lineup for IFA ShowStoppers 2026 in Berlin, highlighting a Next-Gen “true 0mm” bezelless smartphone concept and the MEGABOOK T15 360 Pro laptop with a 360° hinge and 10-point touchscreen. The company also plans new MEGABOOK models (K15S WCL and T17 Ultra), plus Tonino Lamborghini-branded devices including the POVA 8 PRO 5G Limited Edition (launching Sept. 4) and an AI tablet in Q4. Additional consumer releases include CAMON Slim 5G/CAMON Slim, MEGAPAD SE 2, Watch 4, and Buds 5, with no financial figures or guidance provided.
Analysis
This reads more like brand-positioning than a measurable demand inflection, so the near-term market impact should be muted. The only investable angle is the Intel platform mention: if tier-2 and emerging-market OEMs are indeed standardizing on Core Ultra/NPU parts, that supports the thesis that Intel can defend client share below the premium Windows tier, but it also implies heavier price competition to win sockets. That mix is good for unit relevance, not necessarily for gross margin, so any positive read-through to INTC should be limited unless channel checks show attach rates and ASPs holding.
Second-order, the bigger winner is the broader Windows AI-PC ecosystem if low-end and midrange devices start advertising NPU features as table stakes; that helps software and peripheral attachment more than it helps any one chip supplier. The potential losers are ARM-based notebook alternatives and low-cost x86 rivals if Intel uses bundled platform pricing to lock in OEMs, but that would take quarters to show up in shipment data. In phones, this is mostly an incremental design/marketing cycle; without carrier or subsidy validation, there is no reason to model meaningful share shifts.
The contrarian view is that investors may be overestimating the signal value of a showcase event and underestimating how little it says about sell-through. The real falsifier for an INTC-positive read is if the next two PC earnings cycles show no improvement in client revenue mix, ASPs, or inventory normalization. On the flip side, if OEM commentary starts referencing NPU-enabled sub-$700 systems as a volume category, the thesis becomes more durable over 6-18 months.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.08
Ticker Sentiment
Key Decisions for Investors
- Do not chase INTC on this headline alone; treat it as a watch item and require confirmation from OEM shipment/channel data before adding exposure. Falsifier: no client-revenue mix improvement or ASP stabilization in the next two earnings prints.
- If already long INTC, consider holding rather than adding; the best-case scenario here is share defense, not obvious margin expansion. Use a tight stop if client gross margin guidance rolls over on any pricing commentary.
- Set an alert on the broader AI-PC basket (INTC, HPQ, DELL, XRX as a value-PC proxy) for evidence that NPU-enabled systems are moving into the sub-premium tier; if confirmed, a relative long INTC vs. a hardware basket short could work over 1-3 months.
- Avoid any short in INTC based on this release; the risk/reward is poor because the event can support sentiment without changing fundamentals. Reassess only if channel checks indicate the OEM is buying on aggressive promotional pricing.
- No action on WWRL from this item; absent a direct revenue linkage or supply-chain role, the signal is too weak for a position.
More News
- We're downgrading this retail stock after a big comeback. Plus, AI names slide again
- Why is VanEck Semiconductor ETF sliding today?
- I watched Nvidia's Jensen Huang work the room in London. He brought big checks — and a blunt message
- Why is BE Semiconductor Industries stock sliding today?
- Benchmarked: Nvidia's RTX Spark notebook delivers serious local AI compute, at a price
- A week with RTX Spark: everything we’ve learned using Nvidia’s new laptops