
Bitmine Immersion Technologies (BMNR) gibt bekannt, dass der ETH-Bestand 5,96 Millionen Token erreicht hat und sich der Gesamtbestand an Kryptowährungen sowie Barmitteln auf 15,8 Milliarden US-Dollar beläuft
Source: PR Newswire
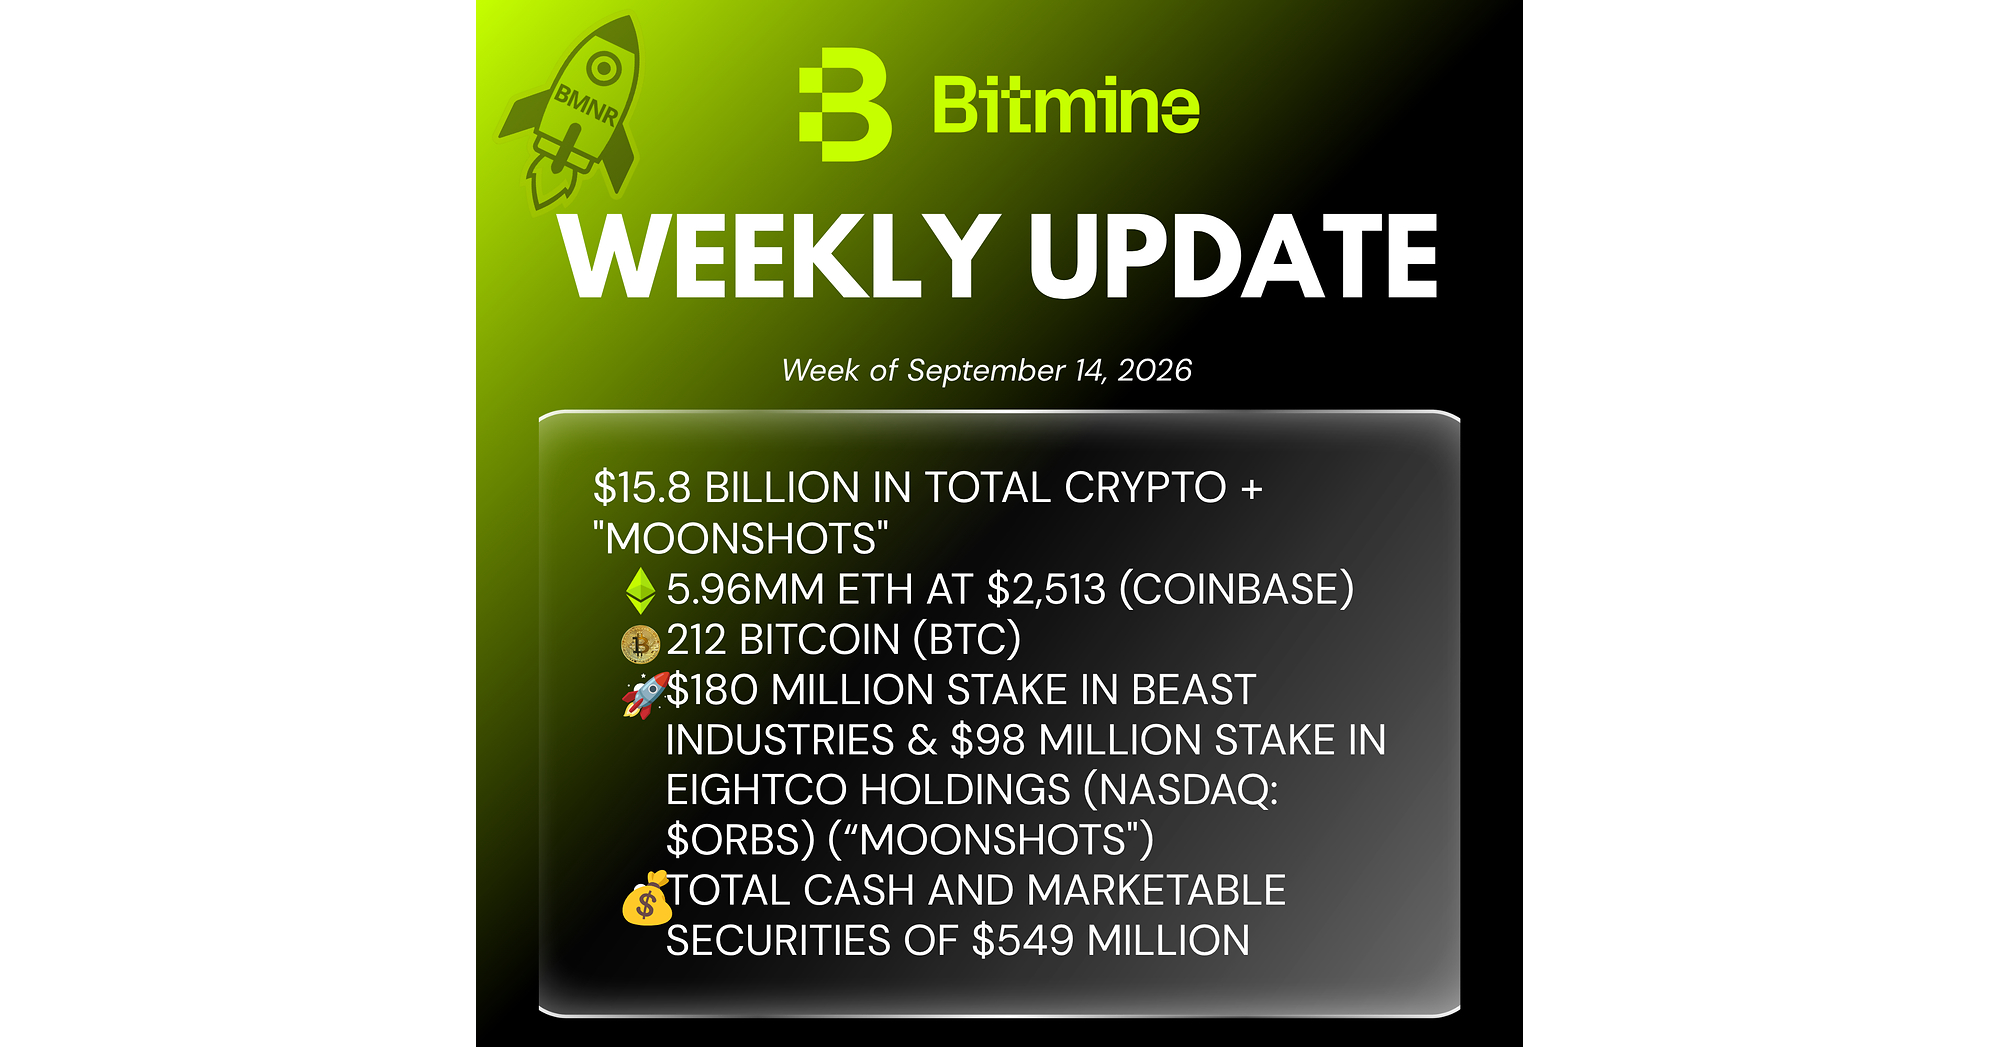
BitMine reported holdings of 5.96 million ETH, worth about $15.0 billion at $2,513 per ETH and representing 4.9% of Ethereum’s 122.0 million-token supply; it bought an additional 27,180 ETH during the prior week. The company has staked 5.07 million ETH (85% of its ETH holdings), with estimated annualized staking revenue of $334 million currently and up to $392 million at full deployment based on a 2.62% annualized seven-day yield. Management expects ETH strength to continue, citing ETH’s 5,866bp Q3 outperformance versus the S&P 500, prospective CLARITY Act legislation, institutional adoption, tokenization, and agentic-AI use cases, though these forecasts remain highly exposed to crypto-price, regulatory, and staking risks.
Analysis
BMNR is evolving into a highly levered ETH closed-end fund with a staking carry overlay, not a diversified infrastructure company. At the stated ETH mark, its liquid crypto position dominates enterprise value; therefore, the relevant valuation is BMNR's premium/discount to NAV and its ability to issue equity above NAV to fund further accumulation. A sustained premium creates a reflexive flywheel—accretive issuance, more ETH purchases, tighter effective float—but a discount breaks it and turns weekly purchases into a financing constraint.
The staking-income headline should not be capitalized like recurring software revenue. Validator yield is partly compensation for protocol, liquidity, custody and slashing risk, while the reported annual run-rate is extrapolated from a short observation window; ETH price appreciation also does not increase ETH-denominated staking rewards. The more material 1-3 month risk is that staking a very large treasury reduces operational liquidity precisely when a risk-off move, redemption pressure, or a need for collateral arises; unbonding/withdrawal mechanics and custody concentration matter more than the quoted yield.
A near-5% treasury stake creates a second-order Ethereum governance and market-structure issue: BMNR becomes systemically exposed to validator concentration scrutiny, while its marginal purchases can amplify upside and downside in ETH liquidity. COIN benefits modestly from higher spot/prime activity and institutional custody demand, but is a cleaner expression of crypto volumes than BMNR. MSTR is the useful relative hedge: it retains BTC beta and financing/reflexivity risk, but lacks the staking-carry narrative, making ETH/BTC the key factor rather than broad crypto direction.
Consensus is likely extrapolating regulatory and tokenization narratives before measurable fee capture exists. A favorable policy event may lift ETH initially, but it does not establish that Ethereum captures tokenization economics rather than L2s, permissioned ledgers, or stablecoin issuers; watch on-chain fee growth, stablecoin settlement share, and institutional staking inflows rather than conference-driven rhetoric. Thesis fails if BMNR's NAV premium compresses despite ETH strength, staking yield falls below roughly 2%, or disclosed ETH purchases require below-NAV issuance.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.62
Ticker Sentiment
Key Decisions for Investors
- Use BMNR only as a tactical 2-6 week ETH-beta vehicle around the policy catalyst; enter only if its premium to independently calculated NAV is below 10-15%. Target 20-30% upside on ETH continuation, but exit if BMNR trades at a >25% NAV premium or ETH breaks its prior monthly support—premium compression can overwhelm spot gains.
- Prefer a 1-3 month relative trade: long ETH exposure (spot/regulated ETF where permitted) and short MSTR in beta-neutral notional terms if ETH/BTC remains above its 20-day moving average. This isolates the anticipated ETH-specific rotation; stop if ETH/BTC closes back below the pre-breakout range for five sessions.
- Do not underwrite the stated staking run-rate until the next filing reconciles gross rewards, validator/custody costs, slashing reserves, withdrawal liquidity, and the percentage staked through affiliated MAVAN versus third parties. Treat a gap between reported ETH holdings and verifiable on-chain validator balances as a risk alert.
- For cleaner listed exposure to a crypto risk-on tape, favor COIN over BMNR after a sharp BMNR premium expansion: COIN captures volume, custody and institutional-flow upside with less single-asset treasury convexity. Reassess if crypto trading volumes fail to rise over the following month despite higher ETH prices.
- Avoid ORBS as a proxy for AI or private-company optionality; its valuation sensitivity is likely dominated by liquidity, disclosure quality, and BMNR's mark rather than a verifiable operating linkage. Any position requires confirmation of the investment terms and current mark methodology.
More News
- US Senate crypto bill collapses in blow to industry
- Wall St futures slip as rising oil, Treasury yields compound AI anxiety
- Crypto stocks fall as Senate blocks landmark digital asset bill
- Strategy (MSTR) stock falls 5% as Clarity Act stalls
- AI coding agent startup Factory triples valuation to $5 billion in latest funding round
- Factory raises $200 million, valuation triples to $5 billion
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Choosing an AI Copilot for Equity Research
- Weekly Update: Advanced Search Filters, Redesigned Ticker Dashboard, and Improved Search Experience