
VinFast Reports Unaudited Second Quarter 2026 Financial Results
Source: PR Newswire
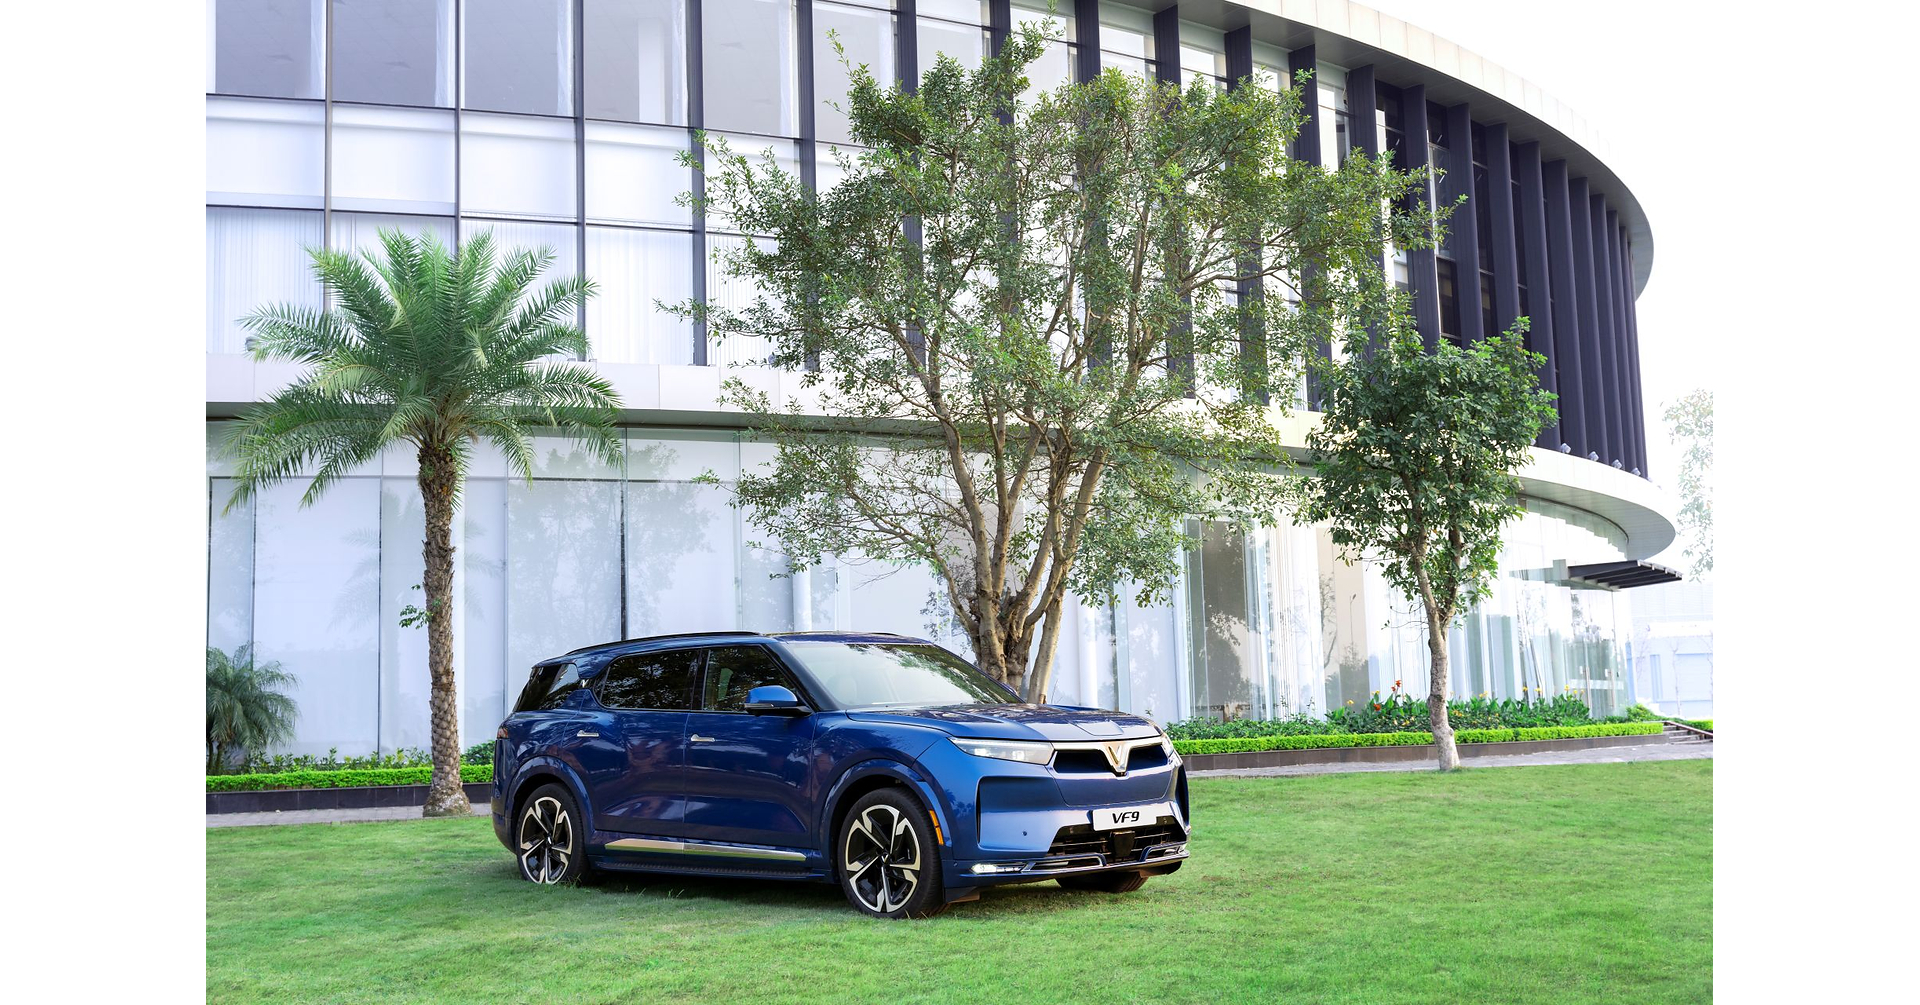
VinFast reported Q2 2026 revenue of VND30,340.9 billion (US$1,203.7 million), up 32.9% quarter over quarter and 85.5% year over year; EV deliveries rose 20% sequentially to 70,085, while e-scooter and e-bike deliveries doubled to 286,039. The company cited higher sales volumes, Vietnam market growth and overseas contributions, and said it is pursuing a more capital-efficient manufacturing model while expanding internationally. VinFast held about 38% of Vietnam’s automotive market and reported 474 global showrooms as of June 30; its planned 200-vehicle Level 4 robotaxi pilot in late 2027 remains subject to regulatory approvals.
Analysis
The key underwriting question is whether VinFast can convert volume into cash generation—not whether it can keep adding units. Vietnam remains the earnings and execution fulcrum: the reported international share of deliveries is still modest, so expansion claims have not yet demonstrated geographic diversification. Rapid scooter growth may broaden the ecosystem and retail reach, but without segment revenue, gross-margin and working-capital disclosure, unit growth cannot be treated as an earnings proxy.
The claimed shift to more capital-efficient manufacturing and a complementary earnings stream could improve the equity story, but neither is independently quantified here. The earnings call is the immediate catalyst: look for consolidated and vehicle gross margin, operating cash burn, capex, funding sources, and clarity on what the added earnings stream is. In the next 1–3 months, evidence that overseas dealer-led growth converts into registrations and repeatable economics matters more than showroom counts or cancellable reservations. Over 6–18 months, execution in India, Indonesia and the Philippines could reduce Vietnam concentration; factory utilization, service coverage and any pricing needed to win share will determine whether that growth is value-accretive.
Contrarian angle: strong delivery and market-share headlines may be masking a financing and margin problem, while the market may also underappreciate the option value of a large two-wheeler base if it supports customer acquisition. Neither side is established by the release. Competitive pressure from established EV makers and local manufacturers can force price investment. This is a high-variance event, not a clean fundamental long on the supplied data.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.45
Ticker Sentiment
Key Decisions for Investors
- Avoid chasing VFS before management’s October 19 call; the release does not provide the margin, cash-flow or funding data needed to validate the growth-to-profitability thesis.
- Treat a defined-risk VFS call spread as a conditional post-call idea only if management quantifies improving vehicle margins and lower cash burn without relying on one-off or non-core earnings. No trade if those metrics remain undisclosed.
- Set a 1–3 month watch item for overseas registrations, dealer sell-through and service-network expansion—not reservations or showroom counts alone. Weak conversion or renewed price discounting would falsify the diversification thesis.
- Reassess any bullish position if guidance or reported results show worsening gross margin, rising operating cash burn or increased funding needs; these would outweigh delivery growth and raise dilution risk.
More News
- Vingroup’s Green SM brings 500 VinFast EV taxis to Los Angeles
- VinFast Auto: Impressive Sales, Terrible Economics
- BlackRock, GIC among investors chasing Indian telecom major Jio's IPO as anchor bids top $26 billion
- Nscale, Anthropic Eye $45 Billion Cloud Deal as AI Trade Rebounds
- Gartner analyst behind tech rout: AI returns are not yet large enough to justify neocloud build-out
- Alibaba Backs Chinese Robovan Maker in $400 Million Fundraising
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: New Reporting Features, UI Improvements, and Chat Optimizations
- Selecting an AI Research Platform for Institutional Investors