
GBI Bio Appoints Jesse McCool, Ph.D., as Chief Executive Officer
Source: PR Newswire
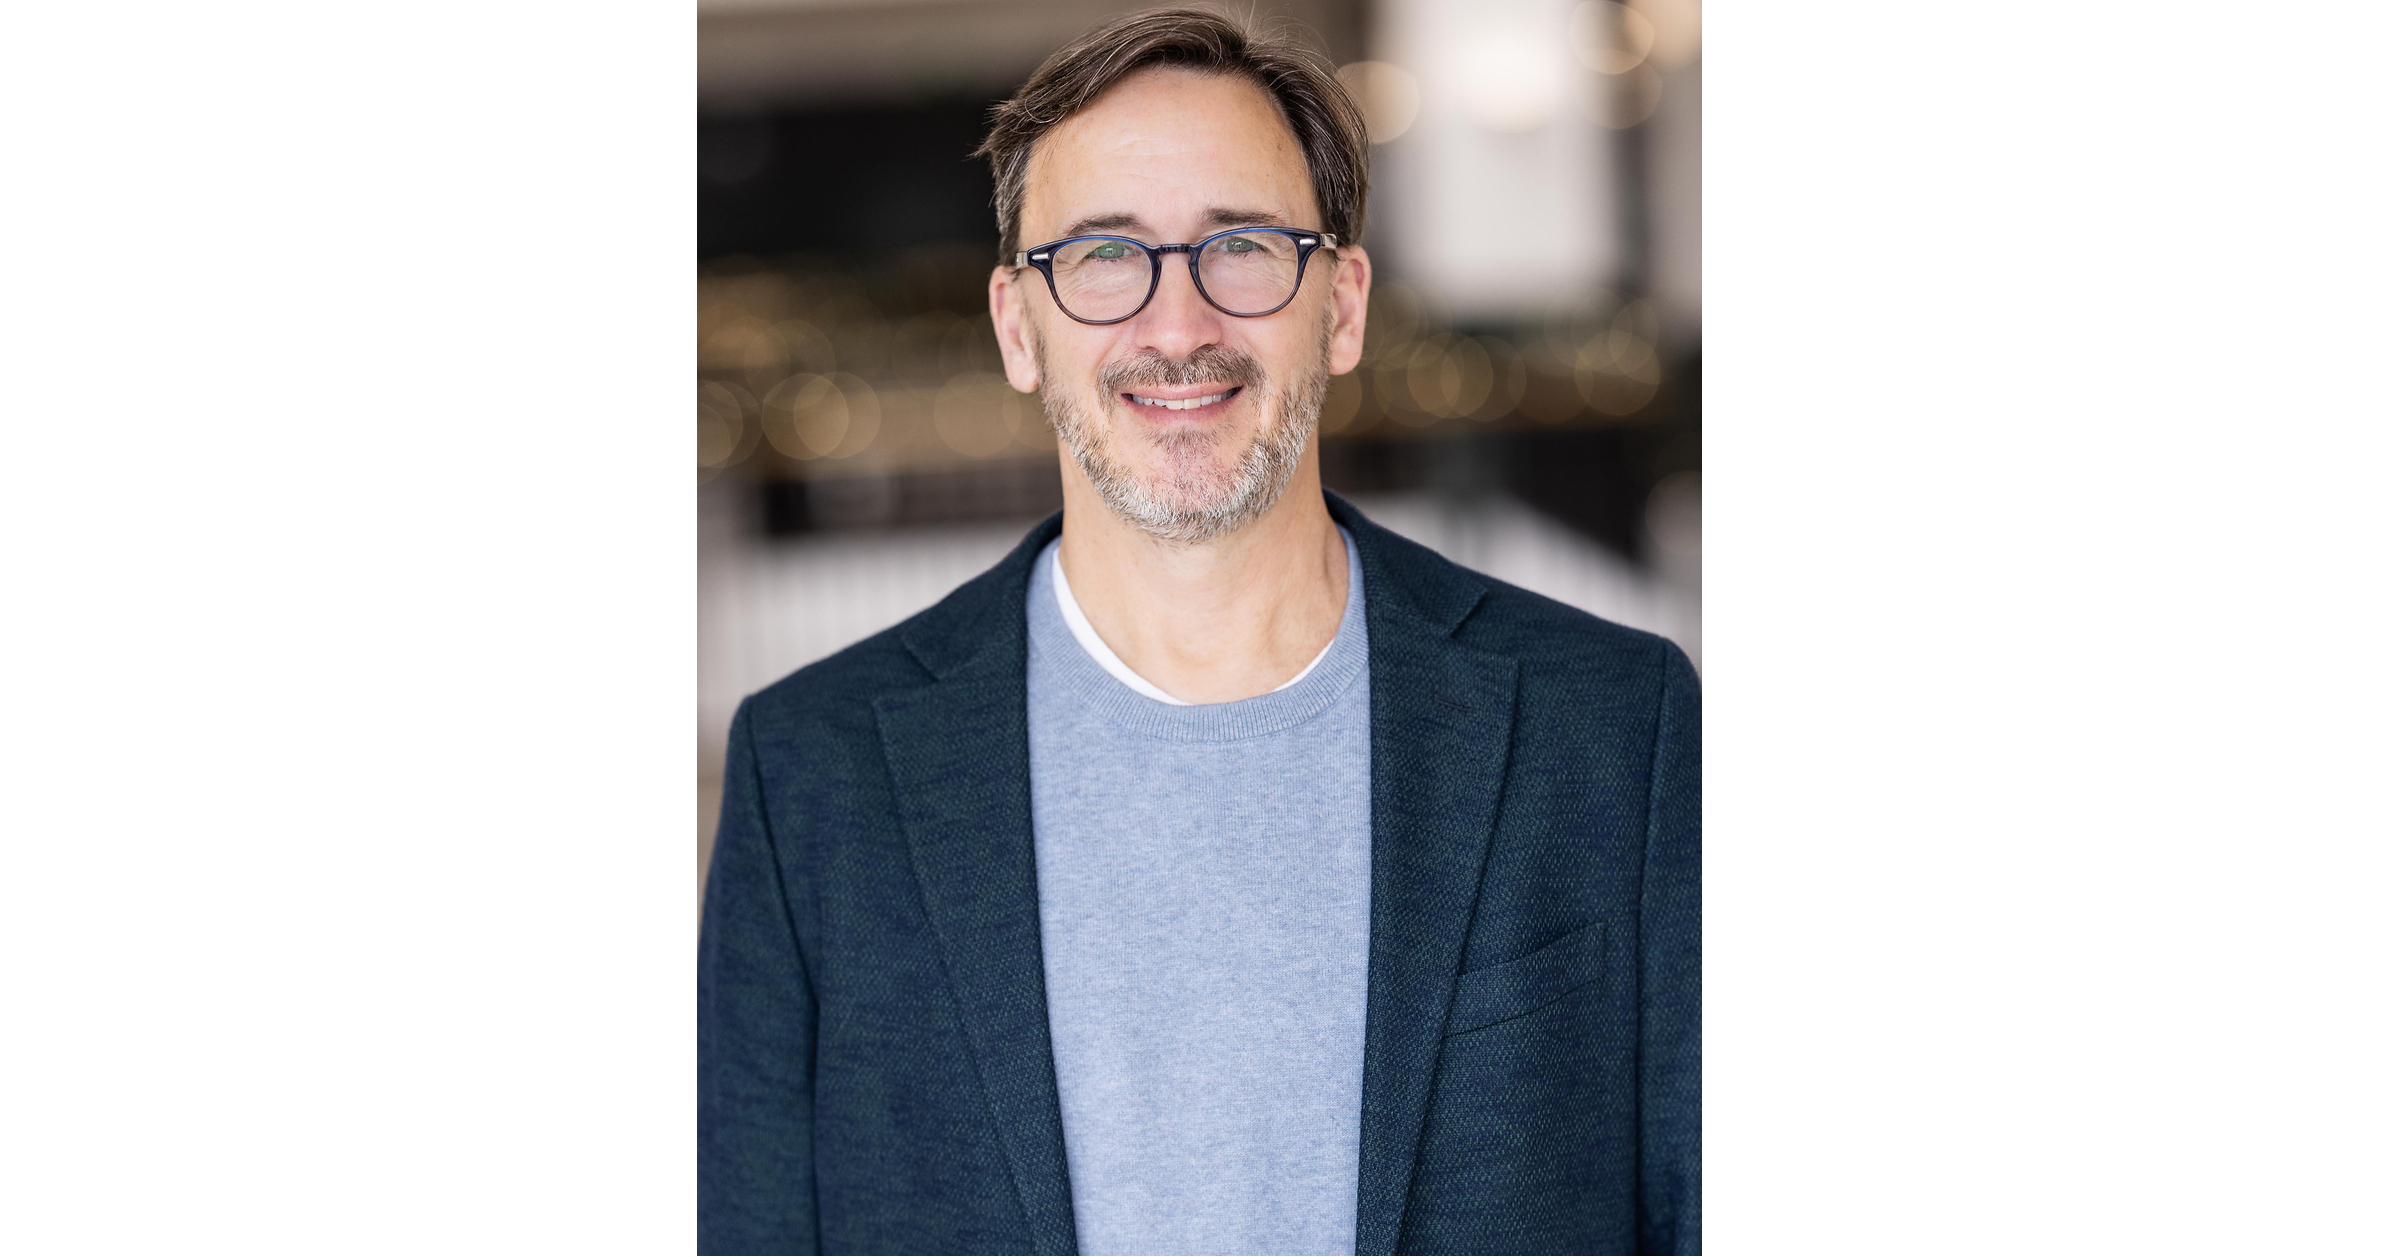
GBI Biomanufacturing appointed Jesse McCool, Ph.D., as CEO after he served as president and COO since late 2025. The company is advancing toward commercial-scale biologics manufacturing while expanding early-stage capabilities, supported by its SmartScale GMP platform for rapid small-scale clinical manufacturing. McCool brings more than 25 years of biopharma manufacturing experience, including leadership roles at Lonza, Bionova Scientific and Wheeler Bio.
Analysis
This is not a fundamental catalyst for LONN: the executive's prior industry experience creates only a weak competitive read-through, while GBI is private and too small for its expansion plans to alter global biologics capacity utilization or pricing. The more relevant implication is that specialized, sub-commercial CDMOs are competing harder for the same emerging-biotech clients that feed larger players' development pipelines. That can modestly pressure early-development service pricing and client retention, but it is unlikely to affect Lonza's earnings mix unless capacity additions become funded, validated, and commercially utilized.
The second-order signal is that customers increasingly value a continuum from early CMC work through commercial supply, which favors integrated platforms but raises execution risk for smaller operators attempting to span both. For LONN, the structural question is whether its premium positioning and global regulatory track record preserve pricing versus smaller flexible entrants; this will show up in biologics order intake, development-to-commercial conversion, and margin guidance over the next 2-6 quarters. Consensus should not treat management rhetoric around "commercial scale" as incremental supply: qualification, regulatory inspection history, customer tech transfer, and utilization typically require years rather than quarters.
Near term, there is no investable public-equity catalyst from this announcement. A meaningful negative read-through for LONN would require evidence of broad US small-scale biologics capacity oversupply, falling development-stage project pricing, or a deterioration in its book-to-bill and commercial manufacturing demand. Conversely, sustained demand for complex modalities such as ADCs and bispecifics would likely favor scaled incumbents with validated quality systems over newer entrants.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.32
Key Decisions for Investors
- No directional LONN trade on this announcement; maintain existing positioning and treat it as a competitive-intelligence datapoint rather than an earnings catalyst.
- Monitor LONN's next results for biologics order intake, capacity utilization, pricing commentary, and development-to-commercial conversion. Consider reducing any LONN overweight only if management signals pricing concessions or a material decline in late-stage pipeline conversion.
- For a 6-18 month relative-value watchlist, favor scaled complex-biologics manufacturing exposure through LONN versus smaller unlisted CDMO expansion stories; the thesis is falsified if LONN's biologics margins compress despite stable utilization, indicating competitive pricing rather than temporary mix effects.
More News
- Here’s the ‘core economic flaw’ in the AI bull case as stock and bond trades unravel, according to a top economist
- Biotech stocks are surging. How investors can play the new drug innovation boom
- Nvidia's role as AI financier faces first big test as neoclouds take market hit
- What next for France as riots rattle markets? Three questions facing investors ahead of more protests
- Ukraine says Starlink and Starshield high speed restrictions have been lifted
- Goldman says these top tech stocks have plenty of upside ahead of earnings