
Veridian Credit Union ranked No. 1 in the U.S. for member value
Source: PR Newswire
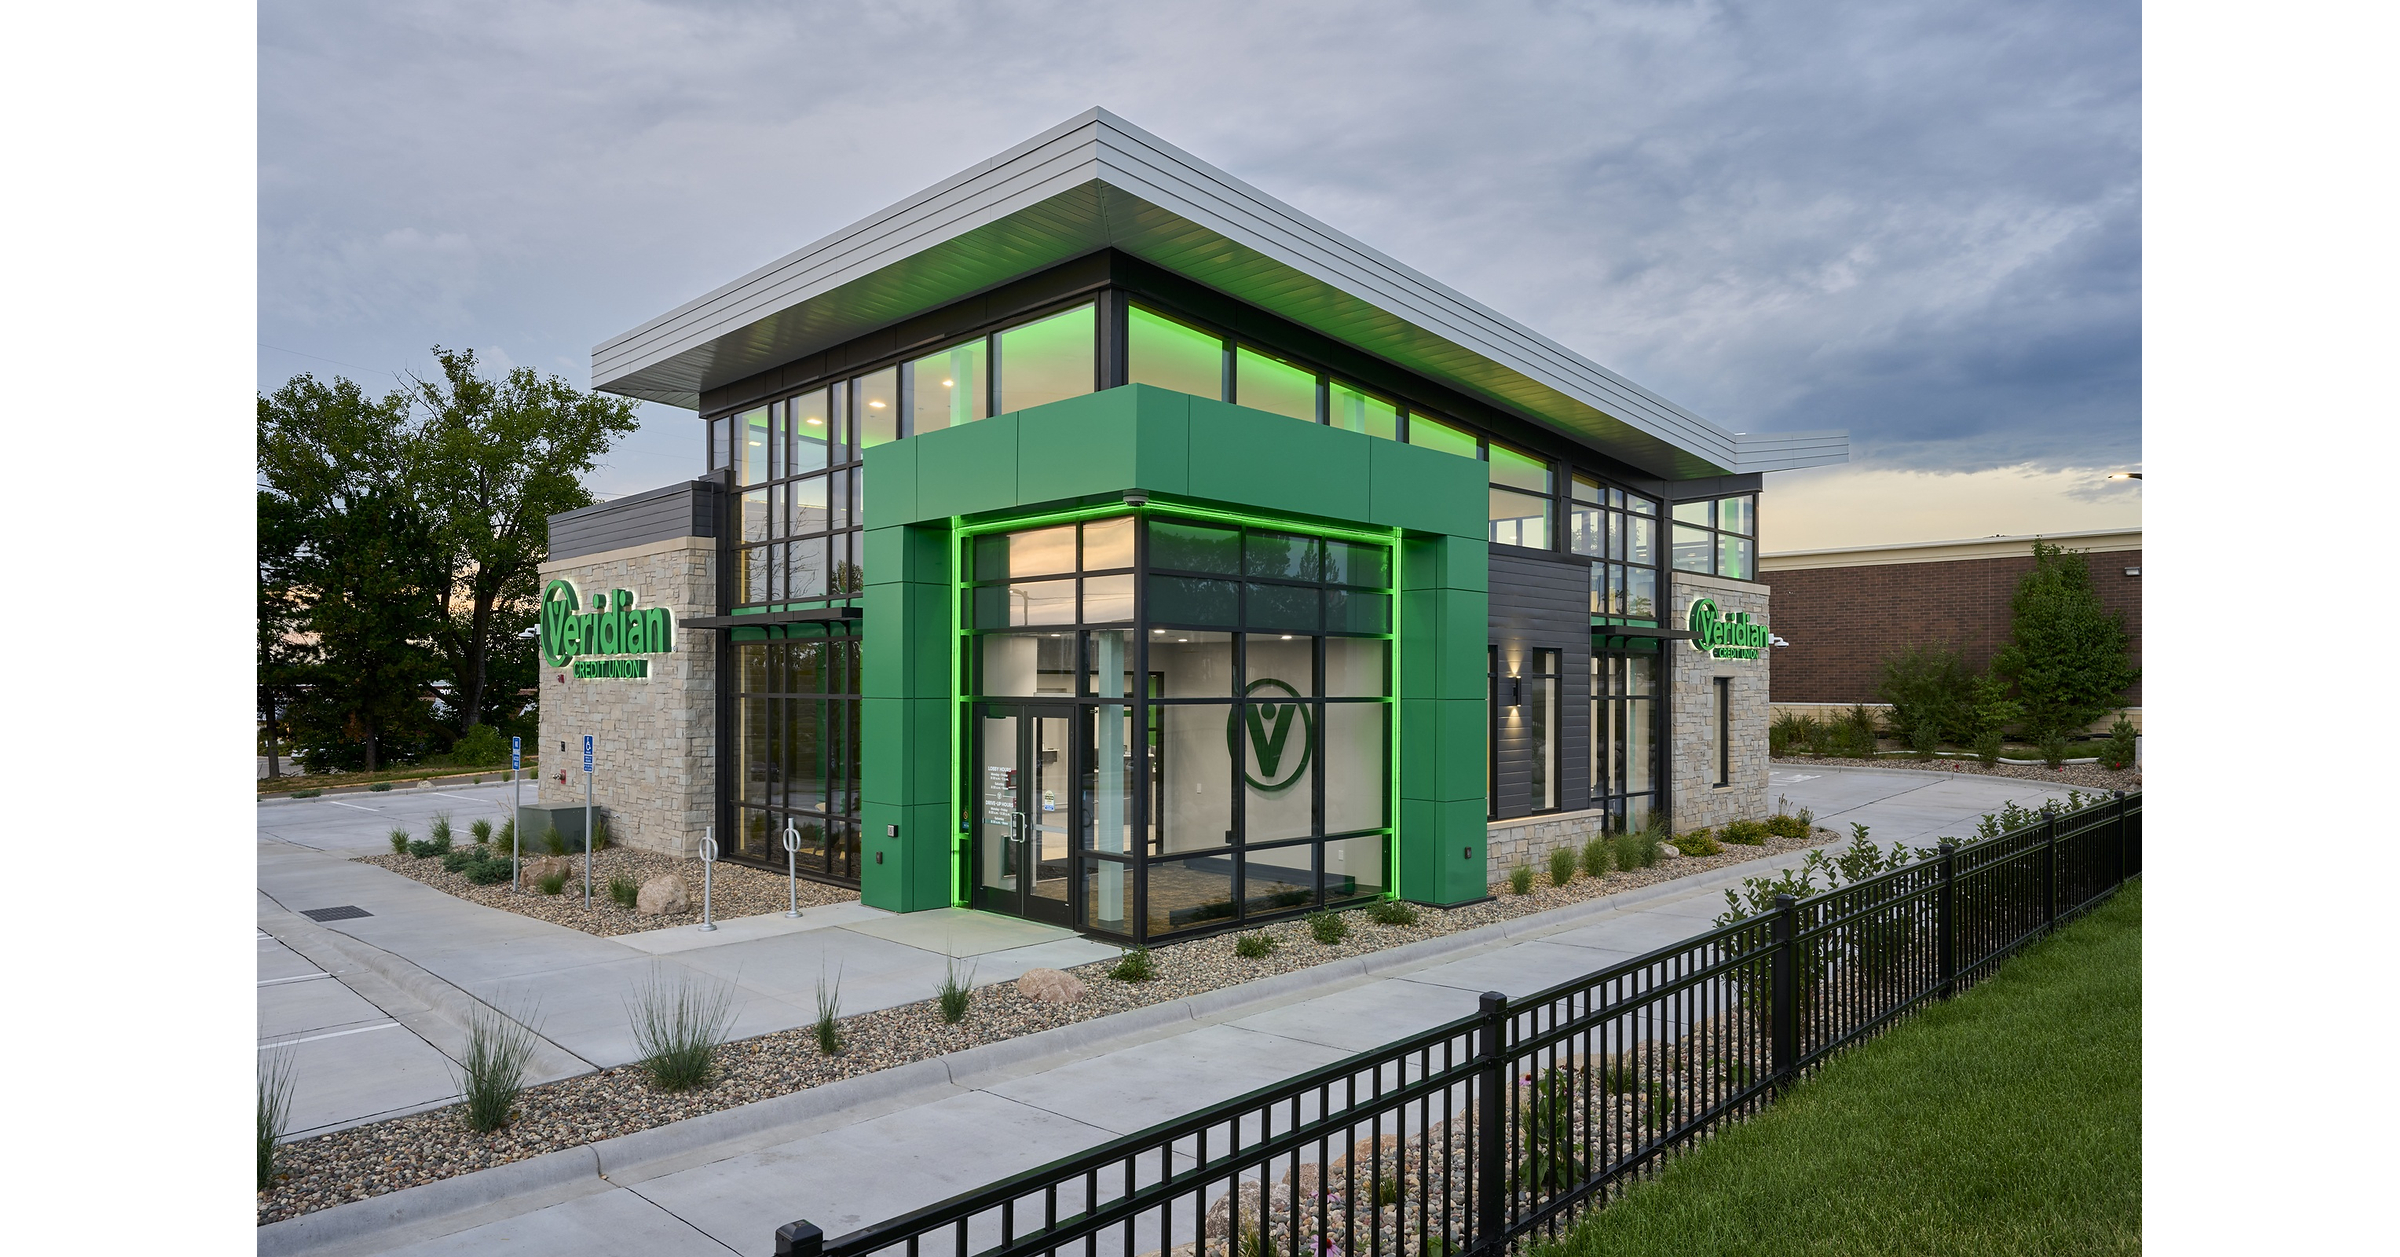
Veridian Credit Union ranked No. 1 nationally in Callahan & Associates' Return of the Member Index for Q2 2026, based on regulatory call-report measures of saver value, borrower value and member service usage. The credit union has ranked in the top 10 since Q4 2022 and is the only institution based in Iowa, Nebraska or Minnesota to reach No. 1 in the index during the past five years. The recognition supports Veridian's member-value positioning but is unlikely to have material market impact.
Analysis
No directly investable issuer is implicated, and the release is unlikely to move public regional-bank or fintech valuations. The ranking is primarily a member-economics signal: sustaining superior deposit pricing, loan pricing, and service utilization generally implies lower retained spread than a profit-maximizing bank, not superior shareholder returns. Treat it as an incremental indication that credit-union competition remains active in Iowa/Nebraska/Minnesota consumer deposits and prime auto/home lending.
The second-order pressure falls on deposit-rich regional banks with meaningful Upper Midwest branch overlap, particularly those relying on retail funding to defend net interest income. Credit unions’ tax-exempt structure and member-return mandate can force banks either to pay up for deposits or accept share loss; the former compresses NIM quickly, while the latter weakens fee cross-sell and loan growth over the next 1-3 quarters. This is more relevant if deposit betas reaccelerate after a rate cut or if consumer loan demand normalizes.
There is no standalone trade on this item. A useful watch is whether local competitors disclose elevated deposit costs, falling noninterest-bearing deposit mix, or below-peer consumer-loan growth in upcoming earnings; those would validate that competitive intensity is becoming financially material rather than merely reputational. The thesis is falsified if bank deposit costs decline faster than asset yields, or if credit-union loan growth slows materially, indicating that the ranking reflects pricing generosity without incremental market-share capture.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Key Decisions for Investors
- No immediate position: classify as low-impact, non-investable industry intelligence rather than a catalyst.
- Monitor Q3/Q4 filings for Upper Midwest regional-bank deposit beta, uninsured-deposit mix, and consumer-loan growth; only consider a relative short versus KRE if a bank shows sequential NIM compression alongside deposit-share pressure.
- Use KRE versus XLF as the liquid sector expression if evidence broadens: long XLF / short KRE over 1-3 months targets regional funding-cost sensitivity, but enter only after confirmation from earnings and set a stop if KRE outperforms XLF by 5% following results.
More News
- Paramount Skydance prices $42 billion debt for Warner Bros deal
- Tencent leases 100,000 chips from Oracle for $7 bln- FT
- RAM supply set to worsen, says Micron, as CEO celebrates ‘much higher’ prices
- Why is Nidec stock plunging today?
- Why is Kioxia stock rallying today?
- Nidec Corp shares slump after auditor declines to sign off on earnings