
Global Schools Group Marks 25th Anniversary with S$100,000 Multi-Organisation Community Support
Source: Newswire
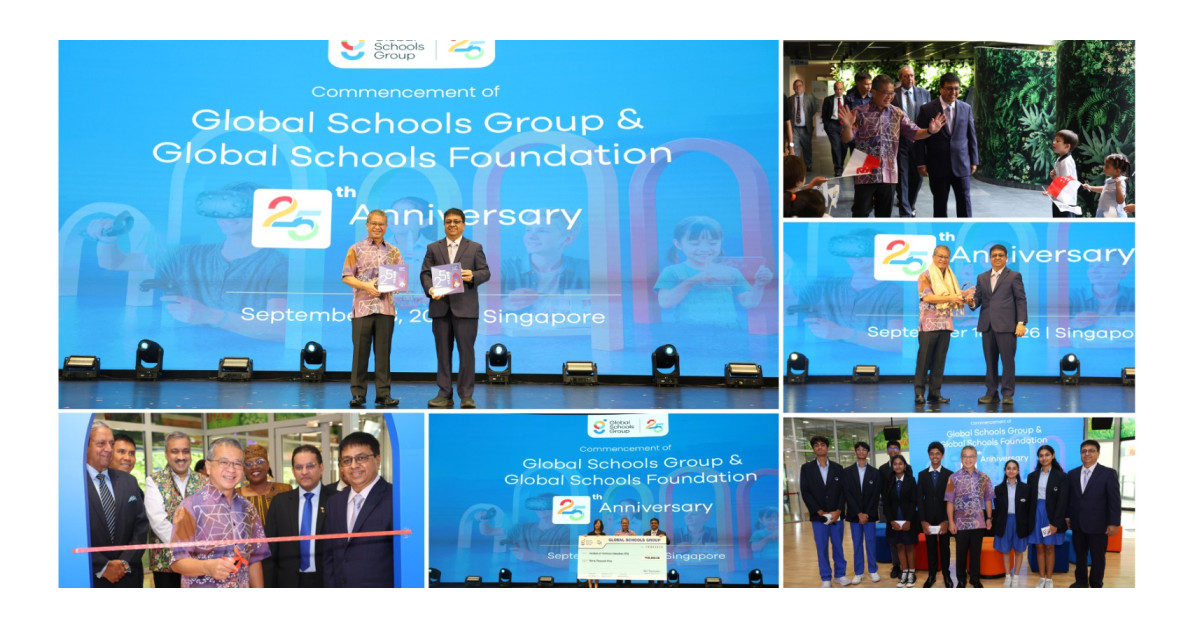
Global Schools Group committed S$100,000 to Singapore community and special-education initiatives as it marked its 25th anniversary, while outlining plans to open 20 international campuses by 2030 across high-growth Asian and Middle Eastern markets. The education network currently operates 64 campuses in 11 countries serving 45,000 students, and highlighted its Deming Prize recognition and more than 650 international awards. The announcement is strategically positive for GSG's expansion profile but is unlikely to have broad public-market impact.
Analysis
This is not a public-markets catalyst: Global Schools Group is privately held, and neither its funding plan, campus economics, acquisition pipeline, nor ownership structure is disclosed. The announced expansion should therefore be treated as a demand signal for international-school capacity rather than evidence of investable earnings growth. Near term, listed exposures are indirect and likely immaterial relative to their broader portfolios.
The more relevant second-order effect is competition for premium expatriate and affluent-local enrollments in Asian and Gulf hubs. Additional supply can raise customer-acquisition costs, teacher compensation, and facility lease costs for private operators; incumbents with owned campuses and established accreditation should be better insulated than lease-heavy greenfield networks. Education-property demand could support selected Singapore, Dubai, and Kuala Lumpur commercial landlords over 6-18 months, but the scale, locations, and financing model are too opaque to quantify.
Consensus should not extrapolate a campus-count target into returns. International-school expansion often front-loads fit-out, licensing, and faculty costs while enrollment ramps over multiple academic years; a weakening expatriate cycle, stricter foreign-school regulation, or higher regional real-estate costs would impair unit economics before revenue maturity. The philanthropic and quality-recognition elements have limited bearing on valuation absent independently verified enrollment, tuition, retention, and EBITDA data.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Key Decisions for Investors
- No direct trade: maintain no position based on this announcement because there is no listed issuer or disclosed financial exposure.
- Create a 1-3 month watchlist for listed education operators with Asia/Middle East exposure, including TAL, EDU and China Education Group (839 HK); only investigate if disclosed campus locations overlap materially with their premium or international-school segments.
- For 6-18 month property follow-through, monitor Singapore and Dubai education-zoning approvals, school-site lease transactions, and expatriate employment data before expressing any landlord view; the missing location and ownership data preclude a recommendation.
- Thesis falsifier for any future competitive-pressure trade: evidence that new campuses are acquired rather than built, or that enrollment demand exceeds incremental capacity, which would reduce the expected margin and occupancy drag on incumbents.
More News
- Chinese biopharma stocks jump as U.S. weighs keeping door open to drug deals
- China slows humanoid robot IPO rush as hype outruns reality
- Qatar Says LNG Damage May Take Years to Repair
- Anthropic Mulls New AI Model Amid Investors' Pre-IPO Worries
- AI Boom Is Making Diversifying Investments Tough for Wall Street
- How India Turned Cricket Into A Billion Dollar Business
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AllMind Discusses Ontario's AI Economy with Minister Stephen Crawford and Supply Ontario CEO James Wallace
- AI Research Tools for SEDAR+, UK and ASX Filings