
Shanghai Electric sichert sich ersten Auftrag für eine Schwerlast-Gasturbine im Ausland für ein 500-MW-Projekt in Malaysia
Source: PR Newswire
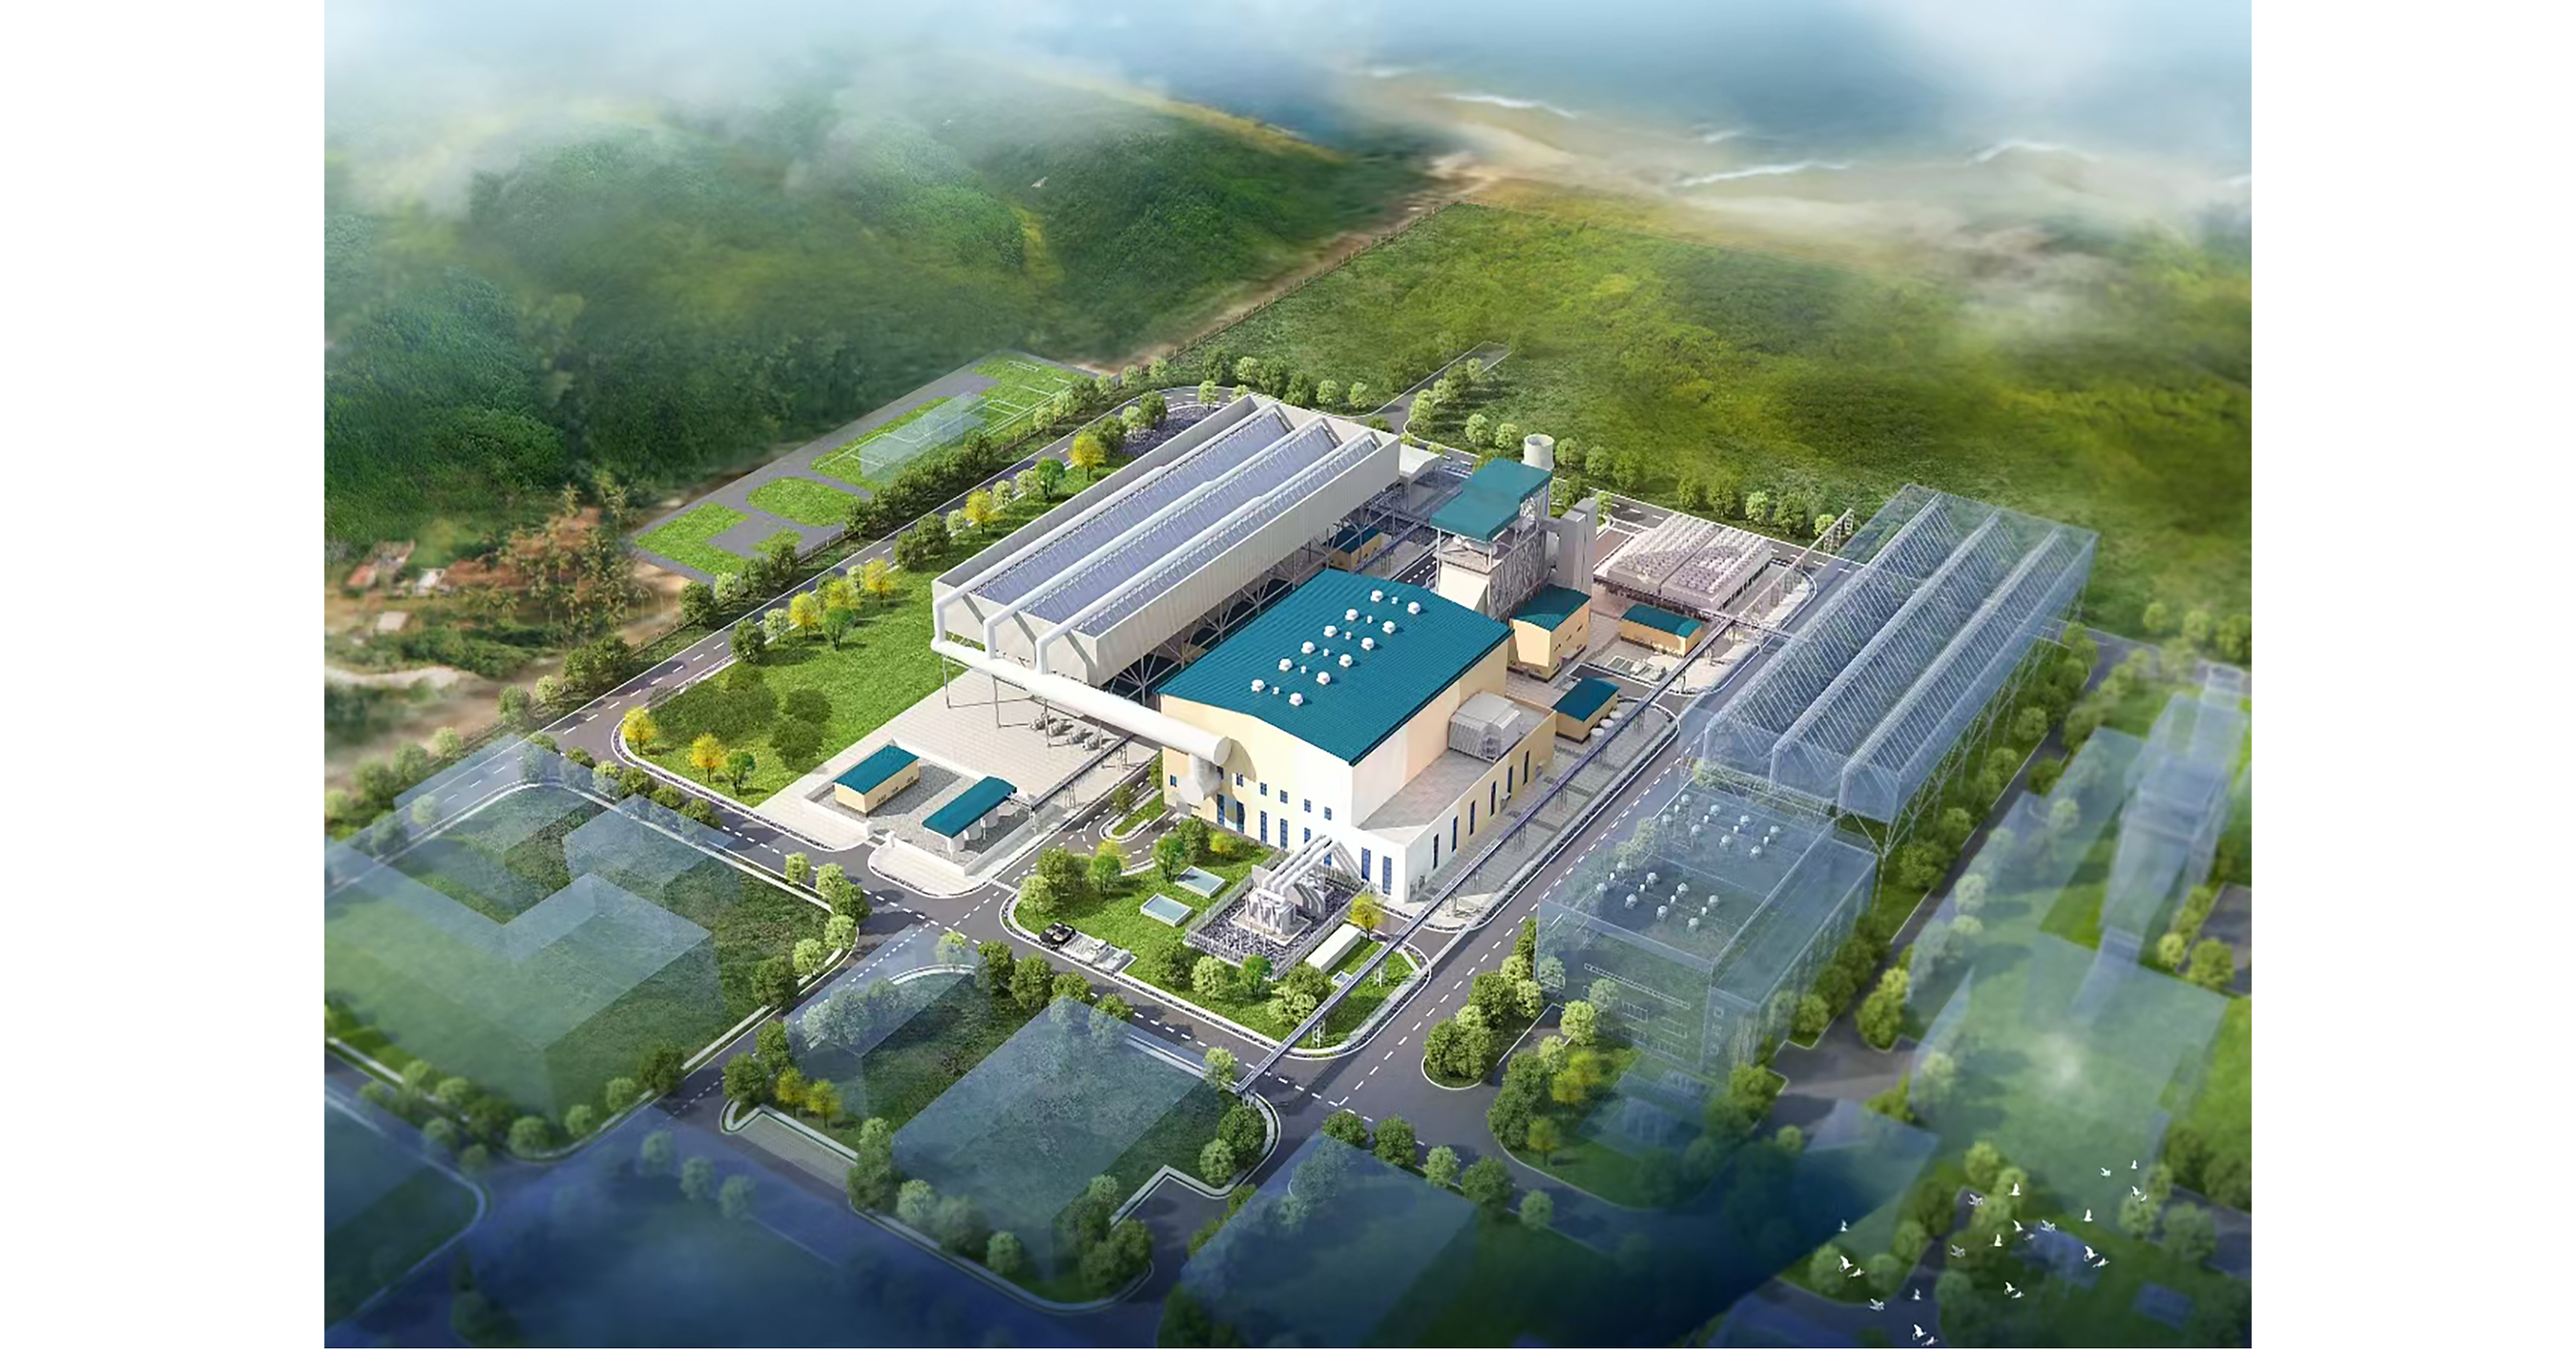
Shanghai Electric secured its first overseas heavy-duty gas-turbine contract, winning Block 3 of Malaysia's 500-MW Sarawak-Samalaju combined-cycle gas turbine project. The company will provide a full EPC turnkey solution and a 25-year long-term service agreement, with all core equipment manufactured in-house. Shanghai Electric has delivered 103 high-performance turbine units totaling more than 21 GW of commissioned capacity, and cited prospective demand from developers in Indonesia, Thailand, the Philippines and Vietnam.
Analysis
The strategic value is less the EPC revenue than whether this reference project converts Shanghai Electric from a China-centric equipment supplier into a credible ASEAN bidder. A successful first operating reference would pressure GE Vernova (GEV), Siemens Energy (ENR) and Mitsubishi Heavy (7011 JP) primarily in price-sensitive combined-cycle tenders, where a vertically integrated Chinese package can trade lower upfront capex for guaranteed service coverage. The likely second-order effect is margin pressure on incumbent OEMs' equipment bids rather than an immediate loss of their higher-margin installed-base service revenues.
The near-term earnings read-through is limited: delivery availability beginning in 2028 pushes meaningful equipment revenue beyond the next two fiscal years, while project execution, financing and grid/interconnection milestones remain material. The 25-year service arrangement could create a valuable recurring-revenue asset, but its economic value depends on independently demonstrated availability, heat-rate performance, spare-parts localization and payment security; these are not established by a contract announcement. A delay, performance shortfall, or warranty reserve would be especially damaging because first-of-kind export projects tend to carry underpriced execution risk.
Consensus may overstate the threat to Western OEMs. GEV and ENR retain bankability, financing relationships, fuel-flexibility credentials and a far larger regional service footprint; ASEAN developers will pay for proven outage performance where power shortages impose high penalties. The underappreciated risk instead sits with Shanghai Electric's margin: winning additional regional work may require aggressive EPC pricing and vendor financing, raising working-capital needs before the LTSA cash stream matures over 6-18 years after commissioning.
Watch for follow-on awards in Indonesia, Vietnam, Thailand and the Philippines within 6-12 months, plus disclosed contract value, advance-payment terms and project financing. The thesis is falsified if incumbents retain subsequent ASEAN CCGT awards without meaningful bid-price concessions, or if Shanghai Electric cannot convert expressions of interest into signed, financed contracts by 2027.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.62
Key Decisions for Investors
- No immediate directional trade in Shanghai Electric (02727 HK / 601727 CH) on this announcement alone; place on watch for contract value, payment schedule and margin guidance. Reassess only if two or more financed ASEAN turbine awards are signed within 12 months, which would support a backlog and service-annuity re-rating.
- Monitor a relative-value alert: long GEV versus short ENR only if ASEAN tender data show Chinese bids forcing material price cuts and ENR's gas-turbine order-margin guidance weakens. GEV's installed-base service mix should be more defensible; exit if ENR secures major ASEAN awards at stable or higher margin.
- For 6-18 month infrastructure exposure, favor selective ASEAN gas-to-power developers and grid suppliers over turbine OEMs until financing terms are known. The investable catalyst is final investment decisions and transmission build-out, not initial equipment awards; avoid extrapolating a single export reference into near-term OEM earnings.
More News
- Trump says U.S. may keep Iranian oil 'like Venezuela' as Gulf-Iran Hormuz talks stall
- Baker Hughes sees no slowdown in energy projects despite higher rates as AI buildouts stoke LNG demand
- U.S. stock futures slide on calls to slow AI development, M.East escalation
- Diplomacy stumbles with postponement of meeting on Strait of Hormuz proposal
- Oil prices rise after Saudi Arabia shut down critical pipeline that bypasses Strait of Hormuz
- Z.ai shares tumble over 10% after $5 billion fundraising, its second major raise in two months