
WuXi XDC Celebrates GMP Release of Singapore Site, Ushering in a New Era of Global Expansion
Source: PR Newswire
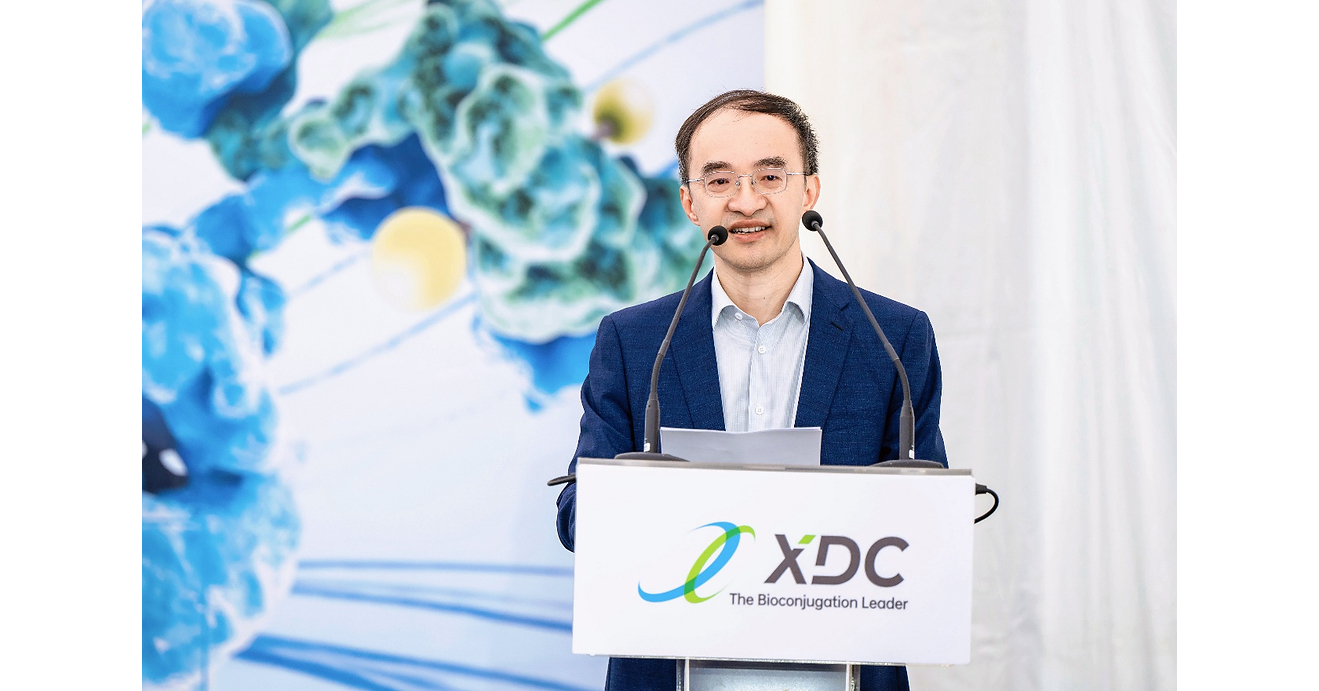
WuXi XDC completed GMP release for its first overseas manufacturing site in Singapore, bringing its BCM3 antibody intermediate/conjugated drug-substance line and DP4 drug-product facility into commercial readiness just 2.5 years after the project was announced. The 25,000-square-meter site can support up to 2,000 L drug-substance batches and up to 8 million liquid or lyophilized bioconjugate vials annually, advancing the company's global dual-sourcing strategy. A further BCM4 facility, with up to 500 L single-batch conjugated drug-substance capacity, is targeted for GMP release by year-end 2026.
Analysis
The investable implication is not the facility announcement itself but whether non-China capacity converts geopolitical diligence into signed commercial awards. For 2268.HK, a credible Singapore option should improve win rates with Western customers that previously treated China concentration as a procurement constraint, particularly for late-stage ADC programs where a supply interruption can destroy far more value than a modest CDMO price premium. The near-term P&L benefit is likely limited: commercial biologics assets typically require customer audits, tech transfer, validation batches and regulatory filings before meaningful utilization and revenue recognition.
The key 1-3 month catalyst is evidence of contracted backlog rather than site specifications: new commercial customer disclosures, utilization commentary, and any upward revision to capex, revenue or margin guidance. A second-order benefit could be pricing resilience versus China-only ADC manufacturing peers, as customers may pay for dual-source optionality; conversely, Singapore's higher labor, utilities and compliance costs could dilute gross margin if the site is ramped ahead of demand. Morimatsu Pharmadule (2155.HK) is a modest read-through beneficiary if this execution becomes a reference case for modular biopharma construction, but one completed project alone does not establish repeat order momentum.
Contrarian view: investors may over-credit the asset as an immediate de-risking event. GMP release is necessary but not equivalent to FDA/EMA inspection history, customer product approvals, or high-margin commercial throughput; the relevant proof point is successful client-specific validation and sustained fill-finish utilization. The thesis is falsified if 2268.HK reports weak new-order growth or lower gross margin during the ramp despite the overseas footprint, indicating that customer demand—not geographic concentration—was the binding constraint.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.50
Key Decisions for Investors
- Watch 2268.HK for a 1-3 month confirmation trade rather than chase the press-release reaction: initiate/add only following disclosed overseas commercial awards or backlog acceleration, with a 6-12 month horizon. Upside is multiple expansion from a China-only supplier discount narrowing; exit if management cannot quantify customer conversion or guides gross margin lower on Singapore ramp costs.
- Use 2268.HK as a relative-value long against a China-concentrated life-science outsourcing basket only after order-data confirmation. The pair isolates the value of geographic redundancy; key risk is industry-wide ADC funding weakness, which would reduce utilization across both legs regardless of location.
- Set an alert around the next results for three datapoints: Singapore utilization, overseas-client order mix, and incremental capex/operating-cost guidance. If utilization is not disclosed, treat the announcement as strategically positive but financially unverified and maintain no incremental position.
- Monitor 2155.HK for follow-on modular-facility awards over the next 6-18 months; consider it a watch-list beneficiary rather than a standalone trade until contract value, margin profile, and order-book conversion are disclosed.
More News
- All Iranian airlines to be 'shut down' from Wednesday, Bessent tells CNBC
- Taiwan benchmark Taiex rises to record intraday high as tech stocks advance
- AMD joins the $1 trillion club as chip rally surges - our AI Strategy saw it early
- Jamie Dimon says hyperscaler AI spending could hit $1 trillion next year
- Factbox-Key issues for this week’s Trump-Xi summit in Washington
- Brazil election: Lula and Flavio Bolsonaro tied in latest polls