
CrownPoint Partners Continues Florida Expansion with Numerous 2026 Closings
Source: PR Newswire
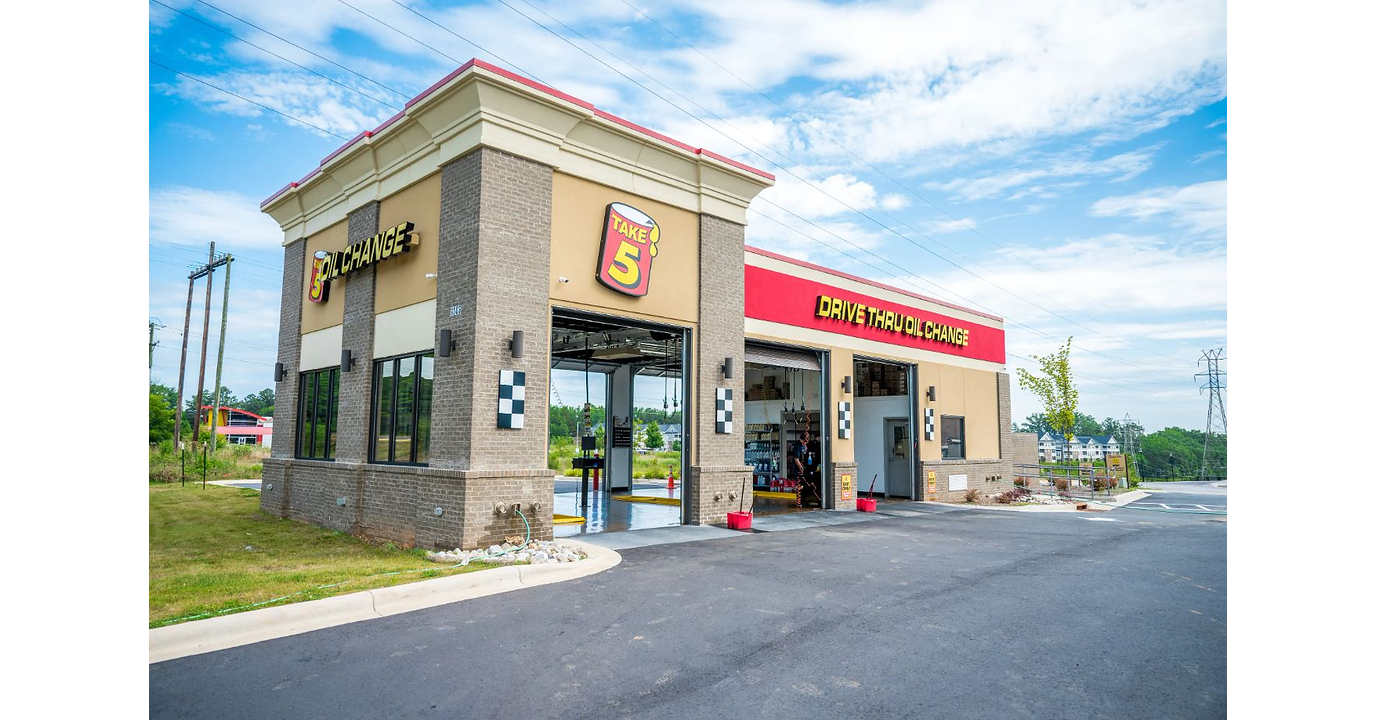
CrownPoint Partners reported numerous Florida commercial-real-estate closings in 2026 across net-lease, retail and healthcare assets, including two Jacksonville Wendy's transactions completed within 90 days. Other deals included a newly opened Take 5 Oil Change acquired through a 1031 exchange on a 20-year corporate-backed ground lease with 10% rent escalations every five years, and the sale of MSH Dental within 60 days after multiple offers. The activity highlights expansion in Florida and repeat-client transaction momentum, but no transaction values or material financial results were disclosed.
Analysis
This is not a fundamentals catalyst for WEN, HD, or TGT; the transactions are too small and privately brokered to alter reported earnings or valuation. The useful signal is marginal: private capital and 1031-exchange demand remain willing to fund Florida single-tenant assets despite a closed restaurant location being transferred rather than redeveloped. That supports liquidity for select net-lease real estate, but does not establish cap-rate compression without disclosed prices, financing terms, or buyer leverage.
For WEN, the closed unit is more relevant as a localized franchisee/site-selection datapoint than a demand signal. A replacement owner may pursue re-tenanting or redevelopment, underscoring that weak individual locations can retain real-estate value even when restaurant-level economics fail; this modestly reduces downside to franchisee asset values, not corporate royalty exposure. The key 1-3 month read-through is whether broader franchisee closures rise in upcoming system-sales and unit-count disclosures; isolated transactions should not affect the stock.
The stronger second-order implication is for publicly traded net-lease vehicles with Florida retail/healthcare exposure: sustained private-buyer demand can provide asset-value support if Treasury yields stabilize or decline. However, private 1031 capital is rate-sensitive and can evaporate quickly if long-end yields rise, while Florida insurance, property-tax and climate-risk costs can widen required cap rates over 6-18 months. Consensus may overinterpret transaction velocity as broad commercial-real-estate recovery; transaction count alone says little about clearing values.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.32
Key Decisions for Investors
- No directional trade in WEN, HD, or TGT on this item; require unit-level closure trends, franchisee health metrics, or Florida sales data before assigning earnings relevance.
- Watch-listed relative-value setup: long NNN or ADC versus short VNQ only if 10-year Treasury yields decline by at least 25 bps and subsequent net-lease transaction disclosures show stable-to-lower cap rates over the next 1-3 months. The thesis is that necessity/service-oriented net lease rerates faster than diversified CRE; invalidate if reported acquisition cap rates widen or AFFO guidance is cut.
- For WEN, treat a material rise in net closures or a reduction in franchisee development commitments at the next earnings update as a downside alert. A broad-based unit contraction would pressure royalty growth and could justify a short versus QSR; absent that evidence, the isolated closure is noise.
- Monitor Florida-focused REIT and net-lease commentary for insurance and property-tax expense escalation over the next two reporting cycles. If those costs outrun contractual rent escalators, avoid treating apparent asset-sale liquidity as a durable NAV floor.
More News
- Instacart should be worried about DoorDash and Uber's new deal
- Australia’s central bank chief warns inflation risks materialising
- This AI-picked stock jumps 18% on Amazon’s $8 billion power deal
- US to Sell F-35s to Saudi Arabia in $24.3 Billion Deal
- Crusoe raises $3.9B to build massive data centers and small modular “AI factories”
- Jensen Huang says Nvidia will sell twice as many chips next year