
TCL продвигает свои амбиции в области смартфонов с серией P80 на IFA 2026
Source: PR Newswire
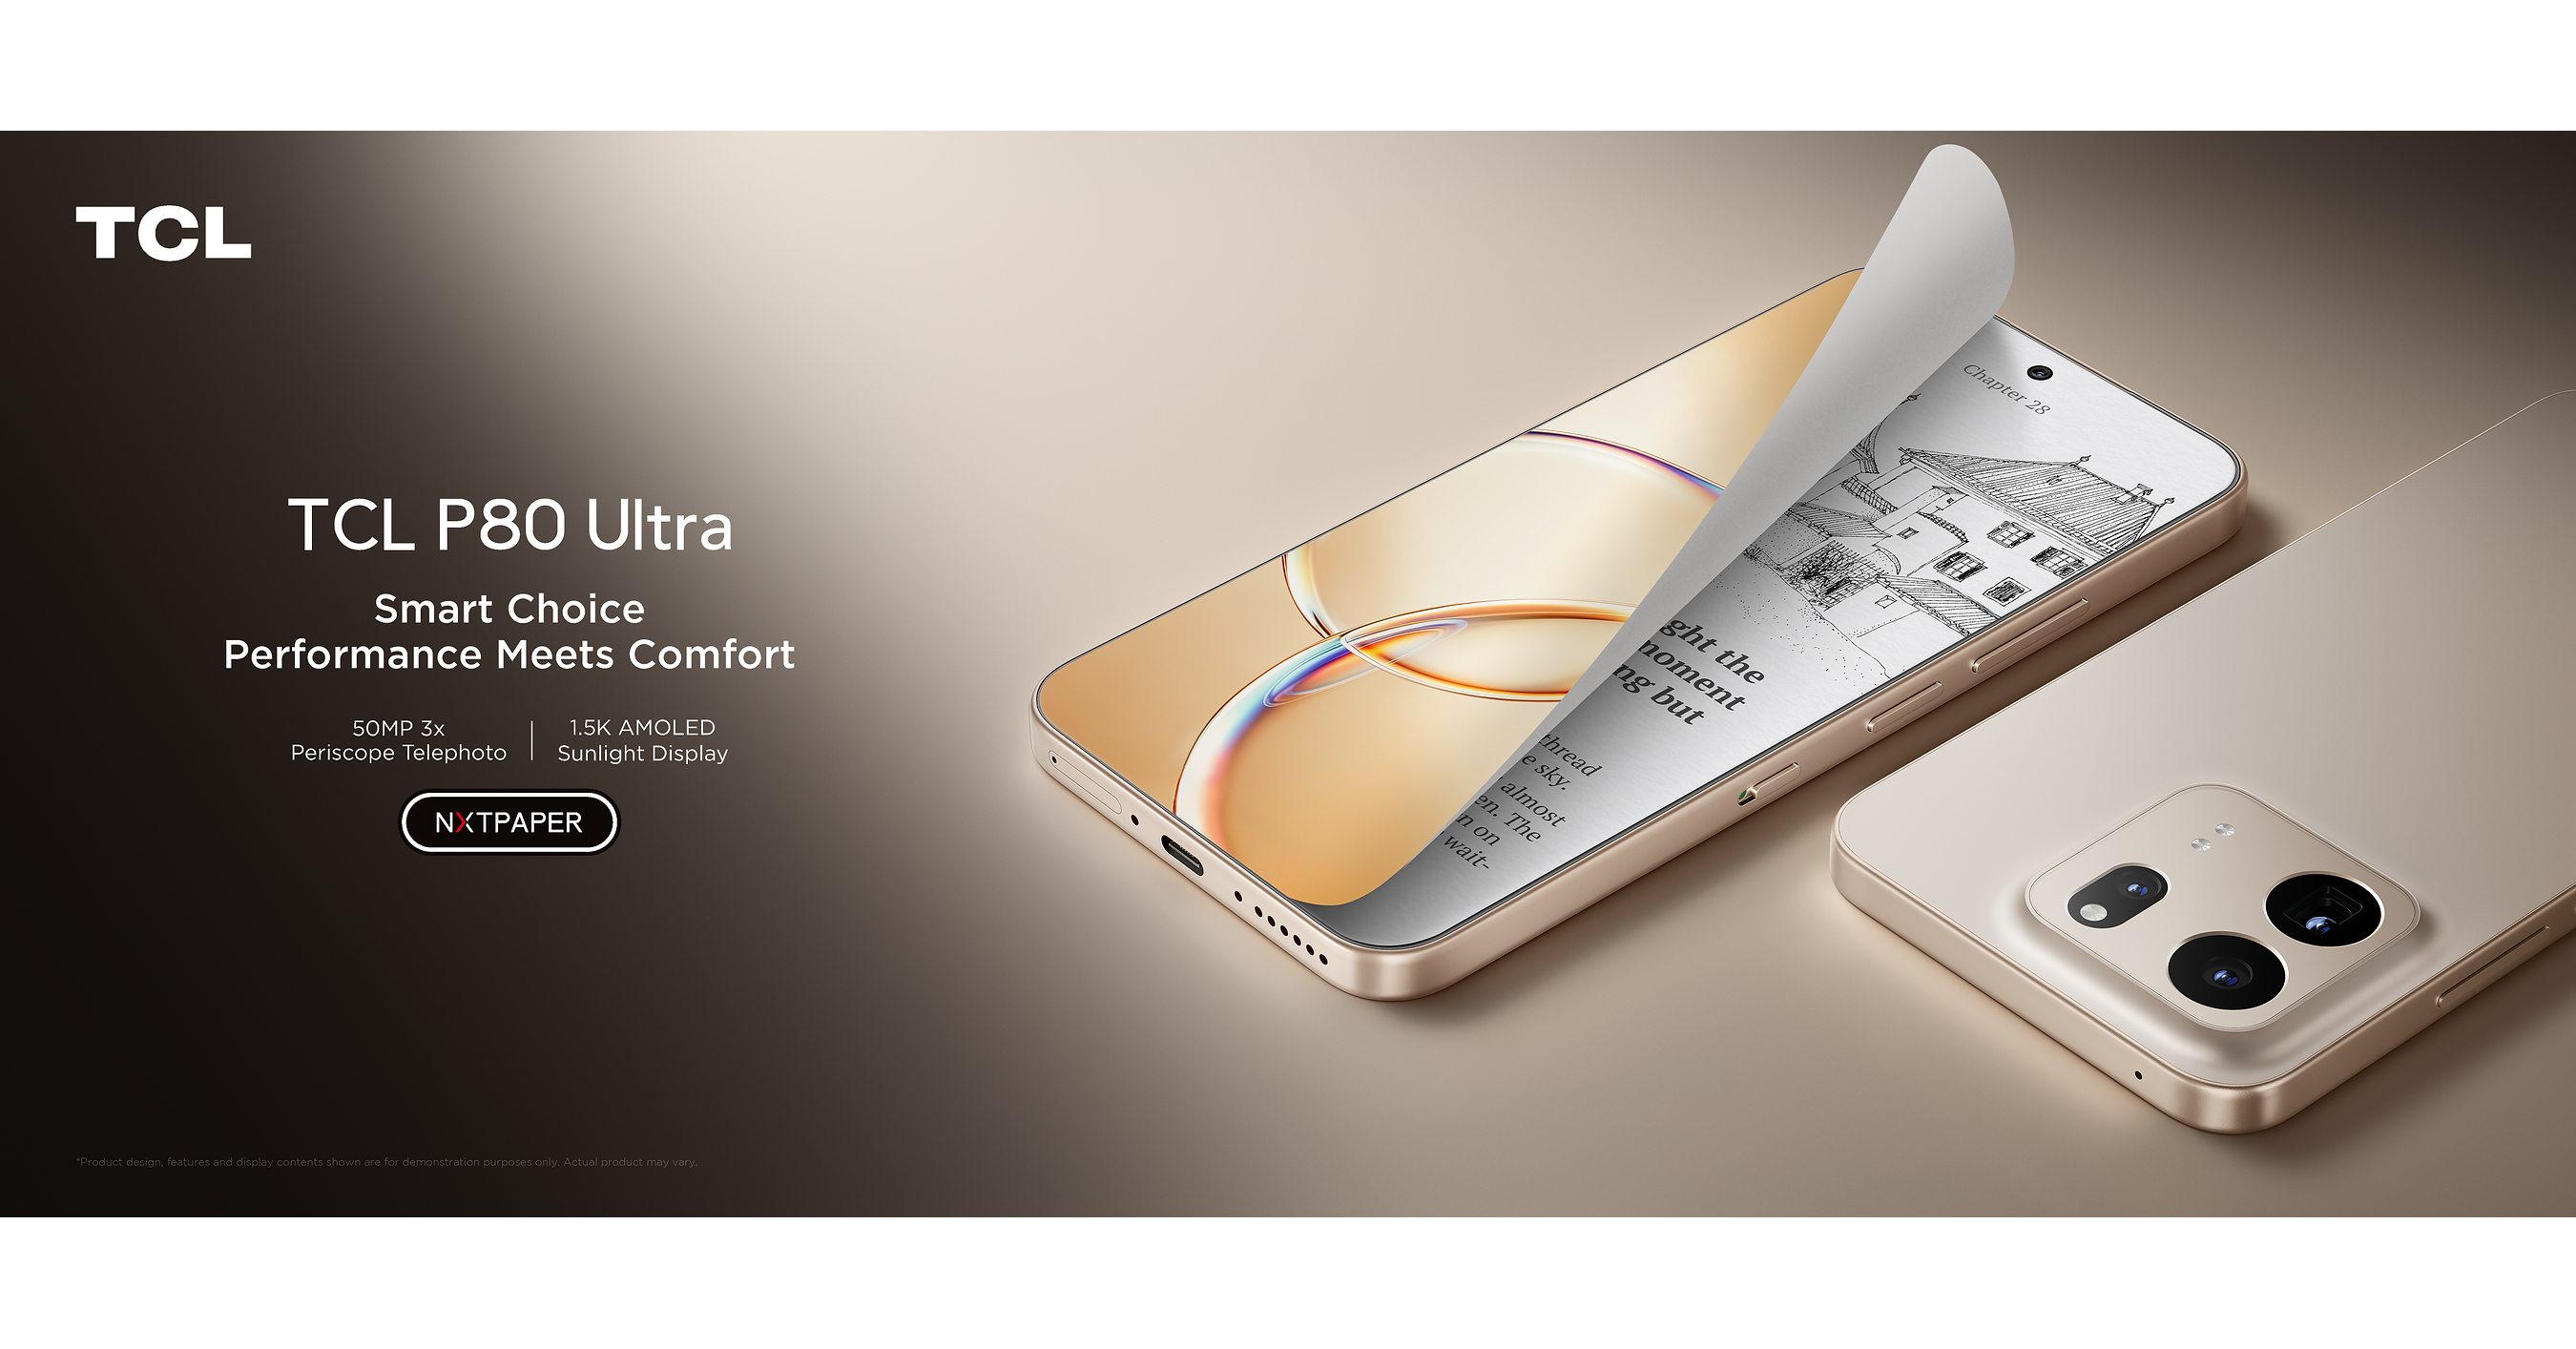
TCL на IFA 2026 представила линейку смартфонов P80 (P80 Ultra, P80 Pro и P80) с упором на мобильную фотографию, комфорт дисплеев и автономность. В P80 Ultra ключевой акцент — 50-мегапиксельный телеобъектив с 3-кратным перископическим зумом, а P80 Pro получил AMOLED 1.5K NXTPAPER и батарею 5 800 мАч с хранилищем до 512 ГБ. Новинка использует технологию NXTPAPER AMOLED для снижения бликов и воздействия синего света, но конкретных цен/дат продаж в тексте не указано, поэтому влияние на рынки скорее локальное.
Analysis
This reads as a brand-building exercise, not a near-term earnings catalyst. In smartphones, feature launches only matter if they change channel economics: carrier placement, retail sell-through, and repeat purchase behavior. Without evidence of meaningful volume, the likely financial effect is limited to modest gross-margin pressure from higher-spec BOMs and marketing spend, offset only if TCL can pull through more ecosystem sales in TVs, tablets, or accessories.
Competitive impact is incremental but not zero. TCL is trying to carve out a defensible niche around display comfort and imaging, which puts pressure on value-premium Android OEMs rather than true flagships; that means the main read-through is on the crowded sub-$400 to mid-tier segment where differentiation is weak and promotions decide share. If the product gets shelf space, the bigger winner may be component vendors with camera modules and display-related content, but the article does not support a measurable demand inflection yet.
The key risk is that this is a marketing announcement that fades quickly unless independent channel data confirms traction in 1-3 months. Over 6-18 months, the thesis only becomes investable if TCL can show that premium mobile launches improve ecosystem attach rates or lower customer-acquisition cost; otherwise the initiative is dilutive to margins. Contrarian view: the market may miss the value of TCL’s display IP as a cross-sell weapon, but that benefit is structural and slow-moving, not a near-term P&L driver.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.12
Key Decisions for Investors
- No immediate directional trade in handset OEMs; the launch is too small to justify a short in Samsung Electronics (005930.KS), Xiaomi (1810.HK), or Lenovo (0992.HK) before channel checks confirm share shift. Reassess after 4-6 weeks of sell-through and pricing data.
- Set an alert on Qualcomm (QCOM) and MediaTek (2454.TW) for any disclosed design-win or shipment commentary tied to TCL premium devices; without volume confirmation, the supply-chain read-through is not actionable.
- If regional retail data later shows TCL taking share in the value-premium Android tier, consider a tactical pair: long TCL-exposed display/component names versus short a basket of low-end Android assemblers. For now, the risk/reward is poor because the catalyst is unverified.
- Watch for evidence that NXTPAPER is driving higher ASPs or lower returns rather than just higher BOM cost; that would be the first sign the story can support a 6-18 month margin expansion thesis.
More News
- Indonesian stocks plunge to six-year low as MSCI downgrade fears mount
- Putin reportedly suggests summit with Trump and Xi to decide fate of Ukraine
- China's CXMT sees shares drop over 6% as investors look past chipmaker's profit turnaround
- China's economic growth quickens to 4.6% as exports surge, stimulus rolls out
- Australia’s Cleanaway agrees to $6.5 bln EQT buyout bid; shares surge
- India’s Finance Minister blames easy exits and excess liquidity for equity market's underperformance
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Index and ETF Holdings Data for AI Research
- Capital Intensity as Gravity: The AI Trade Enters Its Industrial Era (Looking at Q3 2025 Earnings in Tech)