
XCMG legt in Indonesien den Grundstein für seinen ersten Auslandsstandort zur Überholung und Wiederaufarbeitung von Bergbaumaschinenkomponenten
Source: PR Newswire
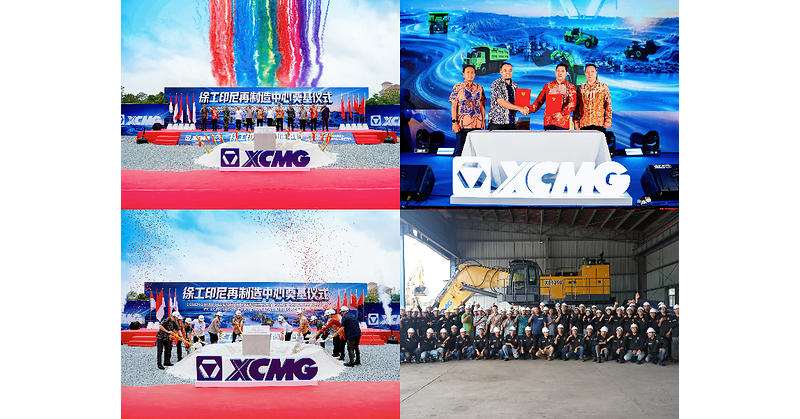
XCMG broke ground on its first overseas remanufacturing center for mining-equipment components in Balikpapan, Indonesia, expanding its localized aftermarket service capabilities across repairs, parts warehousing and on-site support. The facility is intended to reduce equipment downtime and customer-service response times while lowering mining customers' operating costs and improving machine availability. The project follows XCMG's September launch of Indonesia Finance Company (ABC Multi Finance), as well as the 2026 opening of local new-energy manufacturing and R&D facilities, reinforcing its integrated Indonesia expansion strategy.
Analysis
The strategic significance is less near-term equipment revenue than a shift toward controlling the installed base: localized parts, rebuilds, and financing can raise customer switching costs and convert one-off machine sales into recurring service, parts, and credit income. In Indonesian mining, where utilization and downtime dominate purchase decisions, this can pressure CAT, Komatsu (6301 JP), Hitachi Construction (6305 JP), and Chinese peer SANY (600031 CH) at replacement cycles, particularly among cost-sensitive coal and nickel operators. The second-order effect is likely margin dilution for independent repair shops and parts distributors rather than an immediate share loss for global OEMs.
The bundled-finance model is the key risk variable. It can accelerate unit placement in the next 1-3 months, but it also transfers commodity-cycle and customer-credit exposure onto the OEM ecosystem; a downturn in Indonesian coal or nickel prices could turn higher equipment penetration into rising delinquencies, repossession costs, and used-equipment price pressure over 6-18 months. Company-sponsored claims around uptime and lifecycle savings should be treated as unverified until utilization, parts fill-rate, receivables, and warranty data are disclosed.
There is no clean immediate listed-equity trade from this announcement alone, and the likely market impact is negligible. The underappreciated implication is that global OEM aftermarket multiples are most vulnerable only if localized Chinese competitors demonstrate sustained parts availability and financing discipline; without those two proof points, customers may still pay a premium for CAT/Komatsu reliability and residual values.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Key Decisions for Investors
- No directional trade on the announcement; create a 3-6 month watchlist around CAT, 6301 JP, 6305 JP, 600031 CH, and 000425 CH. Escalate only if Chinese OEMs report Indonesian mining share gains alongside improved service/parts revenue rather than discount-driven equipment growth.
- Monitor Indonesian coal and nickel benchmarks, plus financing-company receivables and non-performing-loan disclosures where available. A material commodity drawdown coupled with expanding OEM captive-finance books would support a bearish view on Chinese construction-equipment manufacturers; absent credit data, do not initiate.
- For relative-value positioning, retain a conditional long CAT / short 600031 CH framework over 6-12 months: CAT's aftermarket depth and residual-value franchise should outperform if Chinese localization requires aggressive financing or warranty support. Falsify the trade if SANY demonstrates stable credit metrics and recurring aftermarket growth while CAT reports Indonesia-specific order or parts-margin weakness.
- Watch CAT and Komatsu earnings calls for Indonesia/Asia-Pacific parts growth, dealer inventory, and competitive pricing commentary. A guidance cut tied to mining aftermarket share or sustained price concessions would be the actionable trigger to reduce exposure, not the construction milestone itself.
More News
- Trump says U.S. to build a 'large Military presence' in Greenland as part of a security deal with it and Denmark
- Houthis accuse Saudi Arabia of launching 26 strikes in 24 hours
- European Economies Eye Another Energy Crisis Heading Into Winter
- AI almost led the US military to start a war with China, report says
- Warren Buffett stepping down as chairman of Berkshire Hathaway: 'Father Time always wins'
- After threatening to seize Greenland by force, Trump agrees to leave it with Denmark and boost military presence. ‘We will be very protective of it!’
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AllMind's Data Standardization Methodology: Our Approach to Fundamentals
- What Makes Financial Data Ready for AI Research?