
Sinopec y sus socios internacionales lanzan una iniciativa para impulsar la cooperación global CCUS
Source: PR Newswire
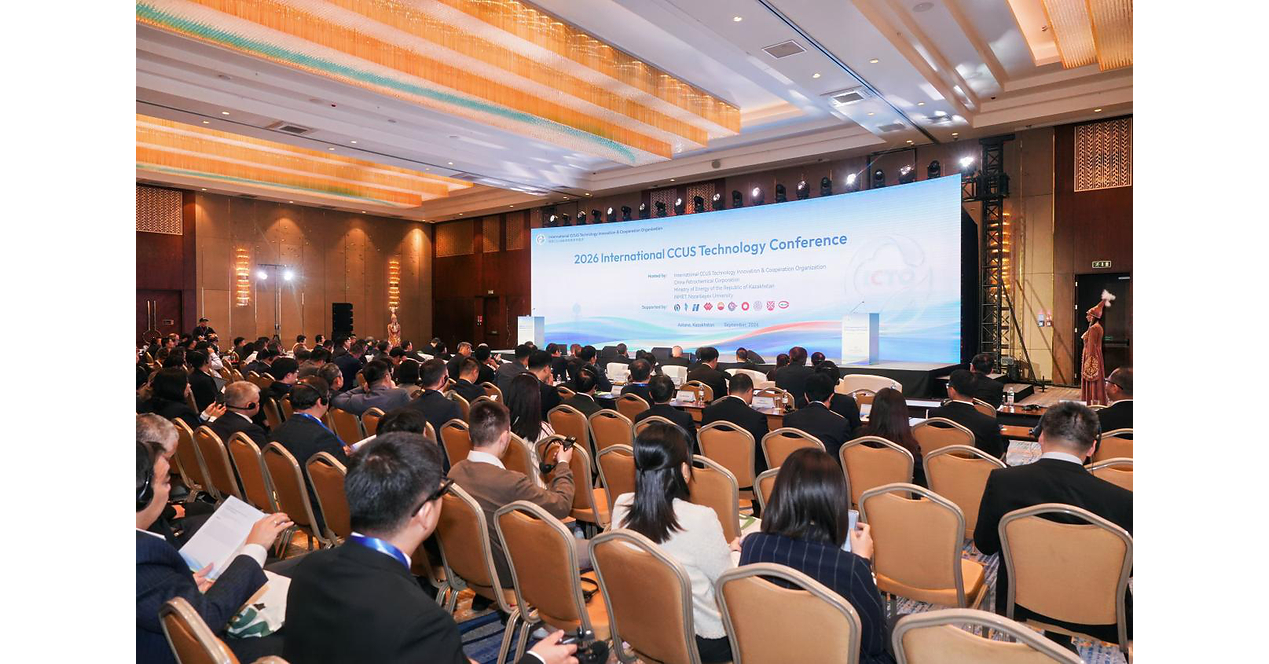
Sinopec (HKG:0386) anunció una Iniciativa de Cooperación para el Desarrollo de Energía de Bajo Carbono junto con ICTO, el Ministerio de Energía de Kazajistán y la Nazarbayev University, enfocada en CCUS (captura, uso/almacenamiento y mineralización). La compañía destacó su capacidad y avances: un gasoducto de CO2 de 100 km en China y un proyecto de demostración integrado con 1 Mt/año, además de un estudio con Shell, BASF y China Baowu para un clúster CCUS “open access” de 10 Mt/año. El anuncio sugiere impulso de colaboración tecnológica y marcos de despliegue para CCUS, con impacto probablemente limitado a corto plazo en mercados, pero favorable para la narrativa de transición baja en carbono.
Analysis
This reads as strategic positioning, not an immediate earnings catalyst. The near-term market impact for SHEL and SNPMF is likely limited because CCUS economics are still dominated by policy durability, transport/storage liability, and customer offtake, none of which are resolved by a cooperation announcement. The real value is optionality: being early in standards-setting and hub design can help win future project flow, especially in Asia where state-backed infrastructure can compress permitting and counterparty risk.
The second-order winners are the picks-and-shovels names that monetize the network, not the capture chemistry. That favors industrial gas, compression, monitoring, and subsurface service providers more than pure-play CCUS developers, because open-access hubs tend to commoditize capture units while margin migrates to transport, storage, and long-term operations. For Shell, the upside is relative rather than absolute: a stronger low-carbon infrastructure franchise can support a premium narrative versus European peers, but only if announcements convert into FEED/FID and not just MoUs.
Contrarian view: the market may be overestimating how quickly CCUS becomes self-funding. If carbon prices stay too low or subsidy regimes wobble, these projects can turn into capex sinks with long paybacks, and the EOR linkage weakens if oil prices fall. Over 1-3 months, watch for disclosed project economics or partner commitments; over 6-18 months, the thesis is falsified if there are no sanctioned hubs, no storage permits, or no repeatable revenue model beyond government relations.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.18
Ticker Sentiment
Key Decisions for Investors
- Stay neutral on SNPMF for now; this is a watch-item, not a high-conviction buy, until management discloses project capex, funding split, and expected IRR/FID timing.
- Use SHEL as a relative-value long only on confirmation of a CCUS FID or commercial offtake structure; otherwise the announcement is mostly narrative optionality. Time horizon: 3-6 months.
- Prefer a CCUS picks-and-shovels basket on pullbacks: LIN and APD are better expressions of infrastructure monetization than pure-play capture developers over a 6-18 month horizon.
- Relative-value idea: long SHEL / short BP over 3-6 months if Shell continues to win Asia CCUS hub roles and BP lacks a comparable pipeline; stop if project conversion stalls or Europe policy weakens.
- Set an alert for any policy package in China/Kazakhstan that clarifies carbon pricing, storage liability, or tax support; without that, the thesis is likely to fade and any rally should be sold.
More News
- Putin reportedly suggests summit with Trump and Xi to decide fate of Ukraine
- Ukraine launches over 1,000 drones at Russia, setting oil facilities ablaze
- China's CXMT sees shares drop over 6% as investors look past chipmaker's profit turnaround
- Trump defends Russian sanctions relief, lashes out at Zelenskyy
- China’s Coal Output Drops as Concerns Build Over Winter Supply
- Asian stocks skid, Wall Street and bonds aided by oil slip