
Security Properties Acquires 186-Unit Cooper Apartments in North Seattle at 28% Below Its 2019 Sale Price
Source: PR Newswire
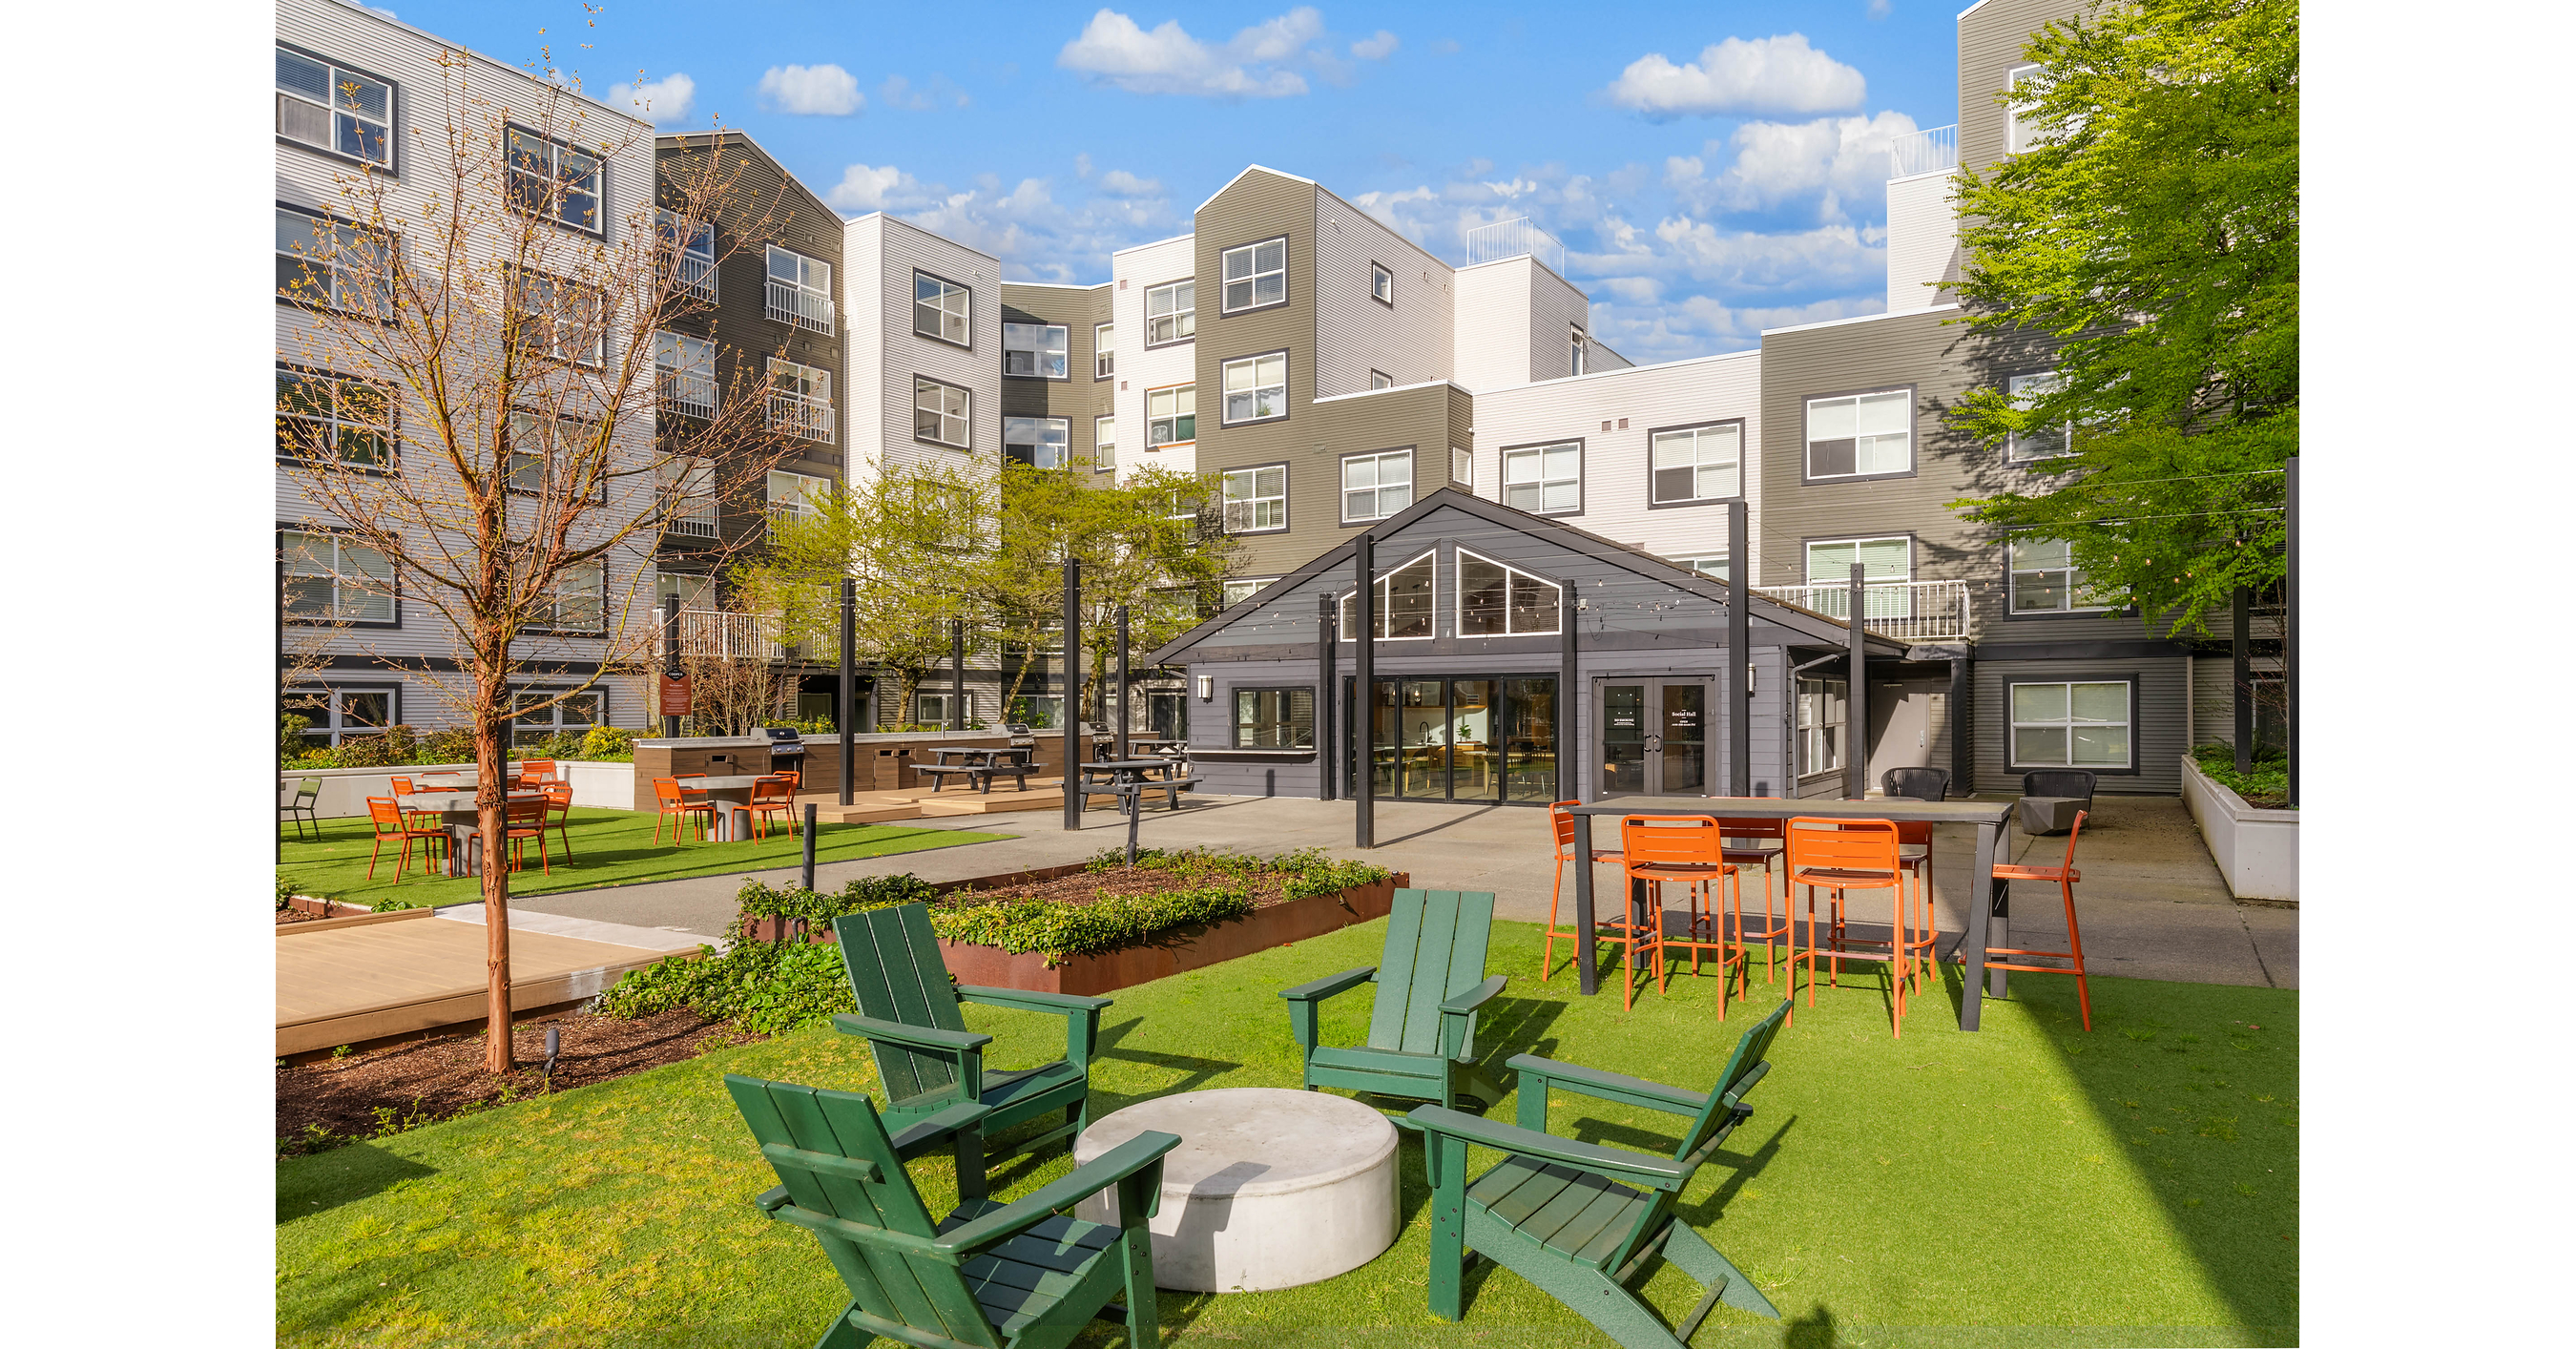
Security Properties acquired the 186-unit Cooper Apartments in North Seattle for $37.75 million, or about $203,000 per unit—28% below its 2019 sale price of $52.75 million and less than half estimated replacement cost. The property has received more than $6.8 million in improvements, and its purchase price was below all 11 cited comparable sales, which ranged from about $270,000 to $426,000 per unit. North Seattle-area apartment deliveries are forecast to decline from 2,626 units in 2024 to roughly 500 annually in 2026–27 and zero in 2028–29; Cooper's average in-place rent is $1,866 per month versus an estimated $5,572 monthly cost to own a median-priced North Seattle home.
Analysis
This is evidence of selective private-market risk appetite, not a reliable mark for Seattle apartment values. The apparent discount to the 2019 sale and replacement cost is not an operating yield: without occupancy, concessions, actual rent comps, debt terms, and remaining capital needs, the purchase price cannot establish a valuation floor. The improvements may reduce near-term capex, but they do not prove achievable rent premiums.
The useful second-order signal is supply: if deliveries in the cited submarkets do fall, less competition could improve leasing and pricing for existing landlords over the next 1–3 years. That would benefit well-located assets more than developers with projects dependent on new construction economics. However, CBRE both brokered the deal and is cited for the supply forecast; treat the forecast as a scenario, not an independently verified catalyst. Rates, insurance, property taxes, and Seattle rental regulation could offset better leasing.
For public markets, any read-through to apartment REITs—including AvalonBay Communities, Equity Residential, and Essex Property Trust—is conditional on confirming their Seattle exposure and asset-level operating trends. A single private transaction should not drive a sector multiple call. The structural case improves if deliveries contract and effective rents strengthen; it is falsified by persistent concessions, weak occupancy, or continued project completions. Near term, this is more a watch signal than a trade catalyst.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Key Decisions for Investors
- No immediate public-equity trade: Security Properties is private, and this single purchase does not establish a comparable valuation for listed landlords.
- Over the next 1–3 months, verify Seattle exposure and submarket leasing metrics in AvalonBay Communities, Equity Residential, and Essex Property Trust filings before considering a relative-value position; avoid inferring exposure from this transaction alone.
- Track effective rent growth, occupancy, concessions, and actual deliveries through 2027. A supply-led long bias toward existing multifamily owners becomes more credible only if leasing improves as deliveries decline.
- Treat the reported below-replacement-cost basis as a diligence lead, not downside protection. Reassess if property-level occupancy or rents weaken, capital needs exceed the claimed completed work, or Seattle operating costs and regulation materially erode net income.
More News
- Marvell to buy Lumentum in $115 billion deal in AI data-center bet
- Statement by the Monetary Policy Board: Monetary Policy Decision
- Marvell, Lumentum tout historic $115B deal to create ‘category leader' in AI connectivity
- Palantir reports booming U.S. commercial revenue growth, topping government for first time
- Anthropic releases amended IPO prospectus with third-quarter financials
- Coinbase has been battered over the past month. Morgan Stanley says steer clear