
Dangote Gets Regulator’s Approval for $1.6 Billion IPO
Source: Bloomberg
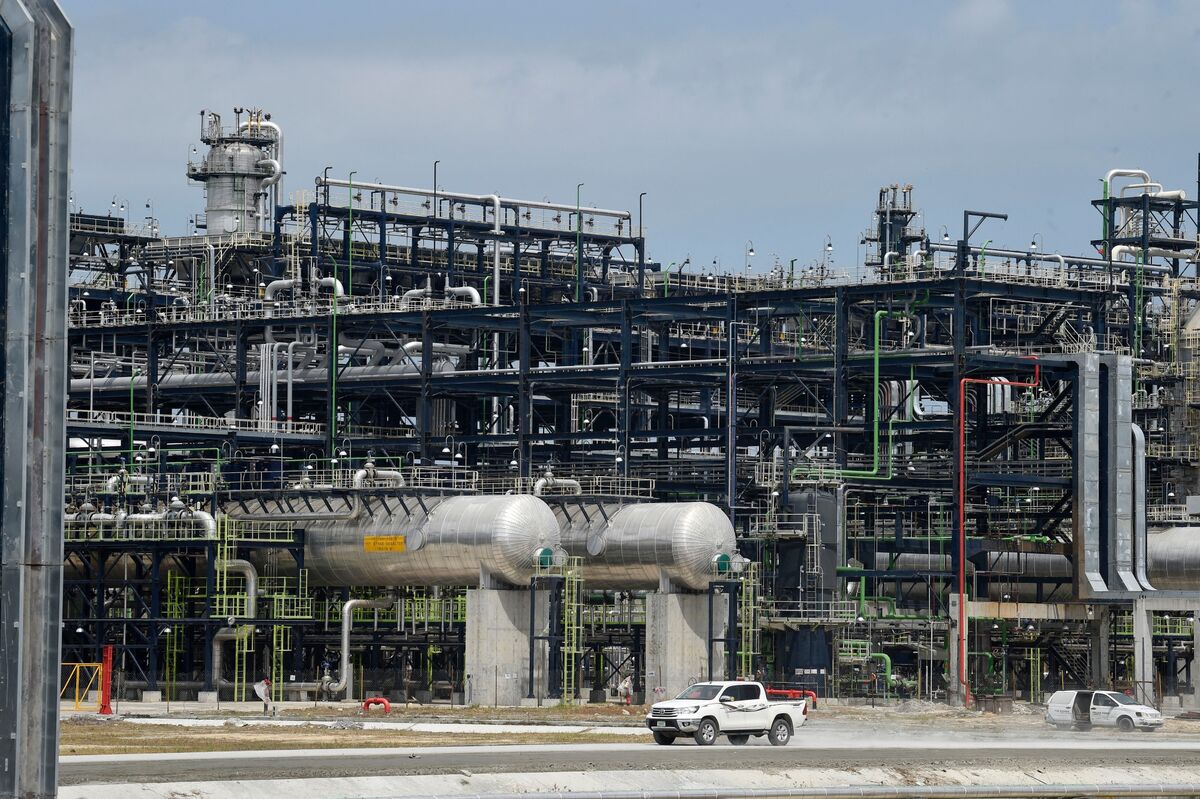
Aliko Dangote’s Dangote Petroleum Refinery and Petrochemicals has received regulator approval to raise $1.6B via an IPO, offering 4.1B shares at 525 naira each. The deal will open Sept. 14, with investor attention focused on funding for Africa’s largest refinery project.
Analysis
This is more a signal about monetizing a strategic asset than a clean operating call. If the IPO is well-subscribed, it can re-rate perceptions of Nigerian industrial assets and reopen primary issuance, but the business itself is still exposed to the classic refinery traps: feedstock reliability, FX conversion, working-capital intensity, and policy interference. In other words, the first move is likely sentiment-driven; the second move depends on whether disclosed throughput and cash conversion look real.
Near term, the main winners are local capital-markets participants and any domestic suppliers that gain from a larger listed industrial base; the obvious losers are import-dependent fuel distributors and product-trading intermediaries whose margin pool shrinks if local supply rises. A less obvious loser is the regional product-tanker complex: if this plant displaces West African imports over 6-18 months, tonne-miles on short-haul refined product routes can soften even if global crude shipping remains intact.
The contrarian risk is that investors overpay for strategic importance and underwrite monopoly economics that may never show up in equity cash flows. If post-listing disclosures reveal low utilization, expensive debt funding, or persistent naira mismatch, the stock can de-rate quickly even with strong headline demand. The key catalyst window is the first 1-3 months after pricing, when float absorption and secondary-market liquidity will determine whether this trades like a national champion or another illiquid EM industrial name.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- Do not chase the IPO into the open: wait 1-2 weeks for real float data, order-book quality, and first indications of turnover before taking exposure to AFBCF.
- If AFBCF trades 10-15% below issue price after the initial allocation overhang clears, consider a small starter long for a 1-3 month mean-reversion trade; stop if price loses the post-IPO support zone on heavy volume.
- Fade any >20% first-week pop in AFBCF unless management proves near-term utilization and cash conversion with hard disclosures; the business model is too working-capital heavy to justify utility-like multiples without evidence.
- For a 6-18 month thematic pair, consider long AFBCF vs short STNG if operational data shows sustained domestic refining ramps and import displacement; abandon the pair if throughput disappoints or FX costs spike.
- Set an alert for the first quarterly operating update: the thesis is falsified if utilization, receivables, or FX-related funding costs materially worsen versus IPO marketing assumptions.
More News
- Indonesian stocks plunge to six-year low as MSCI downgrade fears mount
- Indonesia Said to Meet Monday With MSCI Over Shock Index Threat
- Nifty Bank Heavyweights HDFC, ICICI in Focus After Weekend Earnings
- China's CXMT sees shares drop over 6% as investors look past chipmaker's profit turnaround
- Asian stocks skid, Wall Street and bonds aided by oil slip
- Australia’s Cleanaway agrees to $6.5 bln EQT buyout bid; shares surge
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Bitcoin's 52% Crash Proves It's a Tech Stock: Here's What That Means for Portfolio Construction
- What Is an AI Investment Research Platform?