
Exus Renewables North America Completes Highland North and Cambria Wind Repower Projects in Cambria County, Pennsylvania
Source: PR Newswire
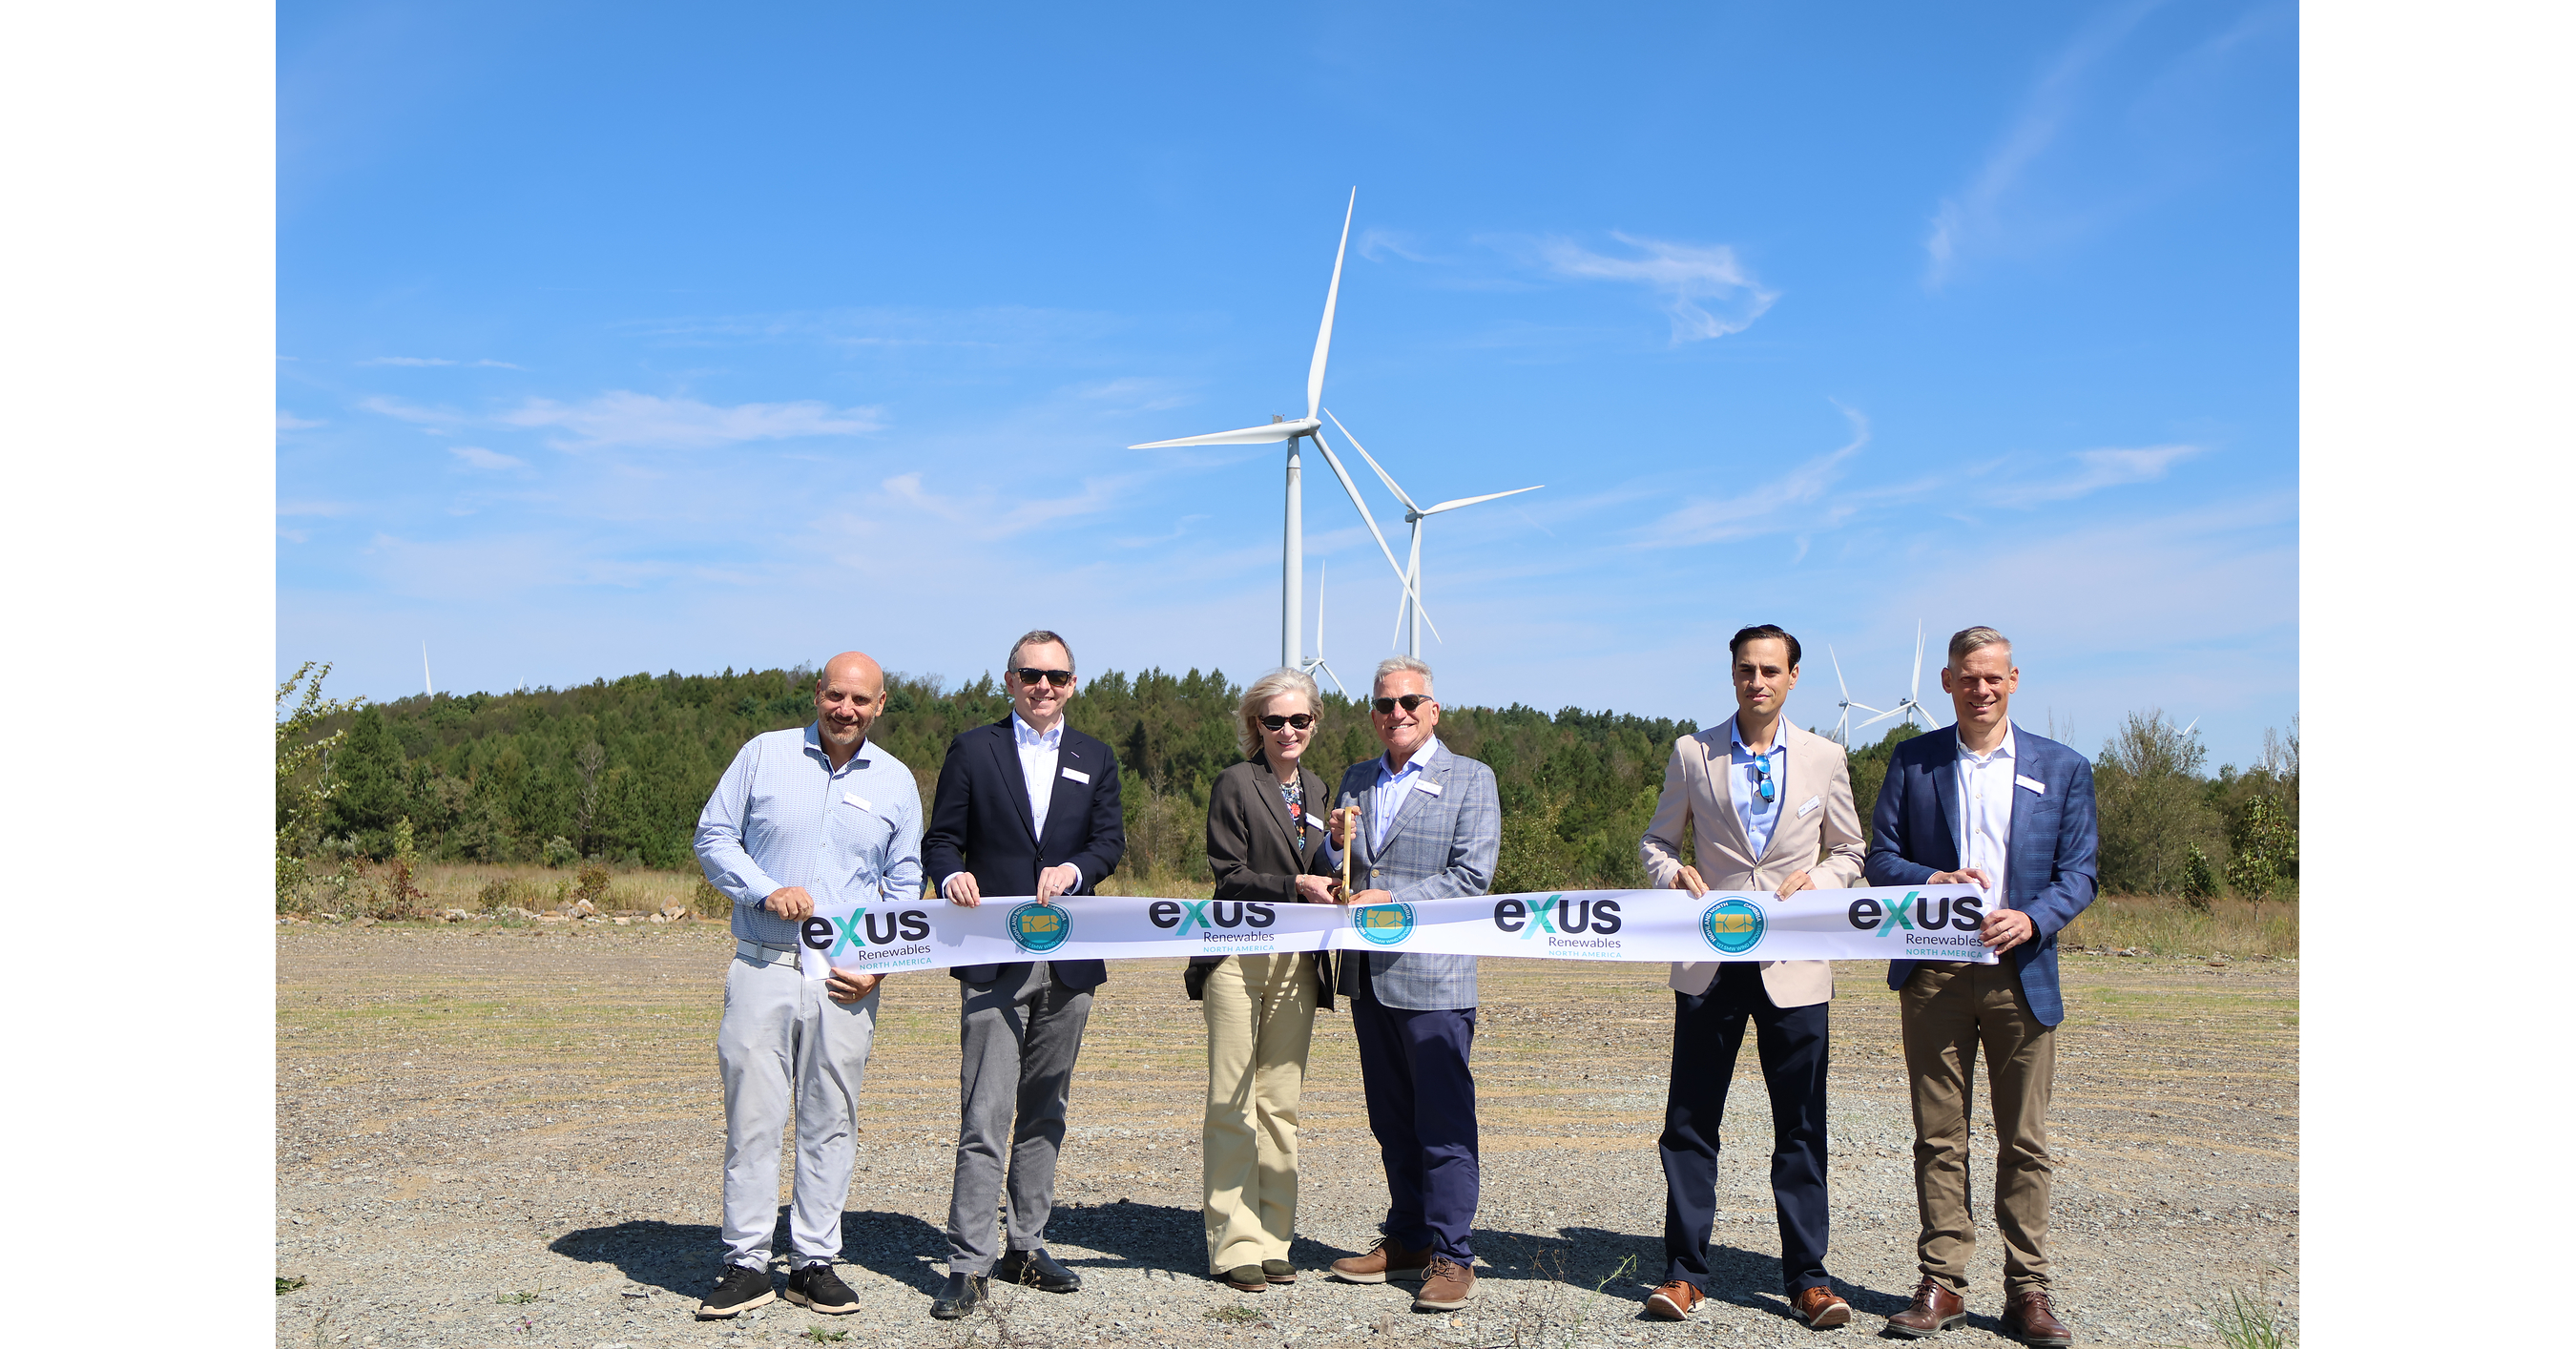
Exus Renewables completed repowers of the 61.6 MW Cambria and 75 MW Highland North wind farms in Pennsylvania, lifting its owned state wind capacity to 306.9 MW. The projects were financed with roughly $356 million led by KeyBanc and extend operating lives by 30 years; Cambria's generation is contracted under a PPA with a Fortune 500 technology company amid rising data-center power demand. Partners Group has committed more than $1 billion to Exus, while the two projects are projected to generate approximately $77 million in local taxes, fees and landowner payments over 30 years.
Analysis
This is strategically positive for Vestas (VWS) because repowering is becoming a scarce-channel alternative to greenfield wind: existing grid interconnection, local permits, and operating history can compress development risk materially. The financial significance of two projects is likely immaterial to VWS earnings, but the read-through matters if hyperscaler procurement shifts toward contracted, near-term capacity rather than waiting for new-build projects. That favors OEMs with an installed-base service relationship and proven retrofit capability, while pressuring smaller developers whose value proposition depends on securing new interconnection rights.
For Partners Group (PGHN), the relevant mechanism is infrastructure capital deployment rather than near-term fee impact. Successful construction completion and a corporate offtake agreement reduce project-risk premia and improve the markability/exit value of private renewable portfolios; however, the asset-level leverage implied by the financing raises sensitivity to power-price basis risk, curtailment, and refinancing costs. Over 6-18 months, congestion in PJM and the gap between intermittent generation and data-center 24/7 load could make firmed renewables—wind paired with storage, gas backup, or nuclear-linked contracts—more valuable than standalone wind PPAs.
Consensus may overread corporate clean-power demand as a blanket wind-equipment catalyst. Buyers increasingly require deliverable hourly power, and a conventional PPA does not eliminate congestion or shape risk; that can cap willingness to pay for unbundled wind output. The key falsifier for the constructive repowering thesis is evidence that PJM curtailment/basis differentials widen or that corporate buyers begin favoring dispatchable clean-power contracts over renewable-energy-credit-backed PPAs.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.58
Ticker Sentiment
Key Decisions for Investors
- No standalone VWS position solely on this announcement; use it as a watch signal for a broader North American repowering-order cycle. Upgrade only if VWS reports sustained North American order intake, improving service revenue, or margin-accretive repower backlog over the next 1-2 earnings cycles.
- Maintain a modest 6-18 month long bias in PGHN versus more transaction-dependent alternative-asset managers only if infrastructure fundraising and realizations remain resilient; renewable construction de-risking supports NAV quality, but the direct earnings contribution is too small for a catalyst trade.
- Monitor PJM capacity-auction results, renewable curtailment data, and corporate PPA pricing over the next 3-6 months. A widening PJM basis discount or rising negative-price hours would favor avoiding unhedged standalone renewable developers and favor firms with storage or contracted firming capacity.
- For listed clean-power exposure, prefer a basket tilted toward grid/storage beneficiaries over pure wind developers if data-center demand is the thesis; enter only after confirmation that load growth is translating into capacity awards and interconnection approvals rather than merely bilateral PPA announcements.
More News
- Wall Street’s Nasdaq hits all-time high as AI frenzy gathers pace
- Data-Center Bet Makes ESDS One of India’s Best New Listings
- Asia stocks ride tech wave higher, oil stays subdued
- South Korean solar stocks jump as curbs on Chinese sector expected to remain in place
- ‘I have a big decision to make’: Trump had a ‘good meeting’ with Iranian officials warning he may ‘annihilate the Islamic Republic’
- Zelenskyy says Ukraine ready for energy truce with Russia after Trump talks