
Morgan Stanley warns of a 7% S&P 500 dip as rebound catalysts emerge
Source: invezz.com
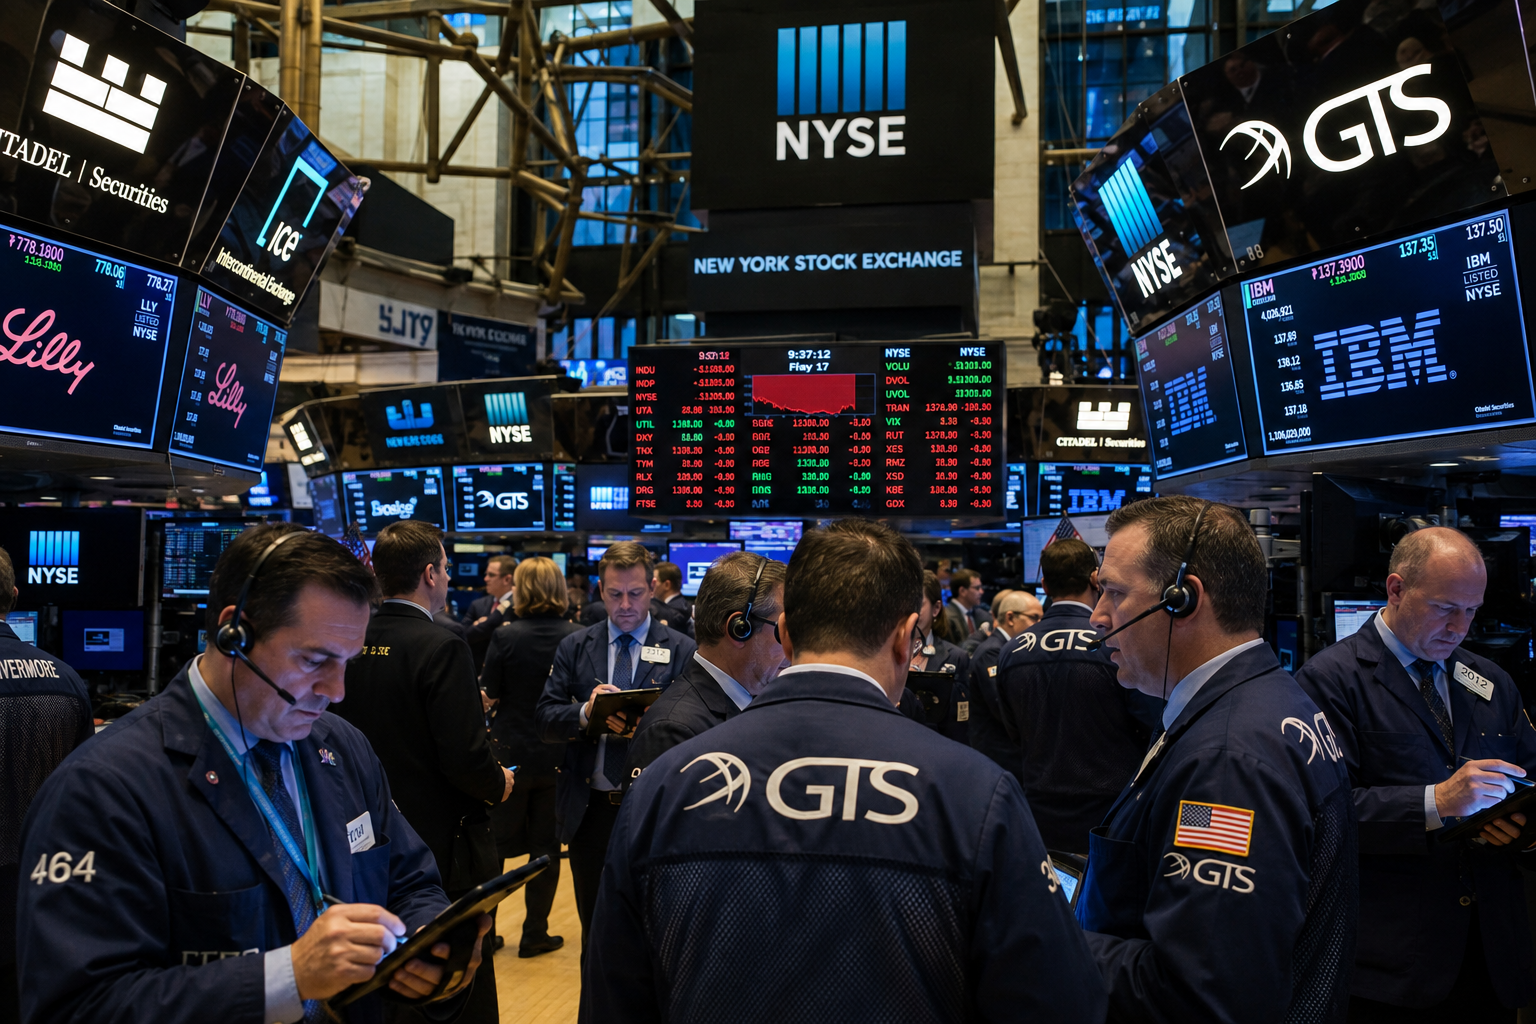
Morgan Stanley strategist Mike Wilson warned the S&P 500 could decline about 7% to 7,100 if tighter financial conditions, bond-market volatility and higher energy prices worsen, despite the index recently reaching 7,650. Offsetting the bearish near-term call, Q3 earnings growth is projected at 28% by FactSet, VOO has attracted more than $140B in assets this year, and the S&P 500's 19.1x forward P/E is slightly below its 19.3x five-year average. Technical indicators remain constructive, with the index above its 50- and 100-day EMAs and potentially targeting its 7,820 all-time high after any correction.
Analysis
The actionable variable is not the index target but the joint behavior of real yields, credit spreads, and crude. A modest equity drawdown can become self-reinforcing if higher energy costs lift inflation breakevens, delaying rate-cut expectations and pressuring the long-duration technology cohort that has carried index concentration. That creates a near-term regime in which equal-weight equities and smaller cyclicals may underperform the cap-weighted index initially, while XLE offers a cleaner hedge only if crude strength reflects physical tightness rather than a short-lived geopolitical premium.
The apparent valuation cushion is fragile because aggregate forward multiples obscure concentration: a de-rating in the largest AI-linked names can outweigh broad earnings resilience. For the next 1-3 months, the key falsifier of a correction thesis is declining 10-year Treasury yields alongside stable high-yield spreads; that combination would restore duration appetite and likely force index hedges to cover. Conversely, a sustained rise in oil accompanied by widening HY spreads, rather than merely higher nominal yields, would signal genuine financial-conditions tightening and raise the probability of a deeper beta unwind.
Consensus may be too quick to translate persistent passive inflows into durable buying power. Flows mechanically support the largest constituents during risk-on periods, but they also make SPY/VOO a concentrated duration-and-mega-cap exposure; redemption or de-risking pressure would be transmitted to the same names. MS is more exposed to a broad risk-asset correction through investment-banking activity, wealth-management fee assets, and market-sensitive revenues than to the direction of rates alone; it is a better cyclical-risk proxy than a pure financials long if volatility rises.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mixed
Sentiment Score
-0.12
Ticker Sentiment
Key Decisions for Investors
- Use a 4-8 week tactical hedge rather than outright SPY short: buy SPY put spreads approximately 4-7% out of the money, financed by selling puts another 5-7% lower. Enter only if 10-year yields rise and HY spreads widen simultaneously for several sessions; target a 2-3x payoff on premium, and exit if yields retreat materially while spreads remain contained.
- Pair long XLE versus short SPY over the next 1-3 months only if WTI holds above its 50-day moving average and energy-sector EPS revisions turn positive. Size for a 5-8% relative move; stop the pair if crude falls below its 50-day average or OPEC supply guidance materially increases.
- Reduce incremental exposure to MU and SNDK into any bond-volatility spike. Semiconductor demand narratives can remain intact while their high-duration multiples compress; re-engage only after long-end yields stabilize and memory pricing data confirm that earnings revisions, not multiple expansion, are driving returns.
- Underweight MS versus XLF for a 1-3 month risk-off window if equity volatility rises and credit spreads widen. The thesis is falsified by resilient capital-markets activity and continued net new assets that offset market-sensitive fee pressure; cover on a sustained tightening in HY spreads.
- Do not treat NVO or VOW3 weakness as a direct macro hedge. Their nearer catalysts are company-specific execution, reimbursement, and auto-cycle risks; wait for earnings revisions or guidance changes before initiating directional positions.
More News
- Volkswagen woes deepen as blue-chip index exit follows latest profit warning
- Novo stock falls as much as 7% despite $23 billion sales target for blockbuster obesity drugs
- Volkswagen, Porsche shares extend losses following profit warning
- Stifel cuts Nike stock price target on margin, demand concerns
- Novo Nordisk stock tumbles as Ozempic maker sets out 2030 goals
- Porsche could face another 4,000 job cuts, Handelsblatt reports