
Crooked Pop Names Lee Schill Chief Commercial Officer
Source: PR Newswire
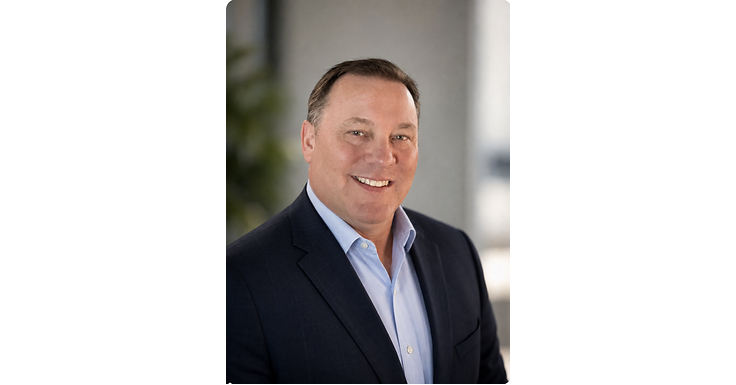
Crooked Pop, a USDA-certified organic, zero-sugar, gluten-free hard soda brand, appointed Lee Schill as Chief Commercial Officer to drive national retail, distributor, and on-premise expansion. The company is scaling after launching on the East Coast in April, signing a distribution deal with Reyes Beverage Group and securing first-mover in-stadium partnerships (e.g., Philadelphia Phillies, Atlanta Braves, Tampa Bay Buccaneers). While no financial guidance was provided, the leadership hire plus new distribution and venue deals modestly improve prospects for revenue growth.
Analysis
This reads more like a distribution credibility signal than a true demand inflection. In beverage, the commercial hire matters only if it translates into higher velocity per door without a step-up in trade spend; otherwise it is just expensive shelf acquisition. For public markets, the near-term impact on DEO, BATRK, or WWRL is essentially zero, but it does raise the odds of another small RTD challenger competing for finite retailer attention and wholesaler bandwidth.
The bigger second-order effect is on shelf-space economics: if this brand gets real national pull, the losers are the smaller zero-sugar and hard-seltzer names that already fight for resets and display support. That pressure would likely show up first in weaker incremental distribution for crowded beverage subcategories, not in top-line damage to large incumbents. Over 1-3 months, the key tell is whether third-party scans and distributor commentary confirm repeat purchase; over 6-18 months, the issue becomes whether this is a durable franchise or another capital-intensive SKU fight.
Contrarian view: the market tends to overvalue a polished operator add and underweight consumer repeat rates. The falsifier is simple: if velocity stalls after the initial retail rollout, the brand will have to buy growth through promo, and that is usually margin-destructive rather than category-creating. In that case, the broader read-through is bearish for late-stage beverage growth stories, but not enough on its own to justify a large public-market position today.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.12
Key Decisions for Investors
- No immediate trade in DEO/BATRK/WWRL; treat this as a watch item until there is third-party scan data or distributor-depletion evidence that the product has real velocity.
- If SAM rallies on any sympathy around RTD/innovation breadth, use it to initiate a small short over 3-6 months; thesis fails if SAM shows sustained scanner acceleration or raises guidance on gross margin/shipments.
- Consider a defensive pair: long DEO / short SAM on any beverage-sector strength, favoring the larger incumbent’s resilience over the higher-multiple challenger if shelf-space competition intensifies.
- Set an alert for any new national wholesaler signings or capital raise from Crooked; that would be the first real signal that shelf-space competition is becoming material for adjacent RTD names.
More News
- Pernod Ricard first quarter sales fall less-than-expected, cautious optimism on China
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- Penske Automotive agrees to be taken private by Penske, Mitsui
- Supermicro promised a new CFO in December 2024. A $2.5 billion smuggling case and a co-founder’s arrest later, it has one
- Blackstone President Jon Gray Bets Big on AI Boom
- What's behind the sell-off in AI neocloud stocks like CoreWeave and Nebius