
Xinhua Silk Road: From temple visit to island getaway: Fujian's Meizhou Island expands tourism appeal
Source: PR Newswire
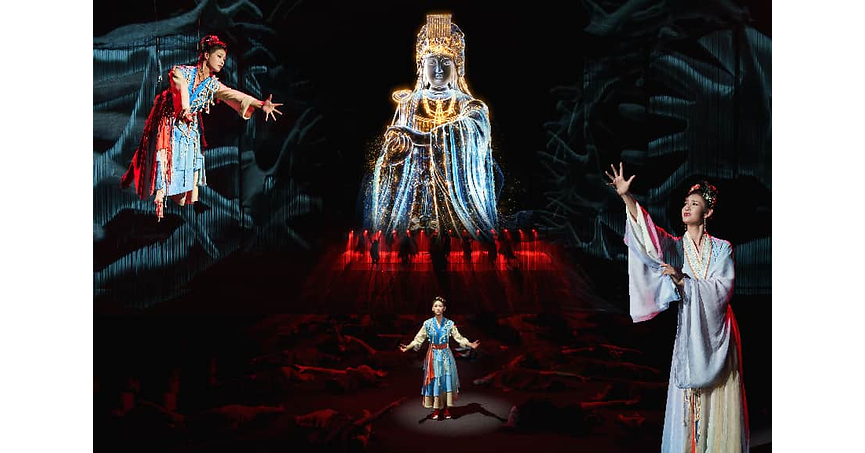
Meizhou Island received approximately 3.23 million tourist visits in 2025, surpassing 3 million for the first time as it broadened its Mazu heritage offering into a multiday vacation destination. The island is targeting longer stays and wider visitor segments—including families, self-driving travelers and younger tourists—through cultural activities, live performances, museums and nighttime events. The development indicates improving local tourism demand, but is unlikely to have material broader market implications.
Analysis
This is not independently investable information: it is destination-promotion content without disclosed visitor spending, hotel occupancy, room supply, transport capacity, or listed corporate beneficiaries. The reported shift toward longer stays would matter only if it lifts revenue per visitor faster than the island’s incremental lodging, ferry, and entertainment capacity; otherwise it primarily redistributes tourism spend from nearby Fujian destinations rather than expanding regional leisure demand.
For China travel proxies, the more relevant read-through is modest support for domestic experiential tourism and family travel, not a material earnings catalyst. Ctrip/Trip.com (TCOM) could benefit at the margin from higher package and accommodation booking mix, while China Tourism Group Duty Free (1880 HK) has no direct linkage absent evidence that overnight visitors convert into higher-duty-free travel flows. Local operators are likely privately held or state-affiliated, limiting clean public-market transmission.
The contrarian view is that destination publicity can create a short-lived social-media demand spike but rarely sustains pricing power. A weaker consumer backdrop, ferry/weather disruptions, or aggressive hotel supply additions would quickly erode any length-of-stay gains; the key validation metric is paid overnight stays and RevPAR through the next holiday periods, not gross visitor counts. No standalone trade is warranted on this release.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.32
Key Decisions for Investors
- No new position based on this item; treat it as a low-signal monitor for China domestic-travel demand rather than a company-specific catalyst.
- For existing TCOM exposure, monitor National Day and Lunar New Year booking data for Fujian/coastal short-haul packages, accommodation take-rate, and hotel ADR. Consider adding only if domestic lodging bookings and management guidance demonstrate broad-based acceleration, not isolated destination traffic.
- Avoid using 1880 HK or broad China consumer ETFs as a proxy for this theme without evidence of incremental retail conversion; the causal link from local pilgrimage tourism to duty-free spending is weak.
- Set a watch trigger for disclosed overnight-stay growth and RevPAR materially exceeding visitor growth over the next 6-12 months. That would indicate monetizable destination deepening rather than volume-led, low-yield tourism.
More News
- Exclusive-How firms linked to sanctioned Chinese cotton giant sell clothes to U.S
- Costco makes progress on a key membership metric. Here's our new price target on the stock
- Why we like Starbucks’ latest turnaround move — plus, two more wins for Eli Lilly
- New York sues Polymarket over allegations of illegal gambling operations
- Argentina’s poverty rises to 32 percent under Milei with more pain forecast
- New York sues Polymarket U.S., two months after filing lawsuit against Kalshi