
Shure Named a Leader in the 2026 IDC MarketScape for AI-Enabled Smart Conference Room Hardware for Hybrid Meetings
Source: PR Newswire
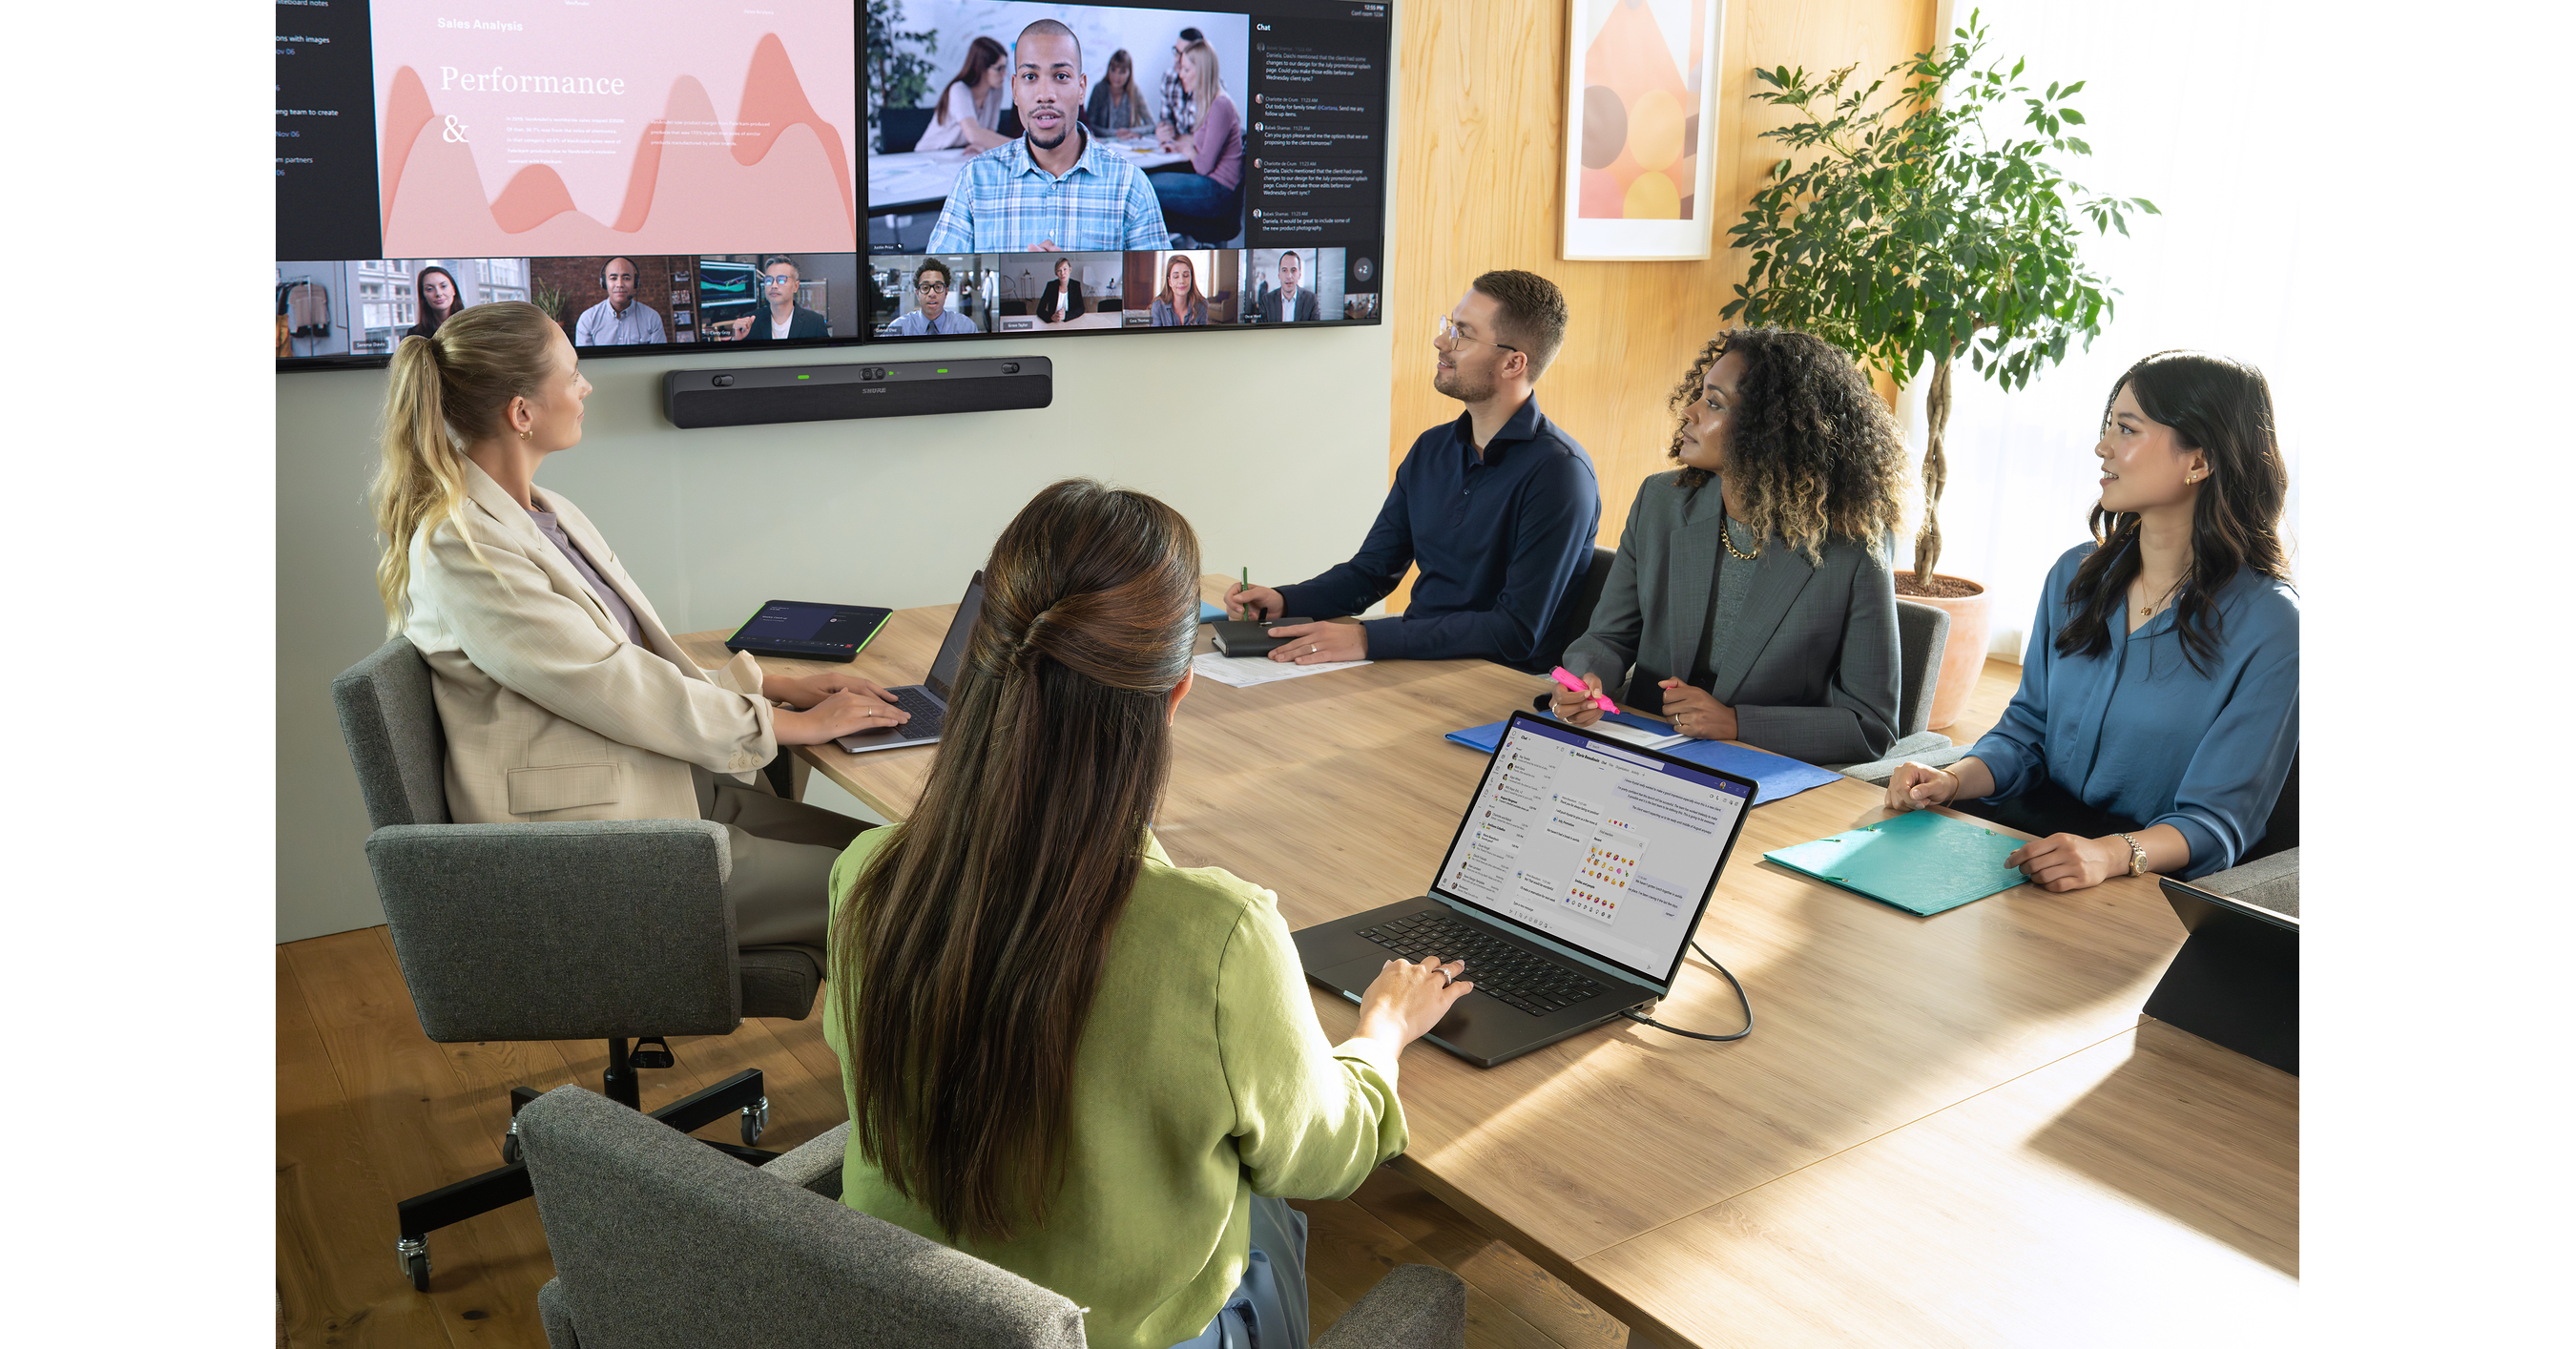
Shure was named a Leader in IDC’s 2026 assessment of AI-enabled smart conference-room hardware for hybrid meetings. IDC cited its capabilities in challenging audio environments, platform integrations, camera tracking data and device-level management; Shure also said warranty coverage is available for up to five years. The announcement highlights product positioning but provides no sales, earnings or market-reaction figures.
Analysis
This is a modest competitive signal, not an earnings catalyst: Shure is privately held, and the announcement provides no sales, share, or order data. IDC recognition may help Shure in enterprise procurement—especially complex rooms where audio performance is a gating requirement—but the more consequential point is that its hardware works across Teams, Zoom, Google Meet, and Webex. That supports a more modular buying model and could pressure vendors whose room-hardware differentiation depends on tying customers to a single collaboration stack. Potential pressure is concentrated in room endpoints and deployments, not necessarily in the recurring software economics of Microsoft, Zoom, Alphabet, or Cisco. Better audio can improve transcription and speaker attribution, but value capture remains uncertain: collaboration platforms control much of the AI workflow and may treat higher-quality inputs as table stakes rather than a paid upgrade.
Over the next 1–3 months, watch for independent evidence—large deployment wins, channel/integrator commentary, or competitor product and pricing responses. Over 6–18 months, broader adoption of cross-platform room systems could intensify hardware competition while increasing demand for device-management tools. The contrarian read is that a vendor-sponsored release amplifies a research accolade without proving changed buyer behavior; the market may overread it as evidence of material share gains. Thesis weakens if procurement remains platform-led, competitors match audio and management capabilities, or Shure fails to convert recognition into disclosed deployments. No direct equity exposure to Shure is identified in the supplied mapping.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Key Decisions for Investors
- No immediate trade in CSCO, MSFT, GOOG, or ZM: the announcement does not establish a material revenue or margin change for any mapped company.
- Add cross-platform conference-room hardware to diligence for Cisco and other endpoint vendors; treat Shure’s recognition as a competitive watch item, not proof of share loss. Seek deployment, pricing, and channel evidence before positioning.
- Monitor Microsoft Teams and Zoom room-device attach rates and any changes in hardware bundling or partner strategy over the next 1–3 months; broader third-party hardware choice could shift endpoint economics without displacing the collaboration software layer.
- Revisit the view if independent procurement data or company disclosures show sustained Shure wins in large enterprise estates, or if Cisco and other hardware vendors respond with pricing concessions or materially upgraded audio/device-management features.
More News
- From Wall Street to Silicon Valley, Anthropic IPO poised to have massive 'trickle-down effect'
- A shock in Brazil sends stocks plunging, while neoclouds take another hit
- Microsoft offers buyouts to nearly 30% of workforce in ongoing AI shift
- Anthropic’s risk factors include the end of humanity, a feud with the Pentagon, and CEO Dario Amodei’s reputation
- Elon Musk warns more than 200 AI cloud companies face ‘guppy-level death’ as the AI boom runs into a debt crisis
- Anthropic’s IPO filing shows explosive growth, risks and staggering costs