
Certus' Newest Partnership Expands its Foothold in Greater Seattle Area
Source: PRWeb
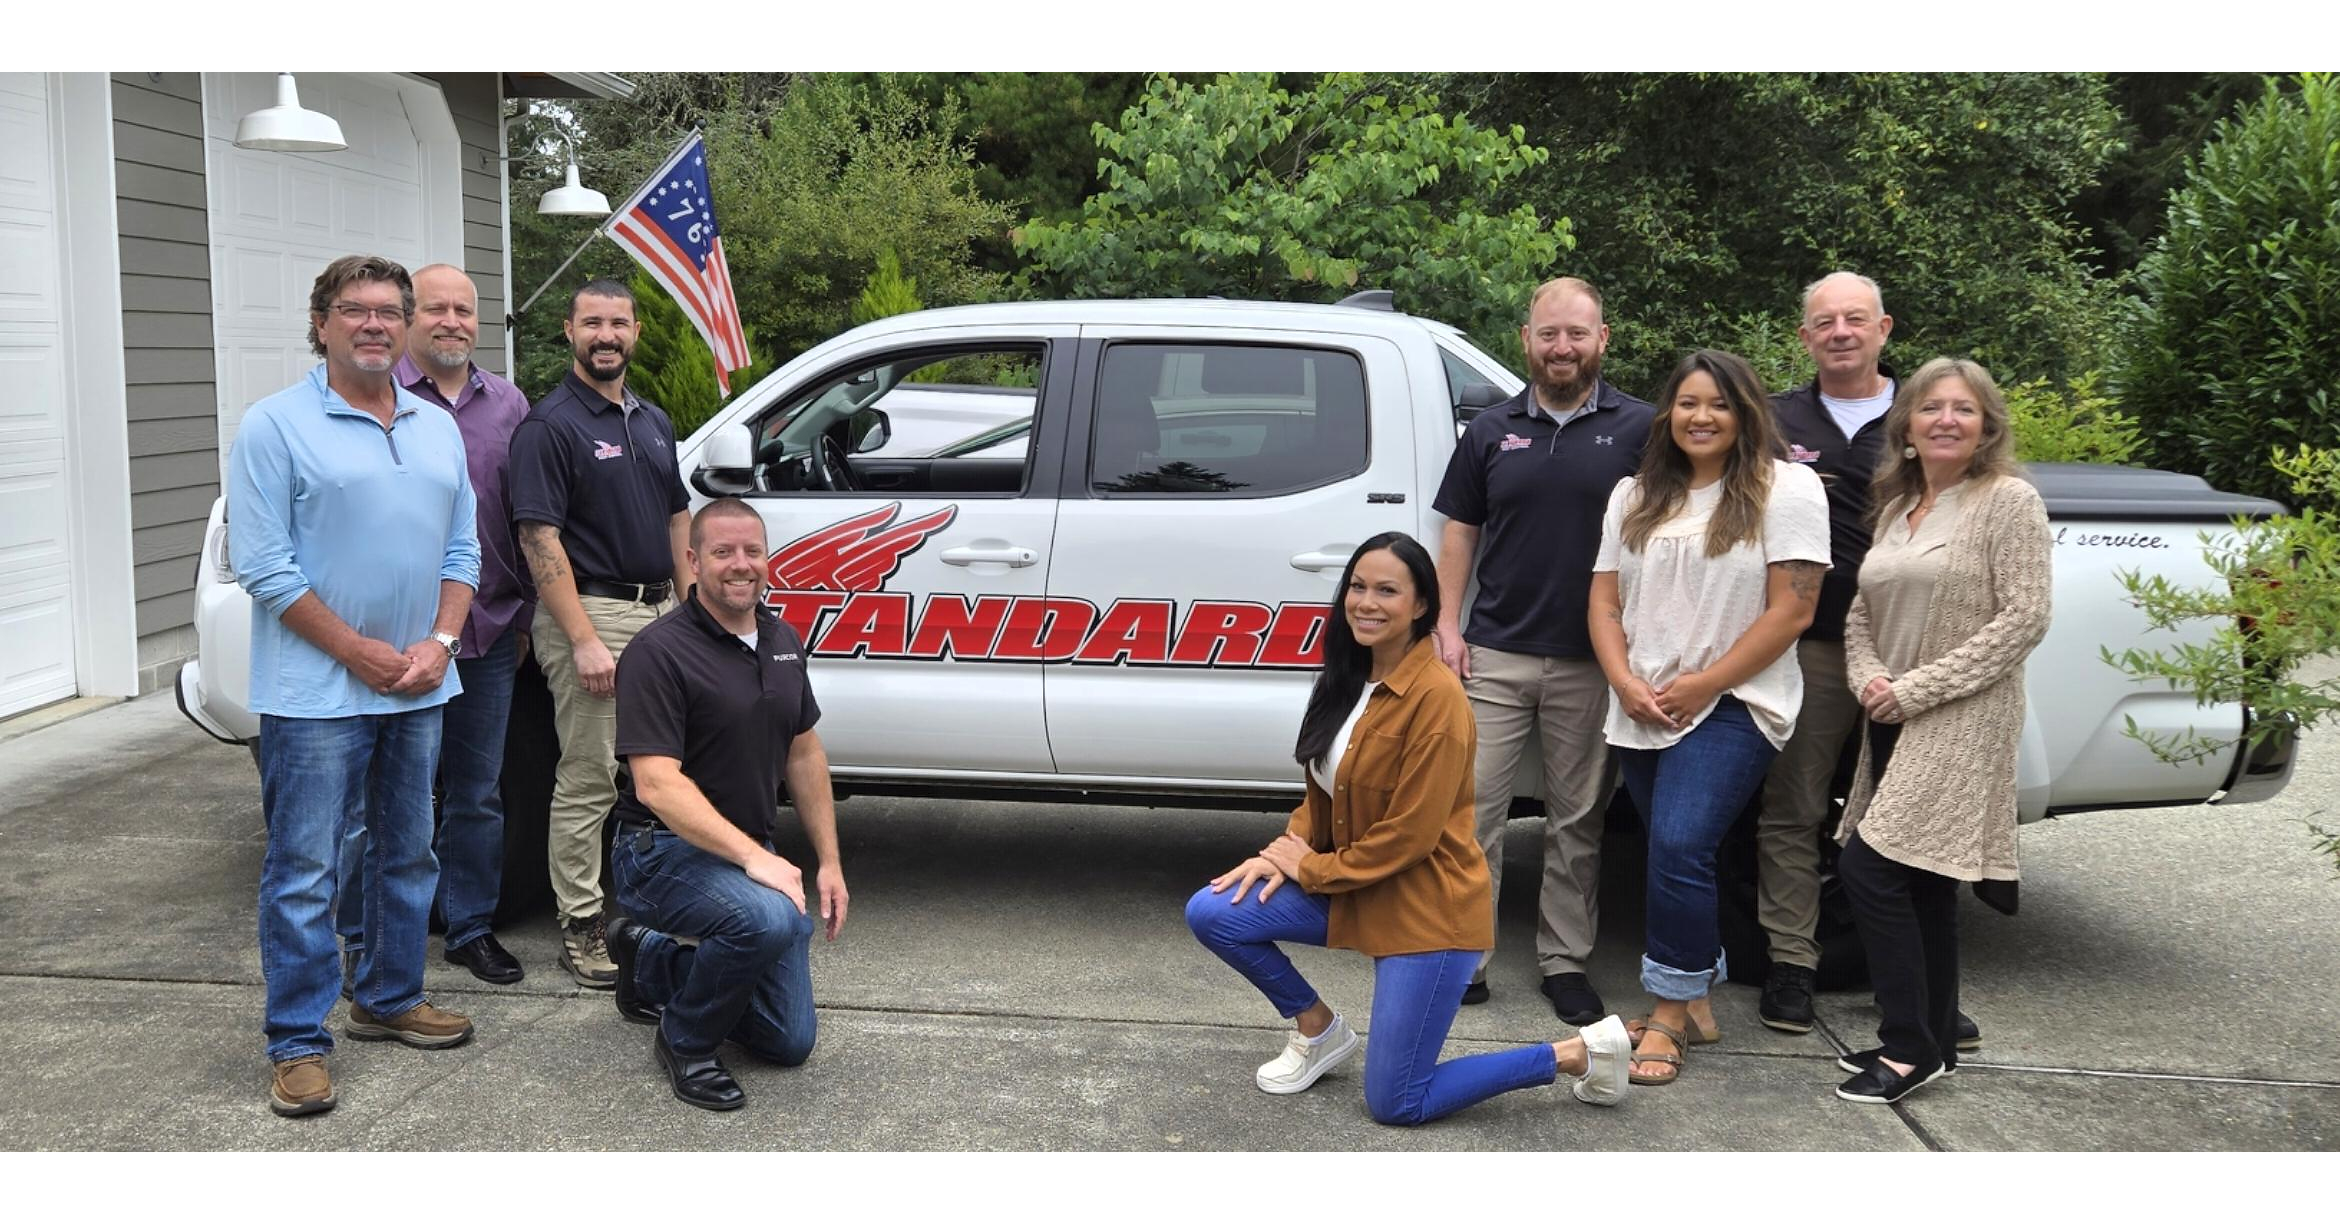
CERTUS partnered with Puyallup, Washington-based Standard Pest Control, expanding its Greater Seattle pest-control footprint through integration with its PURCOR Pest Solutions brand. The transaction targets a Seattle-area market of more than 4 million residents and is expected to provide Standard customers with broader services and operational resources. Financial terms and expected revenue contribution were not disclosed.
Analysis
This is a private, bolt-on transaction with no disclosed consideration, customer count, or EBITDA contribution, so it is not independently investable today. The more relevant read-through is that scaled consolidators continue to value dense metropolitan service routes: higher technician utilization and lower drive-time can lift branch margins materially, while recurring contracts provide durable revenue visibility. That favors national platforms with acquisition capacity over standalone local operators, but the incremental impact on any public peer is immaterial absent evidence of accelerating deal multiples.
The second-order constraint is labor, not demand. Seattle-area wage pressure, technician retention costs, and integration execution can absorb much of the theoretical density benefit, particularly if acquired customers churn following price harmonization or changes in local service personnel. A fragmented-market roll-up model also becomes less attractive if financing costs remain elevated: acquisition valuations may stay sticky while buyers' cost of capital rises, delaying margin and cash-on-cash accretion.
Over the next 1-3 months, this should not move public pest-control exposures. Over 6-18 months, monitor whether private consolidators' activity begins to tighten supply of independent acquisition targets; that would raise replacement costs for Rollins (ROL) and ServiceMaster/Terminix owner Rentokil Initial (RTO), potentially pressuring returns on M&A. The contrarian view is that industry consolidation is often interpreted as uniformly bullish for incumbents, but late-cycle tuck-ins can signal a scarcity of organic growth opportunities and create integration-heavy, lower-return capital deployment.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.32
Key Decisions for Investors
- No standalone trade on this announcement; treat as a low-signal private-company press release until purchase price, acquired revenue, retention, and financing terms are available.
- Maintain ROL as the cleaner public quality compounder watchlist exposure rather than chasing M&A narratives: initiate only on a valuation reset or evidence that organic residential growth and pricing remain above labor-cost inflation over the next two earnings reports.
- Monitor RTO's North American margin trajectory over the next 2-4 quarters. A failure to show sequential integration improvement or customer-retention progress would support a relative short RTO versus long ROL, as RTO carries greater execution sensitivity from prior large-scale consolidation.
- Set an industry alert for disclosed pest-control transaction multiples above roughly 12x EBITDA or a material rise in technician wages; either would weaken the expected return on consolidator-led roll-ups and challenge the bullish consolidation read-through.
More News
- Japan’s corporate leaders sound alarm over weak yen — even dollar-earners are voicing concerns
- Fed hikes again - an AI-Picked insurer is still cashing in
- Berkshire May Boost Japan Trading House Holdings, Itochu Says
- Fed delivers its first hike in 3 years. Plus, what's moving Starbucks and GE Vernova
- Berkshire may boost holdings in Japan’s trading houses- Bloomberg
- The Competition's Response to Tesla Robotaxi Day
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AlphaSense Pricing: What Public Contract Data Shows in 2026
- Eli Lilly Q4 2025 Earnings: Revenue Surges 43% as Mounjaro and Zepbound Dominate the GLP-1 Market