
JA geht mit integrierten Solar-Plus-Speicher-Lösungen auf Europatour
Source: PR Newswire
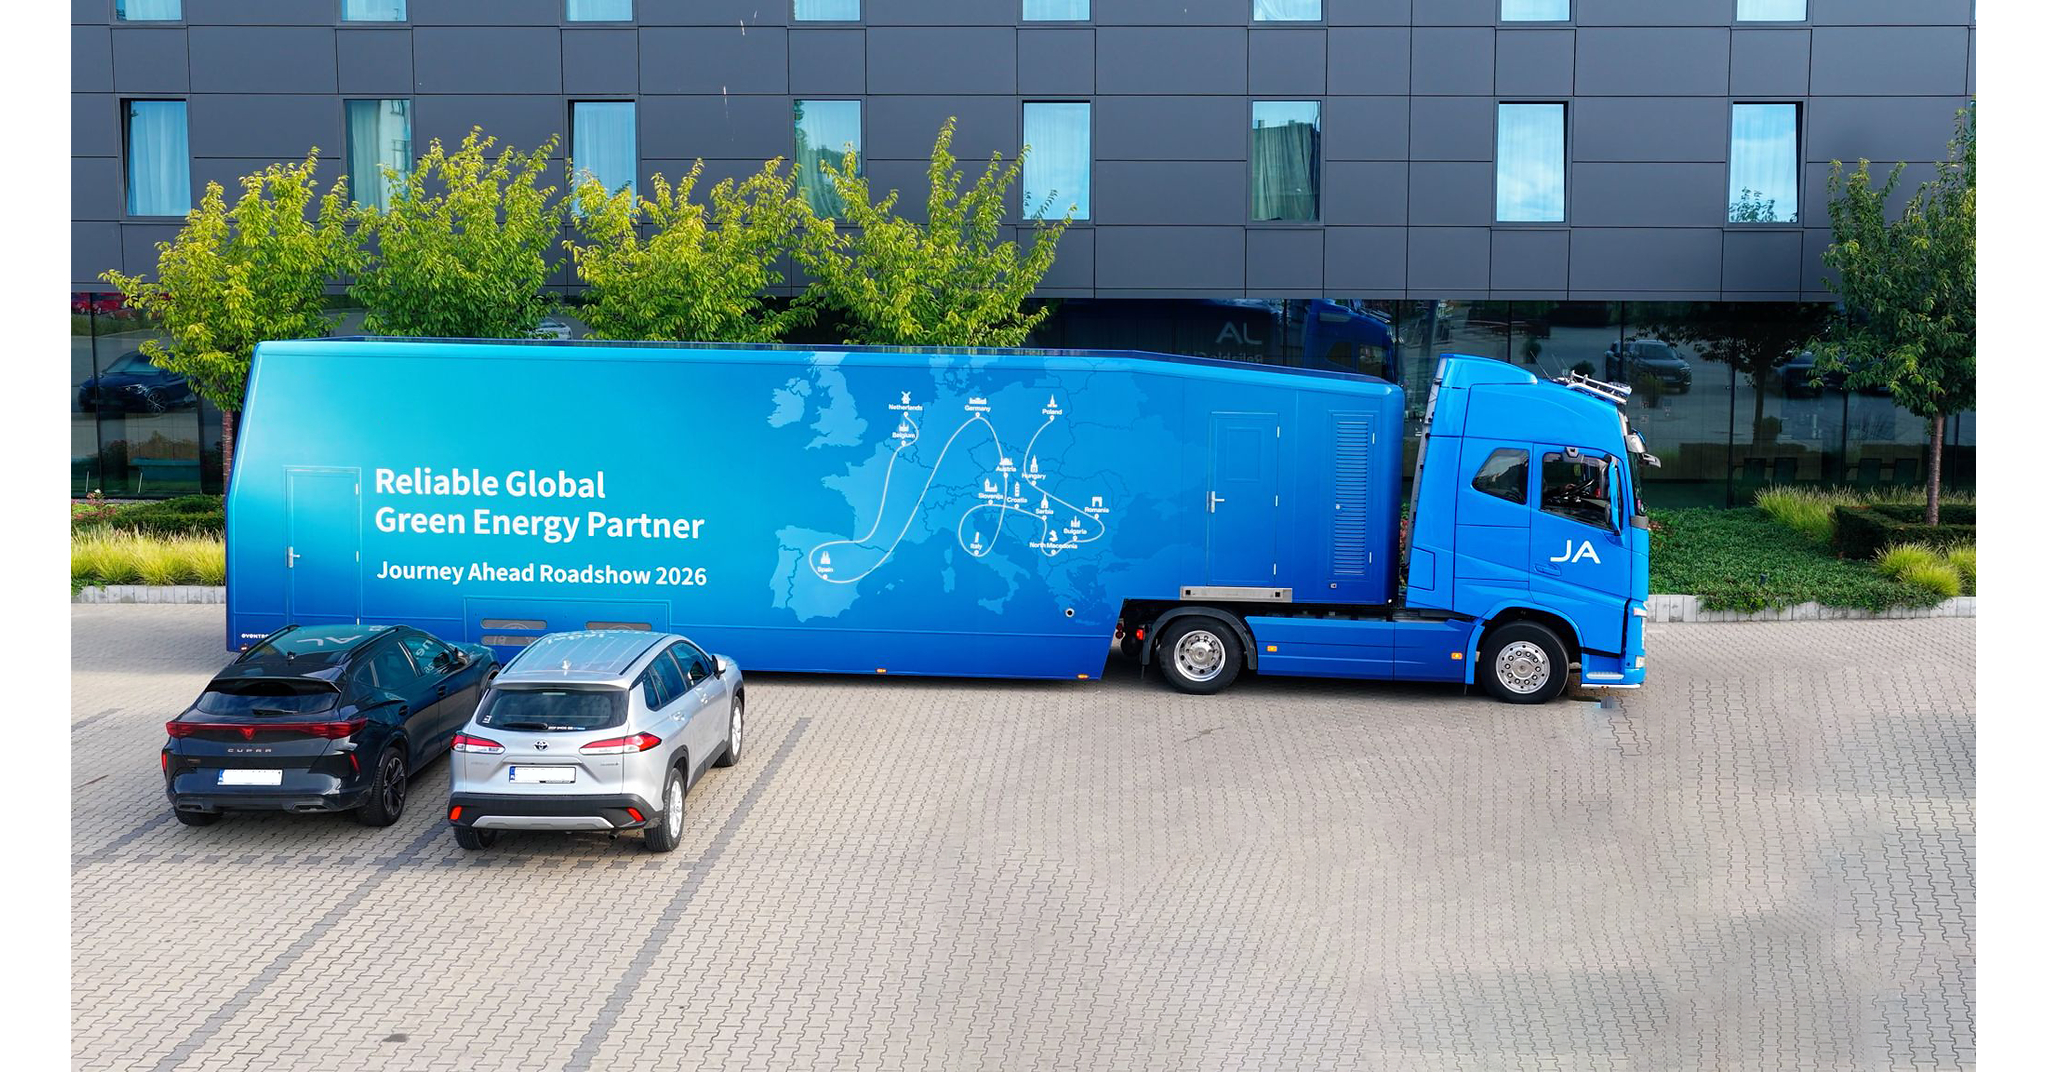
JA startet seine erste europäische Roadshow „Journey Ahead: JA Roadshow 2026“ mit Start in Polen und will in den nächsten 8 Wochen mehr als 20 Standorte in 11 Ländern abdecken. Im Fokus stehen integrierte Solar-plus-Speicherlösungen (u. a. JAPlanet Fusion/2.0 und JAGalaxy) sowie PV-Modelle auf TOPCon-Basis wie DeepBlue 5.0/4.0 Pro; das HyperGen-Modul erreicht eine zertifizierte Zellumwandlungseffizienz von 28,2%. Die Nachricht ist operativ und marktbezogen positiv, dürfte aber kurzfristig nur begrenzt Kursbewegungen auslösen.
Analysis
This reads more like a channel-expansion signal than a revenue event. The market mechanism is margin pressure: if a Chinese supplier can package modules plus storage plus local deployment support for Europe, the competitive battleground shifts from pure panel efficiency to bundled economics, financing, and service. That tends to squeeze commodity module ASPs first, then move upstream into inverters, ESS enclosures, and EPC pricing over the next 1-3 quarters.
The second-order winner is not necessarily the name in the release, but any vendor with a real European service footprint, bankability, and software/control stack. That argues for relative resilience in non-China, compliance-heavy vendors and for weaker pricing power among broad solar beta names. C&I and data-center storage are the more interesting lanes because they monetize uptime and grid-avoidance value, not just kWh, so the competitive impact there shows up in win-rates and gross margin before it shows up in shipment growth.
Near term, the roadshow itself is not a catalyst; signed distributor agreements, tender shortlists, or disclosed project wins are. The thesis breaks if Europe hardens procurement rules around local content/data residency faster than expected, or if falling rates and power prices reduce the urgency of behind-the-meter storage. Over 6-18 months, though, integrated solar-plus-storage should keep taking share in Europe as customers optimize self-consumption and resiliency rather than just install PV capacity.
Contrarian view: the consensus may overrate how immediately bankable a touring sales push is. European buyers care about warranty depth, local O&M, and financing partners more than product brochures, so the actual conversion rate may be low unless JA can prove project references. If the market is already pricing a storage adoption boom, the better trade may be to short the crowded solar-beta basket rather than chase the specific company story.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.18
Key Decisions for Investors
- No immediate long in the headline name; treat this as a watch item until there is evidence of signed European project awards or distributor contracts over the next 1-3 months.
- Short TAN on rallies / sell solar-beta strength over the next 1-4 weeks if module pricing weakens further; the risk/reward is favorable because the headline adds competition without creating incremental demand.
- Pair trade: long FSLR vs short TAN for 1-3 months. FSLR is structurally less exposed to Chinese pricing pressure and should hold up better if Europe becomes more promotional on bundled PV+storage offers. Falsify if broader solar ASPs stabilize and TAN outperforms on actual demand data.
- Watch FLNC and other grid/storage integrators for confirmation of European C&I and data-center pipeline growth; only add on a pullback if order intake or backlog conversion improves into the next two earnings cycles.
- If European regulators tighten data-residency/local-content requirements, rotate toward domestic-service and software-heavy names rather than module manufacturers; otherwise, expect continued margin compression in commoditized solar supply chains.
More News
- Indonesian stocks plunge to six-year low as MSCI downgrade fears mount
- Putin reportedly suggests summit with Trump and Xi to decide fate of Ukraine
- Ukraine launches over 1,000 drones at Russia, setting oil facilities ablaze
- China's CXMT sees shares drop over 6% as investors look past chipmaker's profit turnaround
- Trump defends Russian sanctions relief, lashes out at Zelenskyy
- China’s Coal Output Drops as Concerns Build Over Winter Supply