
Nobu Announces Nobu Hotel and Restaurant San Juan, Marking Its Debut in Puerto Rico
Source: PR Newswire
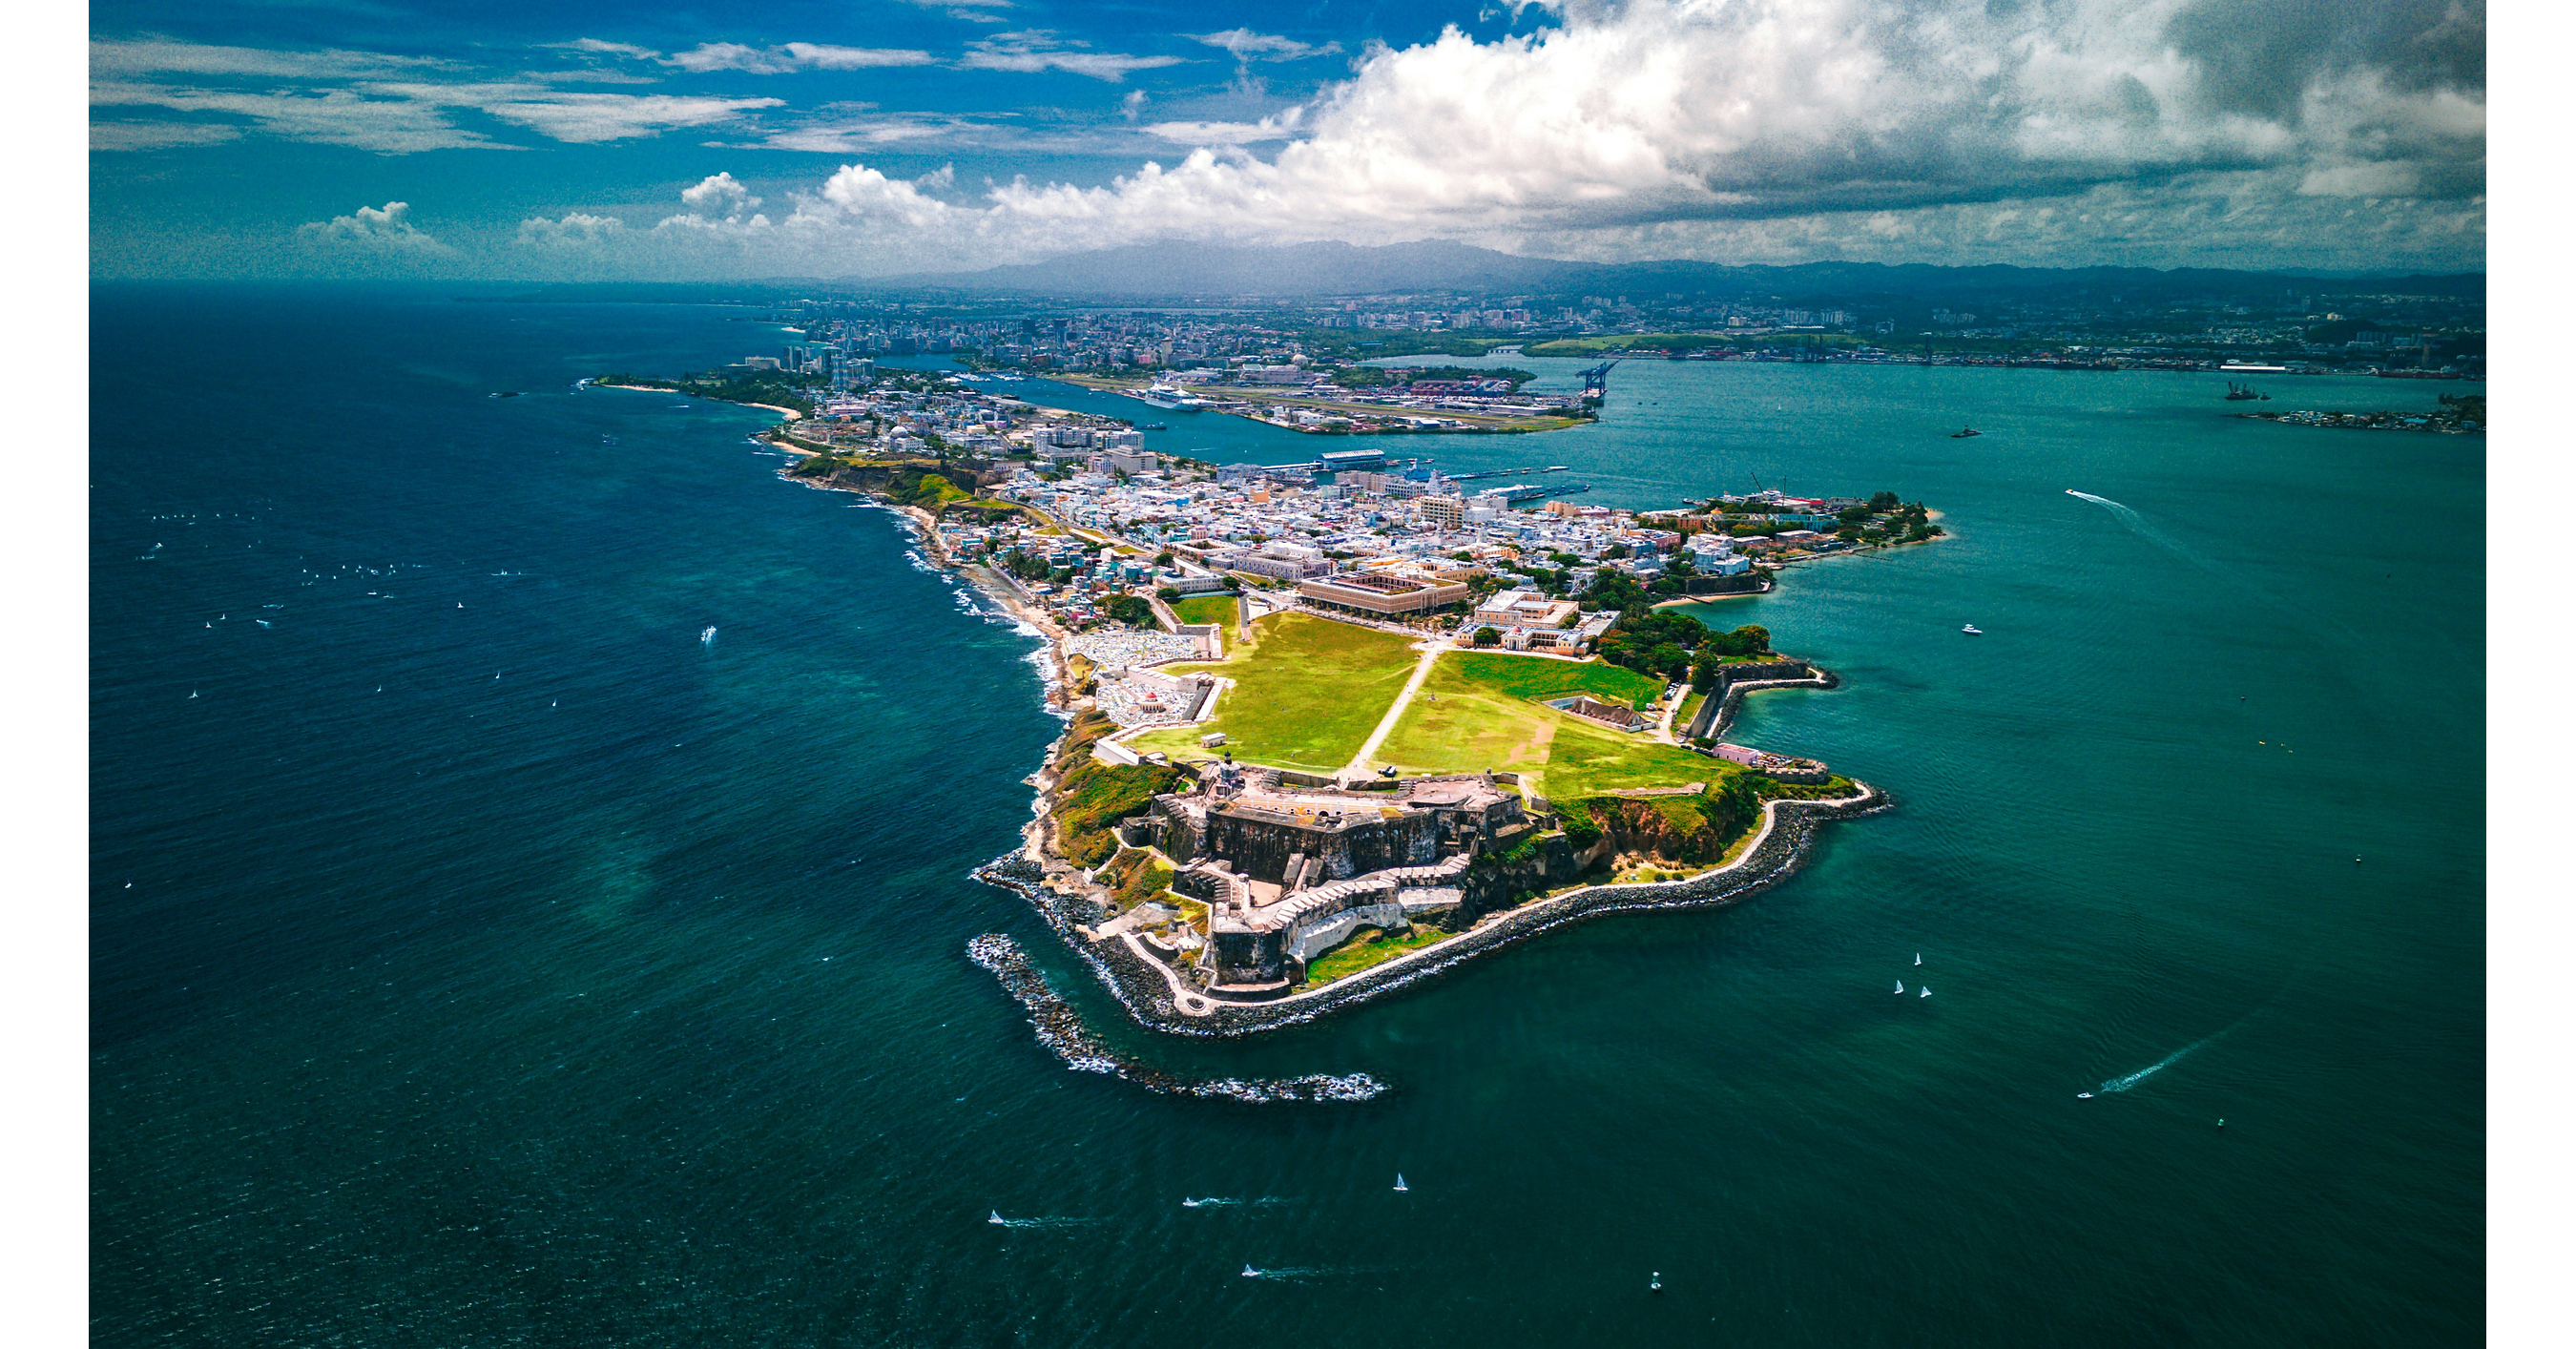
Nobu Hospitality announced its first Puerto Rico venture, a 50-room Nobu Hotel and Restaurant in San Juan scheduled to open in 2028. The luxury property will include a street-level Nobu restaurant and bar plus a rooftop lounge, expanding the brand's Caribbean hospitality footprint. The announcement supports San Juan's positioning as an upscale travel destination, though no investment value or expected financial contribution was disclosed.
Analysis
This is not investable as a standalone catalyst: the asset is small, privately developed, and its earnings contribution will not be visible before 2028. The more relevant read-through is that branded luxury operators continue to favor management/franchise-style expansion in supply-constrained leisure destinations, where fee income can scale without meaningful balance-sheet deployment. Public lodging REITs with Caribbean exposure should not be re-rated on this announcement absent evidence that the project is driving broader room-rate growth or comparable redevelopment activity.
The competitive effect is localized rather than sector-wide. A high-end food-and-beverage anchor can lift nearby luxury ADRs and retail traffic, but it can also redirect affluent spend away from independent Old San Juan restaurants and smaller boutique hotels; this is largely private-market exposure. For public proxies, the signal is modestly constructive for Marriott (MAR) and Hilton (HLT) only insofar as branded supply validates sustained premium leisure demand, but incremental supply ultimately limits upside if regional demand normalizes by opening.
Over the next 1-3 months, watch Puerto Rico airlift, luxury hotel occupancy/ADR, and redevelopment financing rather than the press release itself. The 6-18 month risk is that construction inflation, permitting delays, or a weakening U.S. high-income consumer pushes opening economics below underwriting assumptions; a 2028 launch leaves substantial macro-cycle exposure. Consensus should resist treating another brand entry as proof of durable destination pricing power: new luxury inventory can expand the market, but it more often first raises customer-acquisition and labor costs for incumbents.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Key Decisions for Investors
- No standalone position: the announcement lacks a listed issuer, disclosed project economics, and a near-term earnings catalyst.
- Maintain MAR and HLT on a watchlist rather than buying on this news; upgrade only if quarterly commentary shows Caribbean RevPAR and group/leisure booking pace accelerating while net unit growth remains fee-accretive. Falsifier: regional RevPAR decelerates for two consecutive quarters or development pipelines materially raise supply.
- For lodging exposure, prefer an asset-light pair of long MAR or HLT versus short a higher-leverage hotel-owner basket only if financing spreads widen and luxury construction costs reaccelerate; the mechanism is management-fee resilience versus owner margin/capex pressure. Reassess if long-duration rates decline materially or hotel transaction volumes recover.
More News
- In photos: China's Xi hardens Taiwan warning as country celebrates week-long National Day holiday
- China’s Property Crisis: From Evergrande Collapse to Beijing’s Latest Measures
- Google rolls out Gemini 4 Argon, its most advanced AI model
- Meta stock enjoys best month since 2022 on AI momentum
- Huawei unveils Mate 90 phones, leans on homegrown chip design to offset US curbs
- Bloomberg Tech: OpenAI Seeks $30B as Trump Backs Safety Audits