
Eightco Holdings (NASDAQ: ORBS) comunica attività complessive per circa 380 milioni di dollari, comprendenti partecipazioni in OpenAI e Beast Industries, oltre 16.000 ETH e quasi 302 milioni di token WLD
Source: PR Newswire
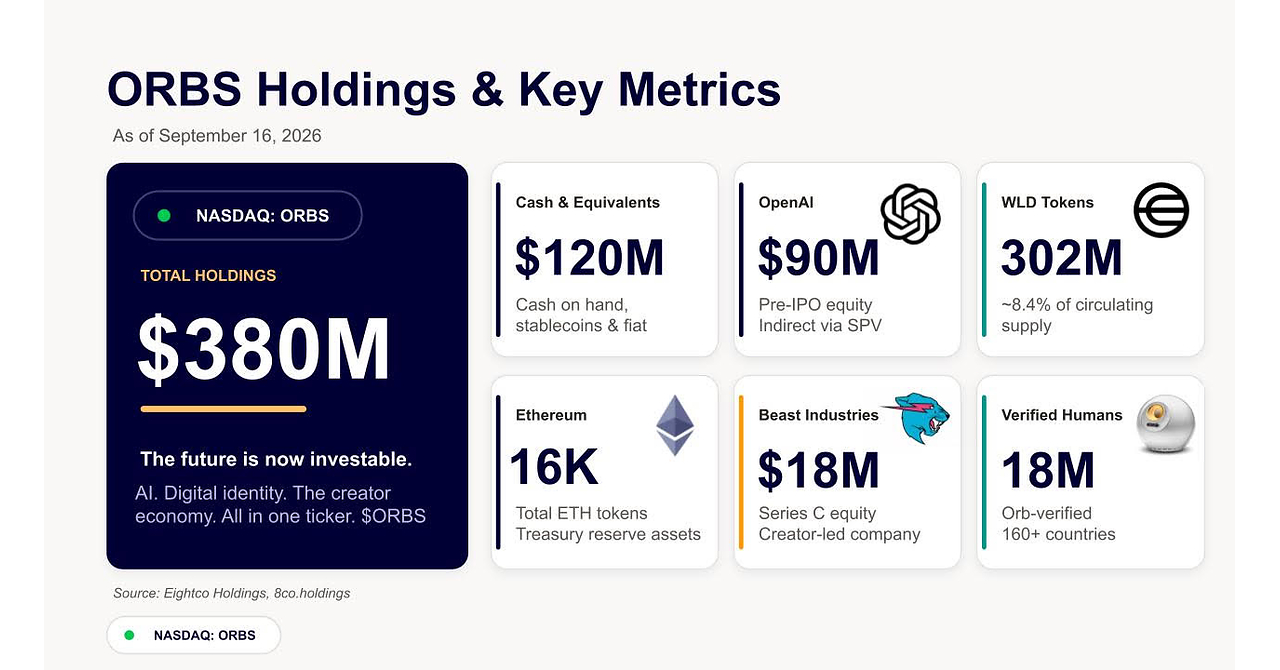
Eightco reported approximately $380 million of treasury assets as of September 16, including a $90 million indirect OpenAI stake, $18 million in Beast Industries, 16,278 ETH, 301.97 million WLD tokens and roughly $120 million in cash and stablecoins. Its WLD position represents about 8.4% of circulating supply and 29% of treasury assets, while OpenAI accounts for 24%. The company also repurchased more than 26 million common shares during the quarter under its previously announced $125 million buyback program, reinforcing its strategy to provide public-market exposure to AI, digital identity and the creator economy.
Analysis
ORBS should trade less like an operating company and more like a highly levered, closed-end vehicle whose discount/premium is determined by the liquidity and realizability of three very different assets. The critical valuation issue is not the stated treasury value but the haircut required for an SPV-held private-company interest, a concentrated WLD stake with potential market-impact constraints, and any stablecoin/cash balance subject to reconciliation after repurchases. A material mismatch between independently marked NAV and equity value would be more actionable than the promotional narrative around AI or creator economics.
Near term, buybacks can tighten float and amplify upside in a thinly traded equity, but they also reduce the cash buffer that distinguishes ORBS from a pure token proxy. The dominant fundamental sensitivity is WLD: a 20% move in WLD would likely have a larger NAV effect than incremental developments at the private holdings, while the public stock can move by multiples of that sensitivity if the NAV discount changes. The stated concentration also creates a reflexive risk: a falling token price widens the equity discount, limiting the company's ability to use stock as acquisition or financing currency.
Over 1-3 months, the catalyst is audited or filing-level disclosure that clarifies share count, cost basis, lockups, transfer restrictions, SPV economics, and post-buyback cash. Over 6-18 months, the upside case requires monetizable protocol adoption rather than token appreciation alone; regulatory restrictions on biometric identity or token unlock/supply pressure would impair both adoption and valuation. Consensus appears to be treating indirect OpenAI exposure as liquid public-market optionality; it is more likely a long-duration, non-mark-to-market asset that deserves a steep discount until a credible liquidity path is disclosed.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.48
Ticker Sentiment
Key Decisions for Investors
- Maintain ORBS as watchlist-only until a fully diluted share count and independently reproducible NAV bridge are available. Initiate a small long only if ORBS trades at a greater than 35% discount to a conservative NAV that applies at least a 40% haircut to the SPV/private holdings and a liquidity haircut to WLD; target discount compression to 15-20% over 1-3 months.
- If long ORBS, hedge the dominant liquid beta with ETH or a crypto-equity proxy rather than treating the position as an AI investment. Size the hedge after establishing actual WLD/ETH NAV weights; the missing WLD borrow/derivatives liquidity prevents recommending a direct WLD short at present.
- Use the next SEC filing as a binary diligence catalyst: exit or avoid ORBS if cash plus disclosed liquid assets do not reconcile with reported repurchases and treasury marks, or if transfer/lockup terms materially limit WLD or SPV monetization. Those disclosures would invalidate the discount-to-NAV thesis.
- Do not extend the ORBS thesis to COIN, NDAQ, or BMNR. Their earnings sensitivity to ORBS's treasury strategy is immaterial; BMNR is only a sentiment read-through and not a fundamental beneficiary.
More News
- Tokenization is set to change stock trading. These stocks could get a boost
- The Dow Is Down for a Third Straight Week and the Nasdaq Is Somehow Up
- Sportsbooks remain king this football season, but upstarts are making a run for the money
- Netflix Stock Gets Downgraded by Wells Fargo on ‘Worrying' Engagement Trends
- InMed receives Nasdaq deficiency notice on equity requirement
- Par Pacific Holdings stock hits all-time high at 87.07 USD