
Bullfrog Spas Marks 30 Years of Innovation, Growth and Utah-Based Manufacturing
Source: PR Newswire
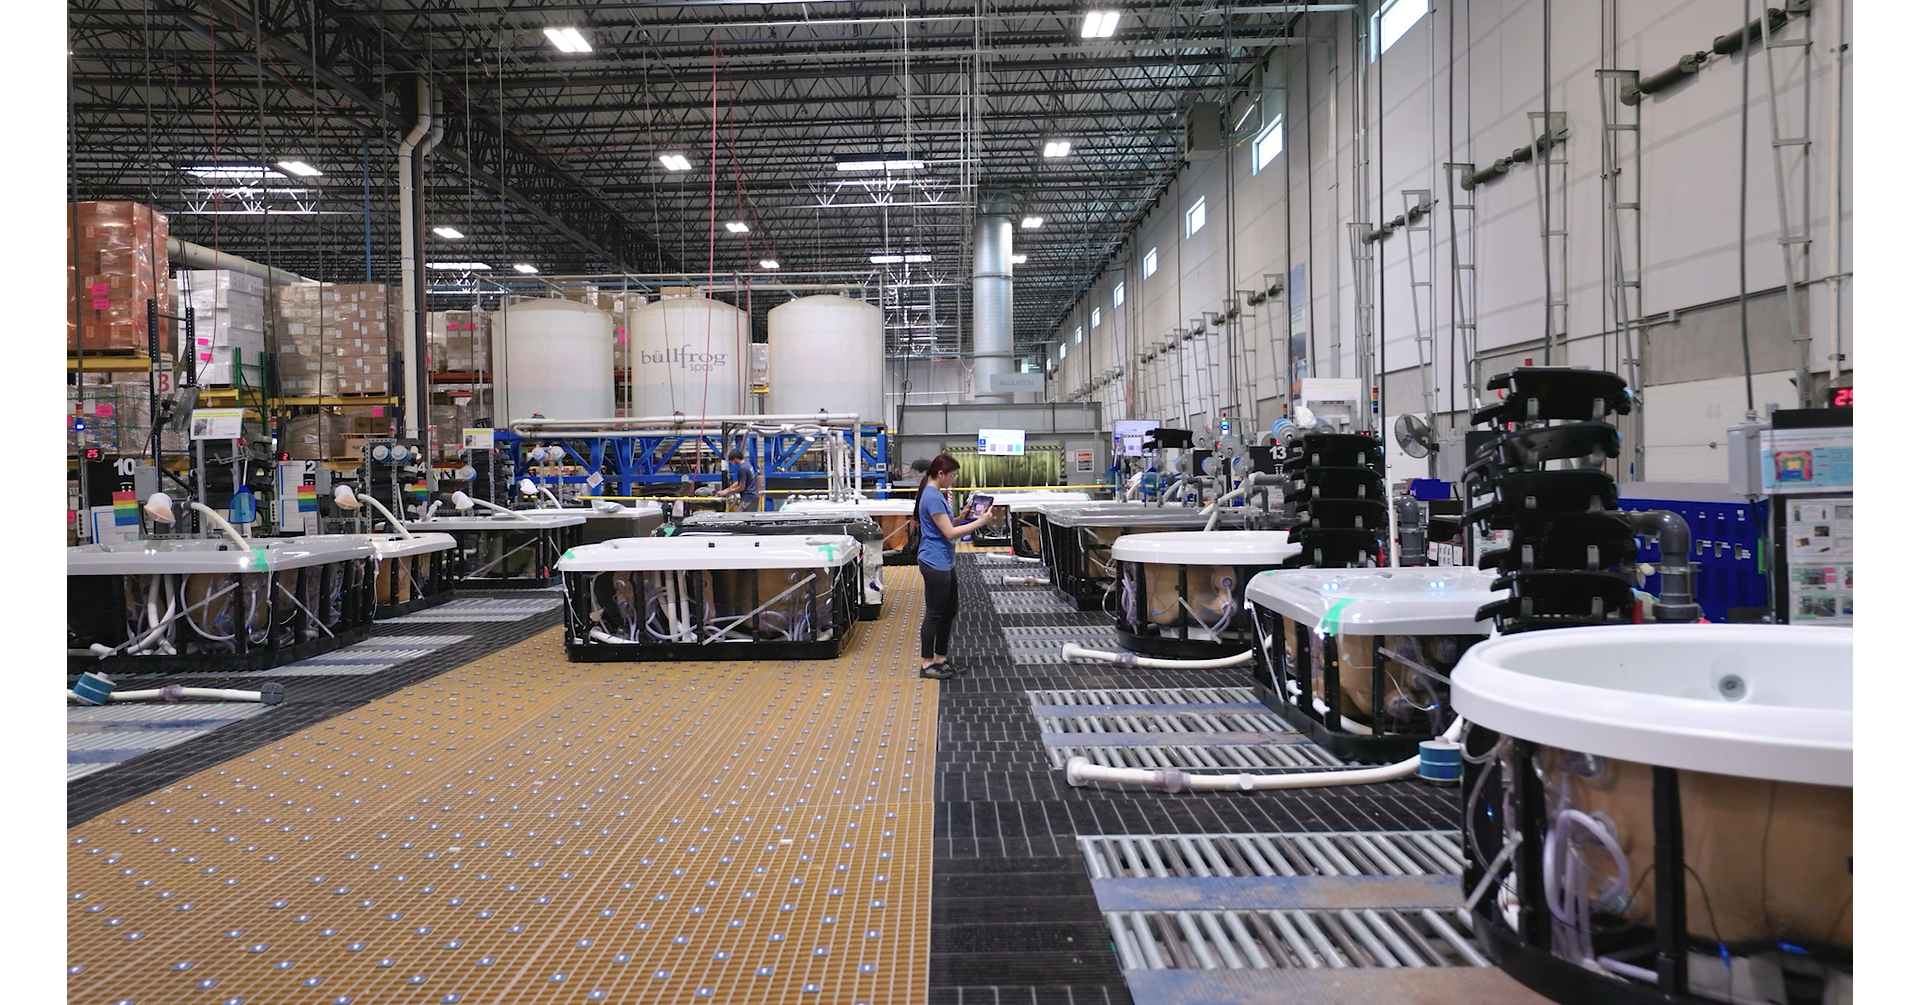
Bullfrog Spas marked its 30th anniversary, growing from 2 employees and 24 spas in its first production year to ~590 employees and nearly 280,000 spas produced over three decades. The company highlights its patented JetPak Therapy System and continued product expansion, including the M Series launch (2020) and Swim Series (2022) plus new Calm Series (2026). The article is primarily a corporate milestone/culture update with no financial figures, so near-term market impact is likely limited.
Analysis
This is effectively a sentiment-only release: a private-company anniversary does not change public-market cash flows, but it does reinforce that premium outdoor leisure remains a niche where brand, patent moat, and dealer relationships matter more than commodity input costs. The nearest public read-through is not the company itself but the ecosystem around big-ticket home discretionary spending: high-end spa demand tends to correlate with affluent housing turnover, remodel budgets, and consumer confidence, which supports a modestly positive backdrop for names like POOL, HD, and LOW only if their proprietary dealer and accessory channels are still seeing attach-rate strength.
The second-order risk is macro, not product. Spas are financed discretionary purchases, so elevated real rates and tighter credit can delay orders by one to two quarters even if brand enthusiasm stays intact. If the category is truly growing, the beneficiaries over 6-18 months are the dealers and service networks with recurring chemicals/parts revenue, while smaller direct-to-consumer brands are more exposed to promo pressure and working-capital strain when demand softens.
Contrarian takeaway: the market should not infer operating momentum from a ceremonial milestone. The right signal would be dealer inventory drawdowns, order backlog, or margin expansion from mix shift into higher-end systems; absent that, the move is likely overdone if investors chase "premiumization" without hard evidence. Falsifier for any bullish read-through would be weakening housing-related demand indicators or management commentary from public home-improvement proxies showing softer big-ticket tickets over the next 1-3 months.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- No direct trade on PPLI: treat this as a non-event for public equities unless follow-up data shows backlog or dealer sell-through improvement.
- Watchlist: POOL, HD, LOW for 1-3 month confirmation of premium outdoor-spend resilience; only get constructive if same-store/accessory attach data improves into the next print.
- If looking for a relative-value expression, prefer long HD/LOW vs XLY only after evidence that discretionary home-improvement tickets are holding up; otherwise stay flat.
- Set an alert on mortgage rates and consumer-credit delinquencies: a further rise would likely pressure spa and other financing-sensitive discretionary categories within one to two quarters.
- If a public competitor/retailer later reports strong premium outdoor-leisure sell-through, consider a pair long the stronger home-discretionary operator vs short a weaker small-cap consumer durable name with higher leverage and slower dealer turns.
More News
- ‘If nothing is done, it’s almost inevitable’: Ukraine’s Yuriy Ryzhenkov on why steelmaking is on the brink of collapse as Russian bombing intensifies
- Why is LG Innotek stock plunging today?
- TotalEnergies, KKR expand U.S. solar venture with 700 MW addition
- Why is SK Hynix stock sliding today?
- TikTok CEO sees major scientific breakthroughs from AI within three years
- Vår Energi cuts 2026 output forecast; Q3 production at 369,000 boepd