
Patriot Consulting Launches Free ISOC Cost Evaluation and Agentic MXDR365 Operations for Microsoft's New Integrated Security Operations Center
Source: PR Newswire
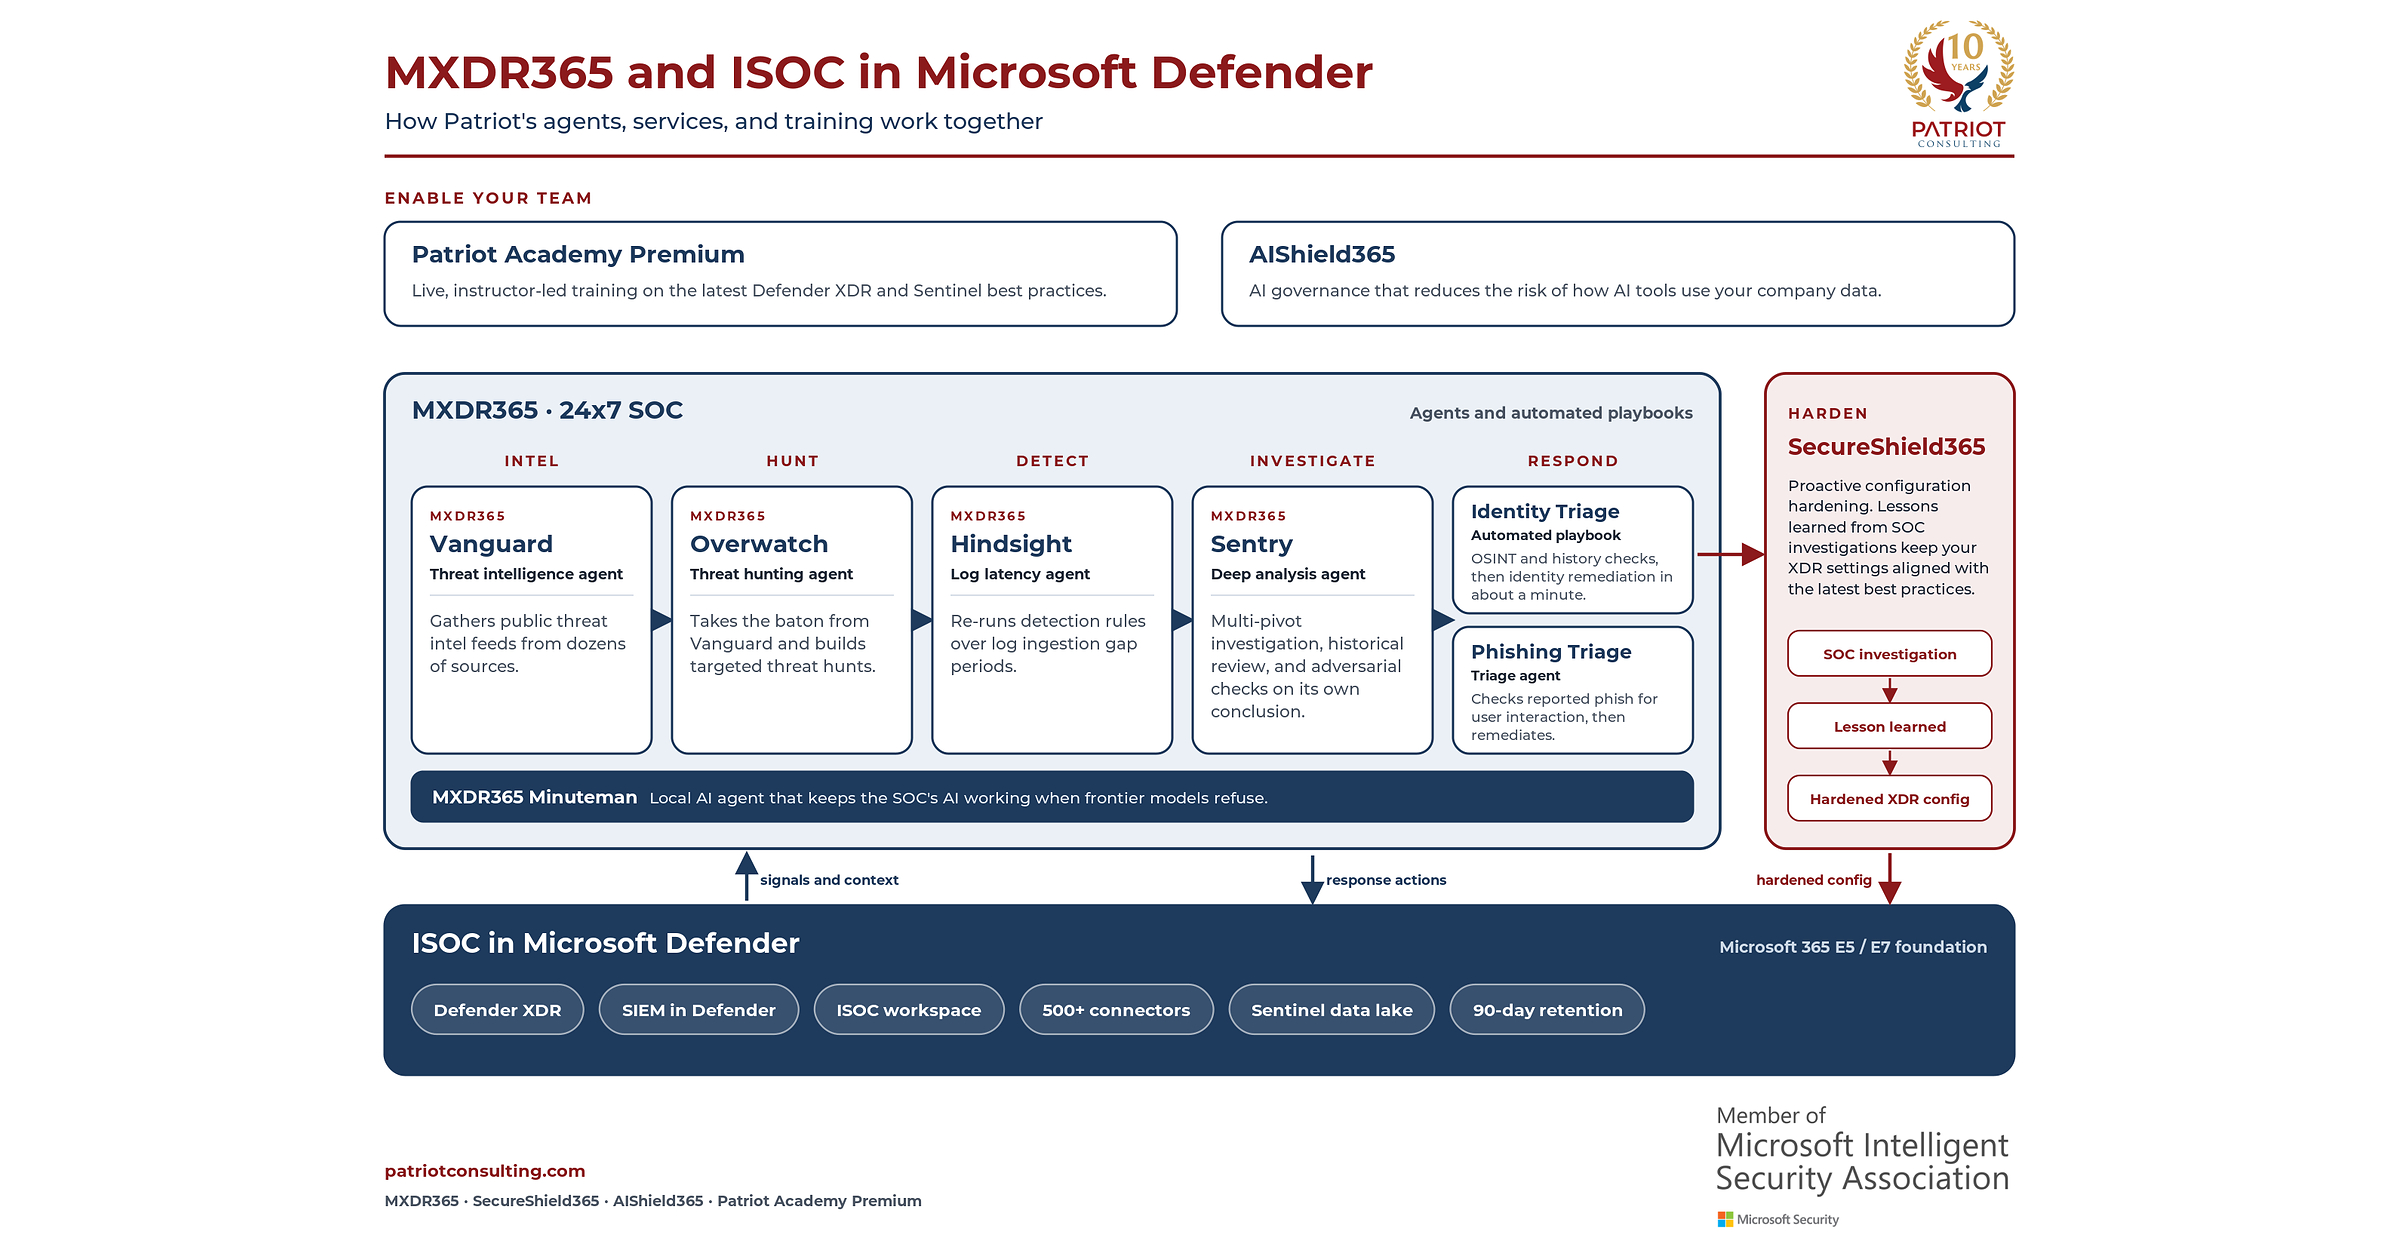
Patriot Consulting launched a free tenant-specific ISOC cost evaluation for Microsoft 365 E5/E7 customers as Microsoft integrates SIEM capabilities into Defender. ISOC will provide 90 days of Defender data retention from November 15, 2026 and charge $2.40/GB for non-Microsoft data ingestion from October 1, 2026, a 44% discount to Microsoft Sentinel's $4.30/GB pay-as-you-go list price. The firm is also positioning its 24x7 MXDR365 service, including seven AI-driven security agents and remediation playbooks, to support ISOC deployments, though savings will depend on each customer's log volumes, licenses and existing Sentinel data-tiering setup.
Analysis
The economic significance for MSFT is less the lower headline ingestion rate than a packaging shift that raises the switching cost of the E5/E7 security stack. Collapsing SIEM workflows into Defender can improve E5/E7 renewal defensibility and attach rates for Security Copilot, Entra and Purview, while reducing the operational rationale for a standalone Splunk/Cisco, CrowdStrike or Palo Alto-centric SOC. Near-term revenue impact is likely immaterial relative to Microsoft’s scale, but it strengthens the security bundle’s ability to support premium per-seat pricing over the next 6-18 months.
The important caveat is that non-Microsoft telemetry remains metered. Large enterprises with cloud, network and endpoint estates outside the Microsoft ecosystem may find that lower per-GB pricing is offset by lost bundled ingestion allowances or migration labor; this favors hybrid architectures rather than wholesale SIEM displacement. The most exposed vendors are services-led MDR providers whose differentiation is monitoring Microsoft telemetry, whereas platform vendors retain an advantage where customers require broad third-party data normalization, long retention, and multi-cloud detection.
Consensus may overstate the immediate competitive damage to CRWD, PANW and CSCO: SOC migrations are governed by retention, detection-content validation and compliance cycles, not list-price arithmetic. The stronger second-order outcome is likely channel consolidation: Microsoft-focused managed-security partners gain demand for assessment, migration and 24x7 operations, accelerating adoption without necessarily creating a near-term license windfall for MSFT. Monitor Microsoft’s next earnings call for Security revenue growth, E5 mix commentary and any disclosure of Defender/Sentinel consumption trends; absence of an acceleration by the January 2027 quarter would weaken the monetization thesis.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Ticker Sentiment
Key Decisions for Investors
- Maintain or add modest MSFT overweight on 6-18 month horizon; treat this as a durability/attach-rate catalyst rather than a standalone earnings driver. Reassess if Security growth decelerates materially or management signals ingestion cannibalization without higher E5/E7 mix.
- Watch-list pair: long MSFT / short cybersecurity SaaS basket (HACK) only if enterprise channel checks show Defender consolidation displacing standalone SIEM/MDR budgets in 1H27. Do not initiate solely on this announcement; migration volumes, retention requirements and third-party log mix are missing.
- Avoid a directional short in CRWD or PANW based on this development alone. A tradeable negative catalyst would require evidence of reduced net-new enterprise wins, falling module attach, or explicit competitive losses to Microsoft in the next two reporting cycles.
- For MSFT options, favor defined-risk exposure only after a broader software multiple pullback: 6-12 month call spreads are preferable to outright calls because the incremental revenue contribution is unlikely to alter near-term consensus EPS.
More News
- Trump’s AI lunch included every major tech company. Except Apple
- Exclusive-Anthropic’s IPO pitch embraces AI’s promise and peril
- Nasdaq Index: PCE Rally Meets Yield Wall as Micron Earnings Loom
- Two trades that just happened in 'Magnificent Seven' stocks point to big gains ahead
- Azure maintenance mess disrupted hybrid clouds, VPNs, cloudy VMware services
- Azure maintenance mess disrupts hybrid clouds, VPNs, cloudy VMware services