
Apple’s iPhone Duo Tackles the Challenge of Taking Foldables Mainstream
Source: Bloomberg
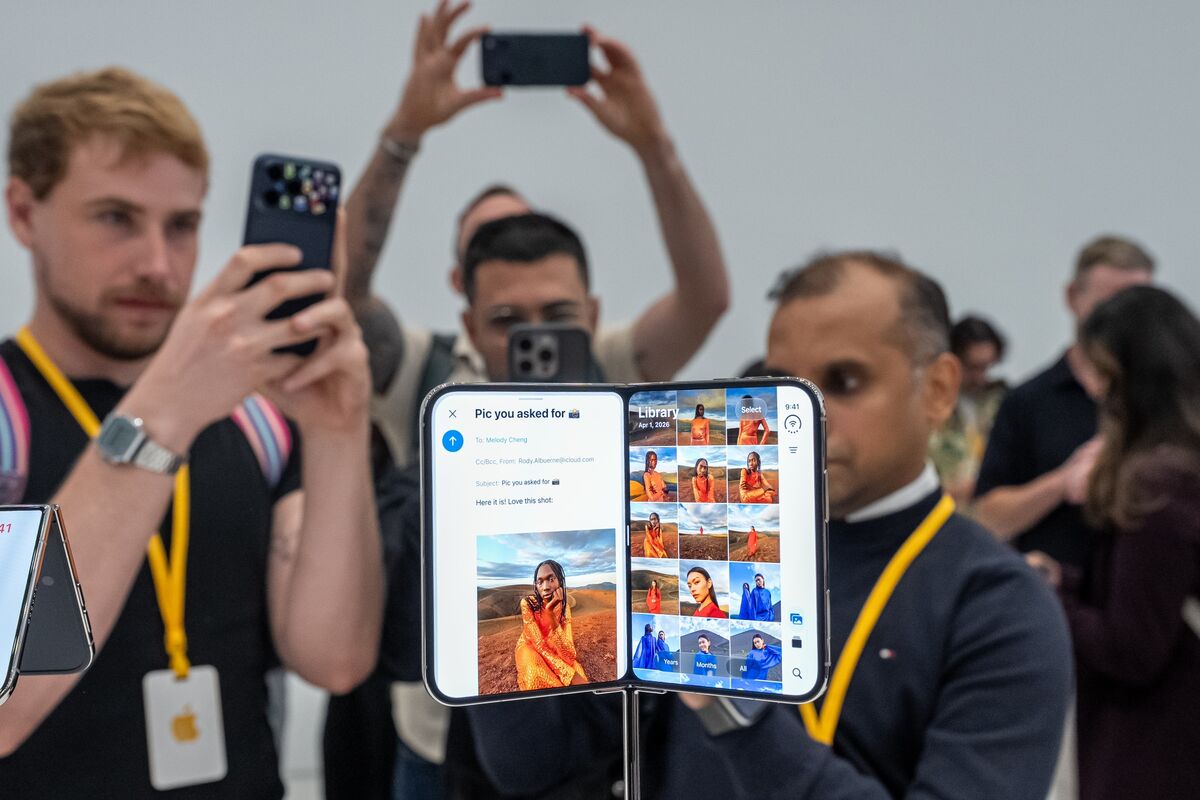
Apple is seeking to bring foldable smartphones into the mainstream with its newest device, referred to as Duo, aiming to reshape consumer preferences in the category. The article also notes that executives from three leading AI companies are calling for a slowdown in advanced-model development because of rising risks, adding a cautious regulatory and technology-risk backdrop.
Analysis
AAPL's foldable opportunity is less about creating a new hardware profit pool than defending premium smartphone mix as replacement cycles lengthen. A credible foldable can shift high-income Android switchers into Apple's ecosystem and support a higher blended iPhone ASP, but the initial unit contribution is unlikely to move FY earnings materially; the investable question is whether the device sustains gross margin above the current flagship range after adding a costly display, hinge, and potentially larger battery. Early supply-chain yield data—not launch-day demand commentary—will determine whether the product is margin accretive.
The more exposed beneficiaries are likely component suppliers with differentiated foldable-display and hinge content, while Samsung Electronics' handset division faces the clearest competitive risk in markets where its foldables have built mindshare. Conversely, a premium device priced materially above the Pro Max could cannibalize Apple's own high-margin flagship demand rather than expand the addressable market, limiting revenue upside while raising warranty and repair-cost exposure. This is especially relevant if carrier subsidies remain geared toward conventional handsets.
Near term, this is not a thesis-changing AAPL catalyst absent evidence of a launch within the next 12 months and a disclosed price/production target. Over 6-18 months, successful adoption would reinforce Apple's premiumization narrative and reduce the risk that hardware innovation leadership migrates to Samsung and Chinese OEMs; failure would likely be absorbed by Services growth but could cap multiple expansion if investors had begun underwriting a new upgrade cycle. The key falsifiers are display yield constraints, a sub-flagship gross-margin guide, or channel checks showing foldable buyers merely trading up from existing Pro models.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.05
Ticker Sentiment
Key Decisions for Investors
- Maintain, rather than add to, AAPL ahead of independently corroborated production-volume and bill-of-materials data; treat a confirmed launch window plus evidence of yields consistent with flagship gross margins as the trigger for an incremental long.
- For a 6-12 month competitive hedge after a confirmed Apple launch, evaluate long AAPL versus short Samsung Electronics (005930 KS), sized modestly: the trade requires evidence that Apple is targeting a conventional-phone replacement purchase rather than a niche tablet substitute. Exit if Samsung foldable share holds or Apple pricing is sufficiently high to constrain conversion.
- Set an event-driven alert on AAPL: a hardware gross-margin guide below expectations, elevated warranty provisions, or reports of delayed display qualification would argue against premiumizing the multiple and favor reducing exposure. Conversely, supply-chain indications of multi-million-unit initial builds with stable yields would make the upside more credible.
- Do not position around the AI-risk commentary on this information alone; without named companies, regulatory actions, model-release changes, or capex implications, it is not a tradable catalyst.
More News
- OpenAI President Greg Brockman on Doing Business in the Wake of Hugging Face
- Apple: JPM says delivery lead times for iPhone 18 line down from last year
- Nvidia CEO Jensen Huang admits he criticizes everything his 42,000-plus employees show him: ‘You can’t go a day without some criticism’
- Can New iPhone Duo Power Apple's Stock Higher?
- SpaceX vs. Apple: Wall Street Sees Strong Upside for One of These Stocks and Remains Neutral On the Other
- Tim Cook Could Have Purchased Any of 488 S&P 500 Companies With $879 Billion. Instead, He Bought Something That Changed Apple's Fortune Forever.