
TECNO Showcased New MEGABOOK Laptops and New Phones at IFA ShowStoppers 2026
Source: PR Newswire
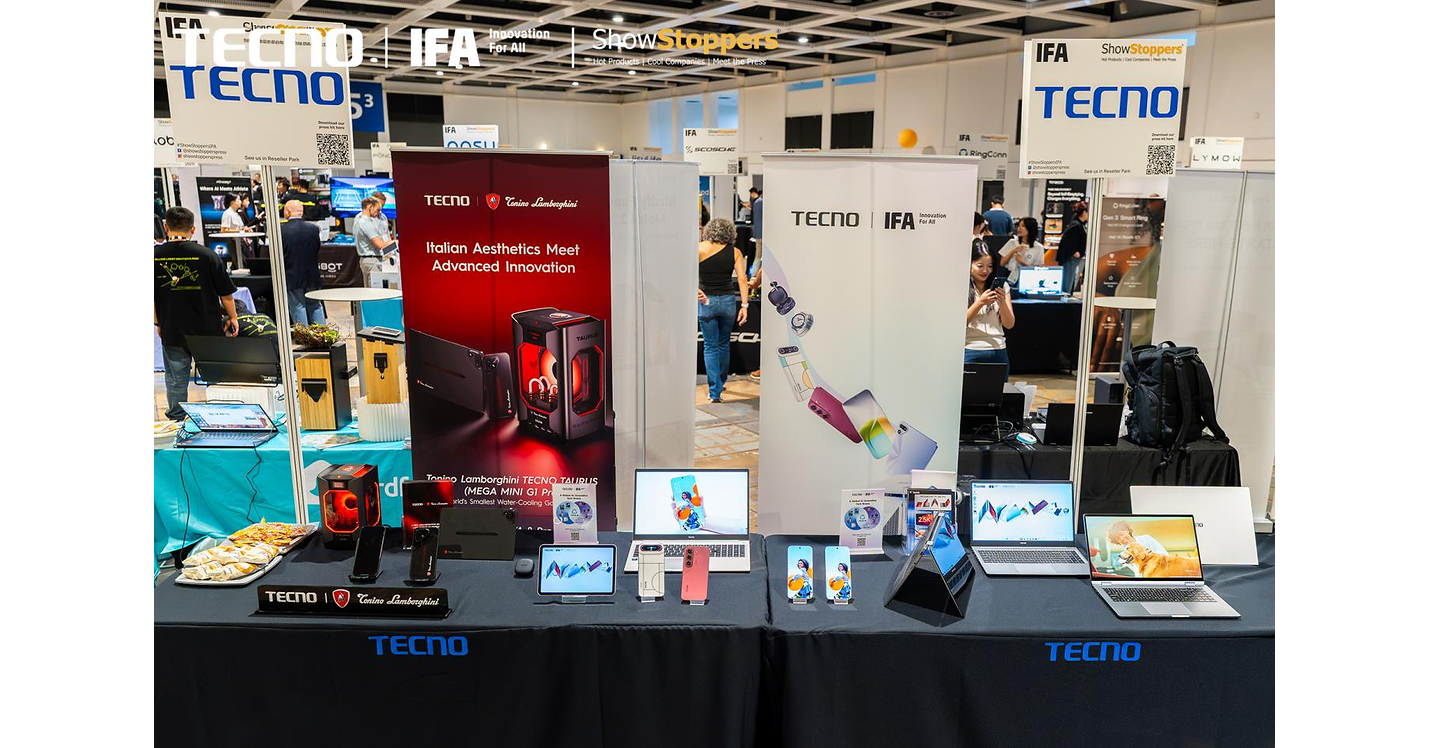
TECNO launched its first laptop series, the MEGABOOK T15 360 (and T15 360 Pro), featuring a 360° hinge touchscreen and optional MPP 2.0 pen support, with the standard model priced at €899–€999 and the Pro at €1,099 for Europe in Q4 2026. The Pro upgrade includes a 2.5K 120Hz 2560×1440 display (350 nits, 100% sRGB) and up to Intel Core Ultra 9 185H with LPDDR5X up to 7467MHz, plus a 70Wh battery. The IFA showcase also highlighted a next-gen near “0mm border” bezelless concept phone and upcoming smartphones: POVA 8 Pro 5G Tonino Lamborghini limited edition and the ultra-slim CAMON Slim 5G.
Analysis
This is more useful as a distribution signal than a fundamental catalyst. Landing an Intel-powered convertible in a value-oriented OEM lineup helps keep Intel visible in the lowest-friction part of the PC market, where win rates matter more than average selling price and where AMD/Qualcomm can still pressure share via battery life and total platform cost. The second-order takeaway is that Intel remains relevant in volume notebooks outside the premium AI-PC conversation, which slightly improves the odds of CCG stabilization, but it does not change the near-term earnings bridge unless units scale materially.
The market should not pay much for this headline in the next few days: launch PR from a smaller brand rarely translates into measurable revenue, and convertibles are still a niche within overall PC demand. Over 1-3 months, the relevant catalyst is not the product reveal but whether holiday channel inventory and notebook mix show an uplift in touch/2-in-1 attach rates; if that fails, this is just showroom noise. Over 6-18 months, the structural question is whether Intel can defend entry and mid-tier Windows share as OEMs diversify silicon across AMD and Qualcomm.
Contrarian view: consensus may be underestimating how much low-end and regional OEM wins can matter to Intel’s utilization and gross margin floor, but it is also easy to overread any design win as share recovery. The thesis is falsified if Intel’s next two prints do not show CCG revenue stabilization or gross margin expansion, or if PC shipment data confirms that convertibles are cannibalizing rather than expanding total demand. In that case, the right trade is to fade headline-driven pops rather than buy the story.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.12
Ticker Sentiment
Key Decisions for Investors
- No immediate outright trade in INTC: wait for verifiable sell-through evidence in the next 1-2 earnings cycles before assuming any share gain or mix benefit.
- If INTC rallies >3% on this launch news alone, consider fading the move with a short-dated call spread or small short against SMH; the fundamental impact window is too small to justify multiple expansion.
- Set an alert on Intel’s next Client Computing Group disclosure: if revenue and gross margin both improve sequentially, that is the first point where these OEM design wins become investable rather than symbolic.
- Watch industry notebook shipment data and 2-in-1 attach rates into Q4; if touch-convertibles are growing without ASP compression, reassess a medium-term long INTC position.
- If Qualcomm/AMD PC share data accelerates over the next quarter, treat this as a competitive noise event and avoid extrapolating the TECNO win into broader Intel share recovery.
More News
- Jim Cramer: Why I am taking the other side of the trade that crushed the market Friday
- Indonesian stocks plunge to six-year low as MSCI downgrade fears mount
- Putin reportedly suggests summit with Trump and Xi to decide fate of Ukraine
- China's CXMT sees shares drop over 6% as investors look past chipmaker's profit turnaround
- Asian stocks skid, Wall Street and bonds aided by oil slip
- Australia’s Cleanaway agrees to $6.5 bln EQT buyout bid; shares surge
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Augmented Intelligence: AllMind, Elevate Human Judgement With an Accessible, Powerful, Data-Driven Financial AI Toolkit
- AI Research Systems for Hedge Funds: A Pilot Design