
United Community Names Dr. Jeff Beisler-Snell Head of International Banking and Capital Markets
Source: PR Newswire
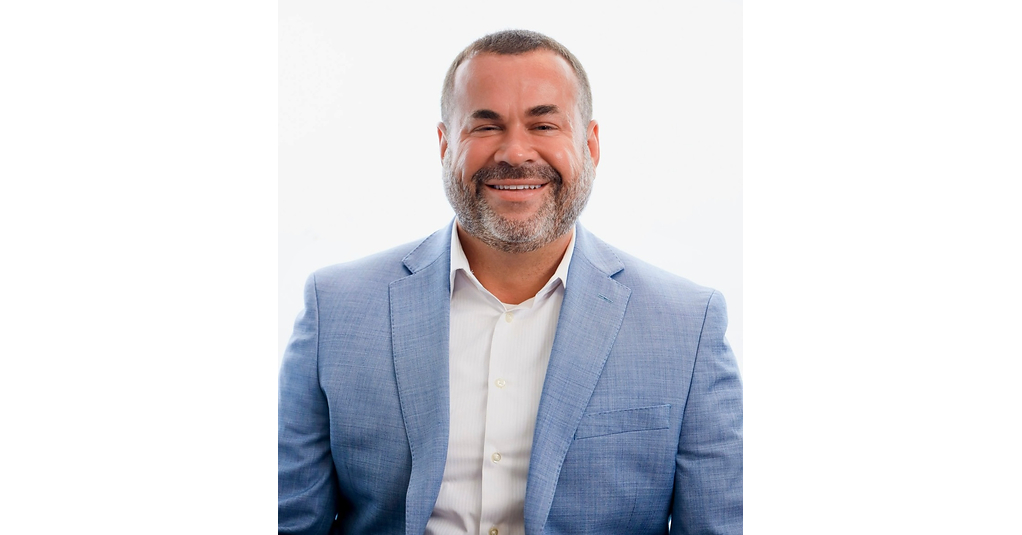
United Community named Jeff Beisler-Snell head of International Banking and Capital Markets, launching a new international banking team to expand support for international payments, foreign exchange, trade services, and cross-border treasury needs. The hire leverages his 20+ years of experience in FX and trade finance and is positioned as an effort to help customers manage global risk and transactions. Overall, this is a modest positive capability-building update with limited near-term earnings impact.
Analysis
This is more signal than substance: adding an international banking lead can improve UCB’s fee mix, but the near-term P&L impact is likely immaterial unless it converts into treasury-management balances and recurring FX/payment flows. The real value is deposit stickiness and cross-sell, which matters for a regional bank trying to reduce reliance on spread income in a slower-growth rate environment.
The competitive angle is that cross-border capabilities are a relationship moat, not a commodity product. If UCB can win mid-market import/export clients, it can displace smaller regionals that lack trade finance expertise and push more of the economics into noninterest income. That said, larger regionals and super-regionals already have deeper product suites, so the upside is mostly share defense and selective wallet-share gains, not a step-change in franchise quality.
On timing, this is a 6-18 month thesis, with the first meaningful test coming in quarterly fee-income and commercial deposit trends rather than press-release momentum. The main downside is execution risk: if the hire becomes a cost center without booked balances, the market will treat this as SG&A creep. What would falsify the bullish read is no sequential improvement in treasury-management fees, FX volumes, or commercial deposit growth over the next 2-3 quarters.
Contrarian view: the move may be underappreciated only if it is part of a broader push into higher-fee commercial banking. Otherwise, the market is right to discount it as routine talent acquisition with limited economic leverage.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Ticker Sentiment
Key Decisions for Investors
- No immediate trade in UCB; treat as a watch item until next 2 quarters of noninterest income and commercial deposit data confirm monetization.
- If UCB re-rates only modestly on the hire, consider a small long UCB / short KRE pair on confirmation of fee-income acceleration over 1-2 quarters; upside is a higher-quality revenue mix, downside is limited if the signal proves cosmetic.
- Set an alert on UCB earnings for treasury-management fees, FX/payment volumes, and deposit growth from commercial clients; if these do not improve, fade any post-news strength.
- For peers with weaker product breadth, monitor OZK and other Southeast regionals for pressure on higher-balance commercial relationships; this is a share-grab risk over 6-18 months, not a day-one catalyst.
More News
- Why is T-Mobile stock tumbling today?
- Why is Verizon stock sliding today?
- SpaceX wants to become a 'major mobile carrier' with low-band spectrum acquisition
- OpenAI projected to bring in $20bn less in revenue than expected
- Soitec climbs 7% as BofA turns bullish on silicon photonics demand
- Schott Pharma drops after Deutsche Bank downgrades on demanding valuation