
Pylontech начинает массовое производство элементов LFP 588 А•ч и 601 А•ч для ESS
Source: PR Newswire
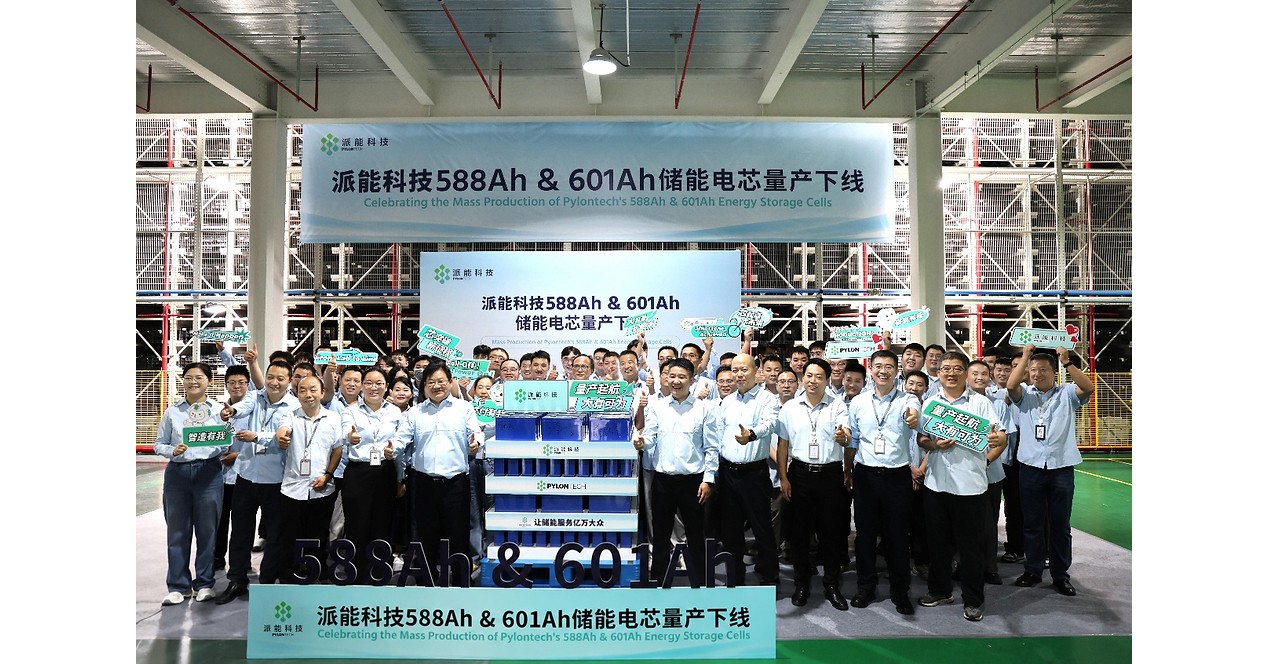
Pylontech began mass production of 588Ah and 601Ah prismatic LFP battery cells for utility-scale energy-storage systems at its Hefei facility, with more than 100MWh already produced. The 601Ah cell delivers 425.8Wh/L energy density, over 12,000 cycles and 96.5% energy efficiency, and will be integrated into PyOcean systems with 6.25MWh and 8MWh capacities. The launch strengthens Pylontech's utility-scale storage offering following deployments including 120MW/240MWh in Jiangsu and 200MW/400MWh in Ningxia.
Analysis
Pylontech’s strategic value is not the cell specification itself but the potential to compress balance-of-system cost and capture more of the utility-storage stack internally. Fewer cells, interconnects and racks can lower installation labor, footprint and warranty complexity, but these savings will likely be competed away in China’s increasingly commoditized BESS market unless Pylontech converts them into contracted overseas projects. The near-term earnings variable is therefore qualification and order conversion, not initial factory output.
The competitive read-through is mixed for CATL (300750:SZ), EVE Energy (300014:SZ) and BYD (1211:HK): larger-format LFP cells are becoming table stakes, raising the risk that cell-level differentiation narrows and shifts bargaining power toward EPCs, developers and system-integrators. Fluence (FLNC) and Tesla (TSLA) could benefit indirectly if cheaper Chinese LFP supply lowers delivered $/kWh, but they retain greater exposure to project execution, grid-interconnection delays and warranty reserves than to cell cost alone. For Pylontech (688063:SH), vertically integrated cell-plus-system supply can improve gross margin only if yields, field reliability and bankability match incumbent suppliers.
The contrarian concern is that oversized-cell economics look strongest in a datasheet and weakest during early field deployment. Utility buyers will require evidence of degradation, thermal behavior, availability and insurance acceptance across operating conditions; a single warranty or safety incident can erase several points of pricing advantage. Over the next 1-3 months, treat this as a qualification/order-flow catalyst rather than a fundamental rerating; the 6-18 month thesis depends on disclosed utility backlog, export mix and gross-margin resilience.
A bullish interpretation is underappreciated only if the company demonstrates that its system architecture—not merely its cell format—reduces lifetime project cost enough to win bankable international tenders. Without independently disclosed yield, contracted volume and project-level pricing, the announcement alone is insufficient to justify chasing the equity.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.58
Key Decisions for Investors
- Watch Pylontech (688063:SH) rather than initiate immediately; upgrade to a tactical long only after the next results show utility-scale backlog growth and stable/improving gross margin. Thesis is falsified by margin compression despite shipment growth, indicating that cost savings are being passed through to customers.
- Use a 3-6 month relative-value screen: long CATL (300750:SZ) / short a broad China battery-materials proxy or weaker LFP-cell peer only if large-cell BESS tender pricing declines while CATL sustains utilization and operating margin. This expresses consolidation rather than betting on a single product launch.
- For US-listed exposure, keep FLNC on a catalyst watchlist into utility-storage bookings and margin guidance; lower cell costs are beneficial only if they translate into higher project gross profit rather than customer price concessions. Do not add ahead of evidence on backlog conversion and warranty-reserve trends.
- Set an alert for disclosed export contracts, third-party safety certification, and 6-12 months of field availability data for Pylontech’s new platform. Those are the missing datapoints needed to distinguish a credible bankability upgrade from a capacity-marketing event.
More News
- Chinese authorities reportedly in possession of F-35 components in Hong Kong
- Meta announces new lightweight virtual reality glasses to one-up Apple’s Vision Pro
- How Meta took the lead in the race for the post-smartphone world
- SoftBank shares jump over 7% after $11.1 billion bond issuance to fund OpenAI bet
- Mark Zuckerberg debuts $1,299 Meta VR Glasses and Muse Charm pendant amid AI agent push
- Meta's standoff with Amazon over Muse could be a sign of things to come
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AllMind Fixed Income Compass for October 2025: Navigating Policy Divergence and Political Risk
- AI Equity Research Tools for RIAs and Wealth Managers