
New York Butcher Shoppe Named Retail Rising Star by the Certified Angus Beef® Brand
Source: PR Newswire
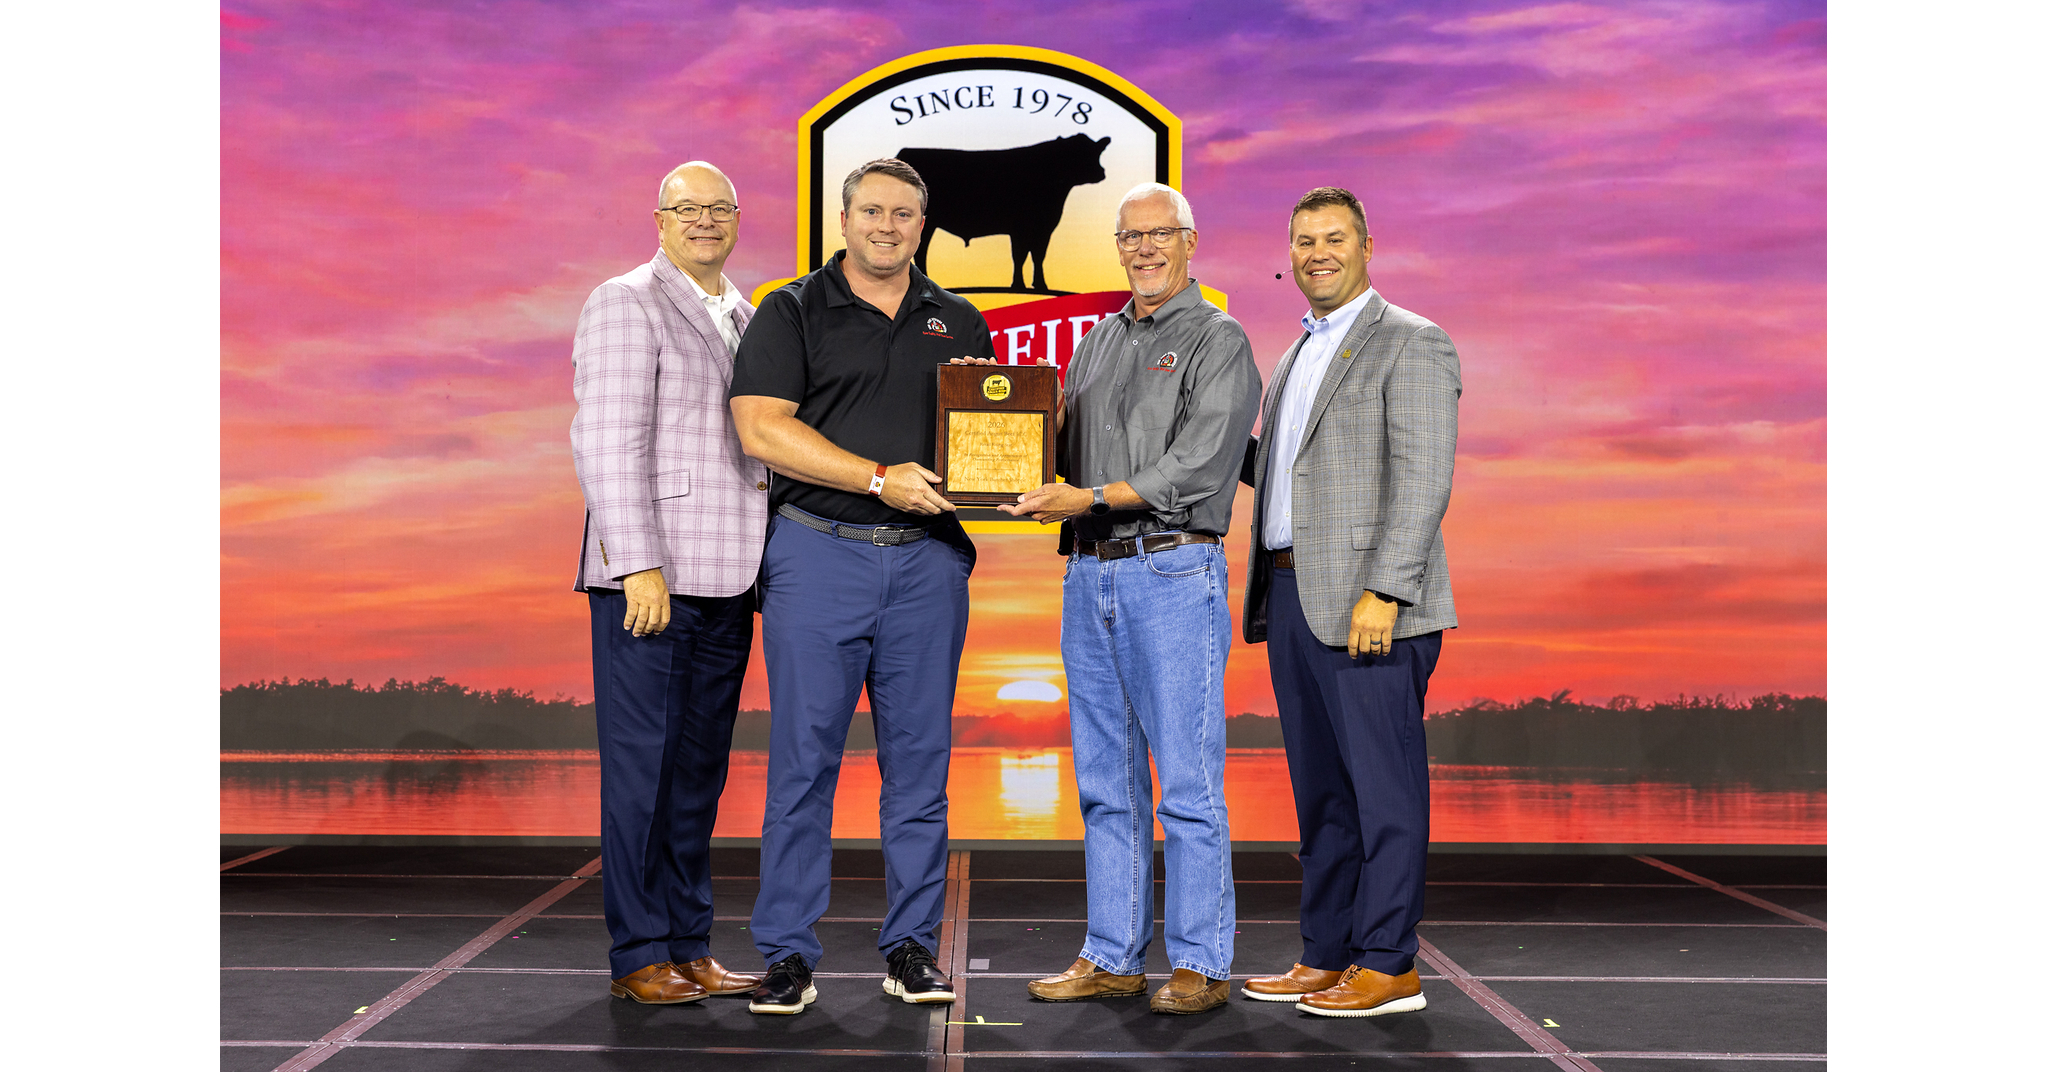
New York Butcher Shoppe received Certified Angus Beef’s 2026 Retail Rising Star award, recognizing its partnership with the brand that began in 2003. The retailer operates 43 locations across 10 states and is on track to exceed 50 by the end of 2027, with recent development agreements in five states. The release also cites more than 1 million pounds of Certified Angus Beef products purchased by December 2024 and over 1,500 meat thermometers sold last year.
Analysis
The investable signal is franchise execution, not the award: the recognition may help lower customer-acquisition friction, but it does not establish attractive franchisee returns or durable royalty growth. Expansion beyond the current base could increase purchasing leverage and brand awareness; it could also dilute service consistency and make qualified beef availability more consequential. Because the capital burden sits substantially with franchisees, announced openings should not be treated as equivalent to company-funded revenue growth. Premium beef sourcing is a potential constraint as the footprint expands: if supply tightens or input costs rise faster than menu and retail pricing, the same quality promise that supports differentiation could pressure franchisee economics. The release provides no same-store sales, unit-level payback, royalty contribution, closure rate, or sourcing-cost data to test that risk. Near term, the award is a modest marketing catalyst with little basis for a public-market repricing. Over 1–3 months, verify signed agreements convert into opened stores; over 6–18 months, assess whether new units sustain customer demand and franchisee returns. The contrarian read is that the growth target may look more compelling than the underlying evidence: an award and a pipeline are not proof of profitable, repeatable unit economics. No direct public-equity exposure is identified in the supplied company mapping.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Key Decisions for Investors
- No direct equity trade on this release; the company and its investment partner are not identified as publicly traded in the supplied mapping.
- Track announced openings against actual store launches and request evidence on same-store sales, franchisee payback, closures, and recurring royalty economics before treating expansion as fundamental upside.
- Monitor beef procurement costs and product availability as the footprint grows. A sustained rise in input costs without corresponding price realization would challenge the premium-positioning thesis.
- Reassess the growth thesis if openings slip materially beyond the stated 2027 goal, or if franchisee economics weaken; confirmation would require successful launches plus stable repeat demand and unit returns.
More News
- Former world No. 1 Jon Rahm's lawyer tells court Spaniard is done with LIV Golf after three seasons
- Anthropic will be 'most ridiculous IPO' of year, analyst says
- Levi Strauss hikes profit guidance after tariff refunds, but its sales outlook is less optimistic
- Weston Family, Fairfax Financial’s Watsa Acquire Boots in $8.9 Billion Deal
- Samsung Q3 profit surges to record high, but misses lofty expectations
- Brazil is having its Argentina moment. How to play it