
Zoomlion célèbre son 34e anniversaire en mettant en avant ses avancées en matière d'innovation et de croissance mondiale
Source: PR Newswire
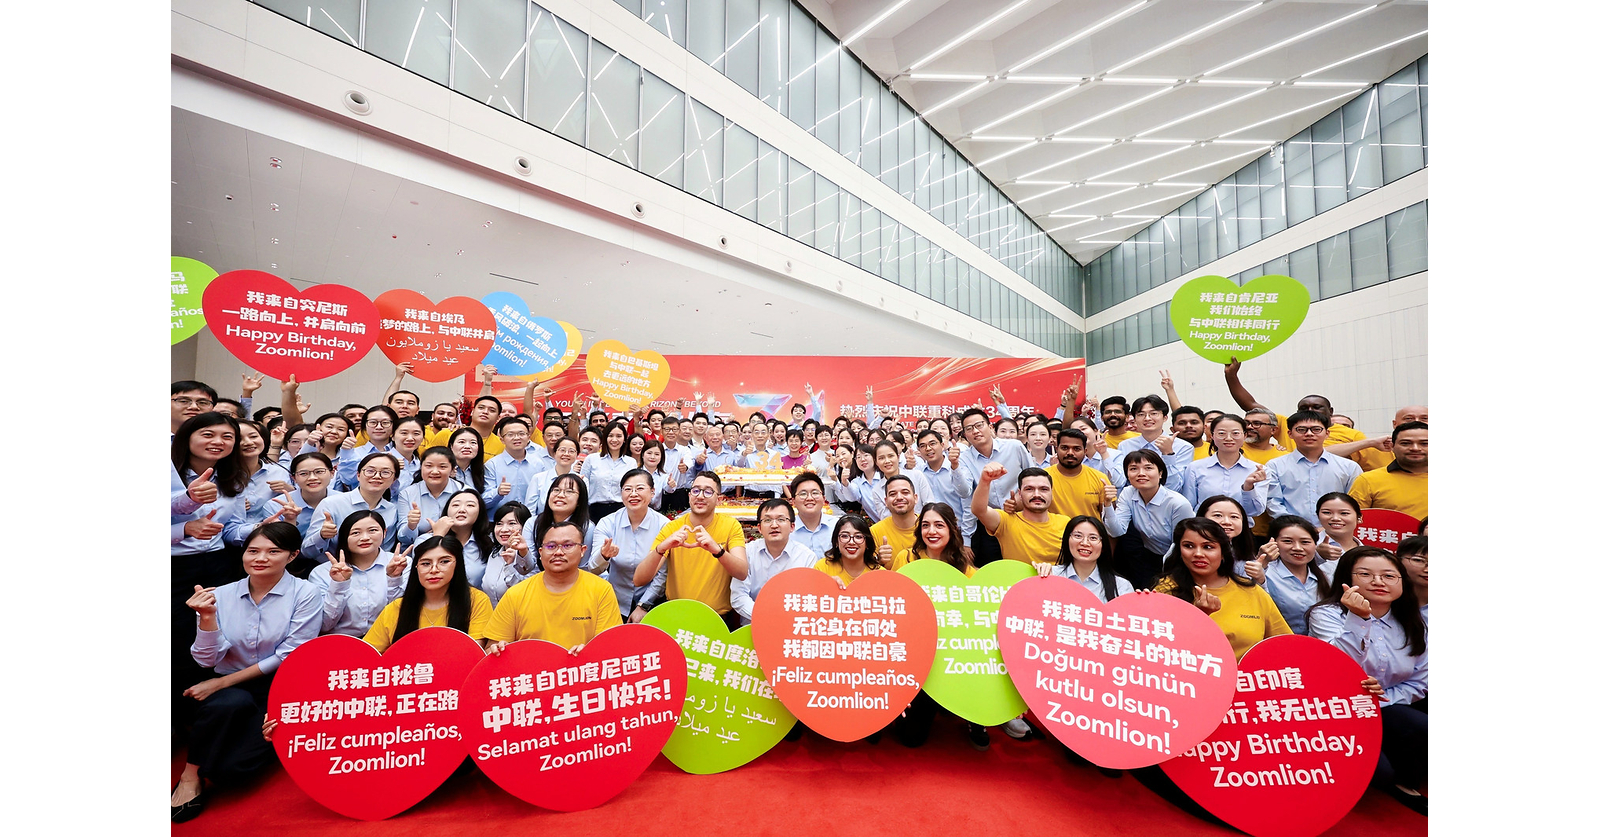
Zoomlion marked its 34th anniversary by highlighting its global expansion, with international operations now accounting for nearly 60% of total revenue and products and services sold in more than 170 countries and regions. The construction-equipment manufacturer operates 11 overseas R&D and production sites and plans further diversification, globalization and digitalization, including investments in AI, robotics, smart equipment and new-energy technologies. The announcement is primarily a corporate milestone and strategic update rather than a disclosure of new financial results or guidance.
Analysis
This is a corporate-branding release rather than an earnings, order, or capital-allocation update; it provides no independently verifiable change to revenue, backlog, utilization, pricing, or margin. The relevant investable question is whether overseas localization is converting into higher service/parts mix and lower working-capital intensity, but neither is disclosed. Without evidence of export order growth, receivable days, or overseas gross-margin progression, the announcement should not alter estimates for Zoomlion (1157 HK; 000157 SZ).
The more consequential second-order risk is that Chinese construction-equipment manufacturers are increasingly competing abroad on local service coverage rather than just upfront price. That can pressure share and pricing for Sany Heavy Industry (600031 CH), XCMG (000425 CH), and selected lower-end product lines of Caterpillar (CAT) and Komatsu (6301 JP), while raising fixed-cost and FX exposure for Chinese exporters if global construction demand softens. Over 6-18 months, successful localization would justify a multiple re-rating only if overseas aftermarket revenue reduces cyclicality; otherwise, expansion may simply trade domestic demand concentration for more receivables and geopolitical risk.
Contrarian view: the market may over-credit international revenue mix as inherently defensive. Emerging-market equipment sales are often distributor-financed and commodity-linked, so a stronger RMB, weaker mining activity, or tighter local credit can turn nominal export growth into cash-flow deterioration within one to two quarters. The near-term catalyst path is therefore not this release, but upcoming quarterly disclosures on export growth, operating cash conversion, inventory, and bad-debt provisions.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Key Decisions for Investors
- No new directional position in 1157 HK or 000157 SZ on this release; set an alert for the next results for overseas revenue growth versus receivable-days and operating-cash-flow conversion. Consider a long only if international growth is sustained while receivables and inventory grow slower than sales.
- Monitor a 6-12 month relative-value pair: long CAT / short a basket of 1157 HK and 600031 CH only if Chinese peer export-led revenue growth fails to translate into margin or cash conversion. CAT's parts/service mix offers downside protection; invalidate the pair if Chinese peers demonstrate two consecutive quarters of accelerating overseas margins with stable credit losses.
- For existing Chinese equipment exposure, reduce risk if RMB appreciation accelerates or commodity-capex indicators weaken; those conditions would expose the gap between reported overseas sales growth and realized cash generation within 1-3 quarters.
More News
- Asian stocks dip, bonds in focus after torrid September
- Greer urges G20 to back Trump tariff agenda, takes aim at China
- Paramount Skydance prices $42 billion debt for Warner Bros deal
- Tencent leases 100,000 chips from Oracle for $7 bln- FT
- California Gov. Gavin Newsom bans AI 'robo bosses' in landmark state law, reversing his earlier veto
- The new and huger Paramount has a new co-CEO
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- How to Evaluate AI Report Writers for Financial Analysis
- Weekly Update: Sector Analysis, Improvements on Research Data, and Performance Enhancements