
BofA's CashPro App facilitates more than €100 billion in payments approved European companies
Source: PR Newswire
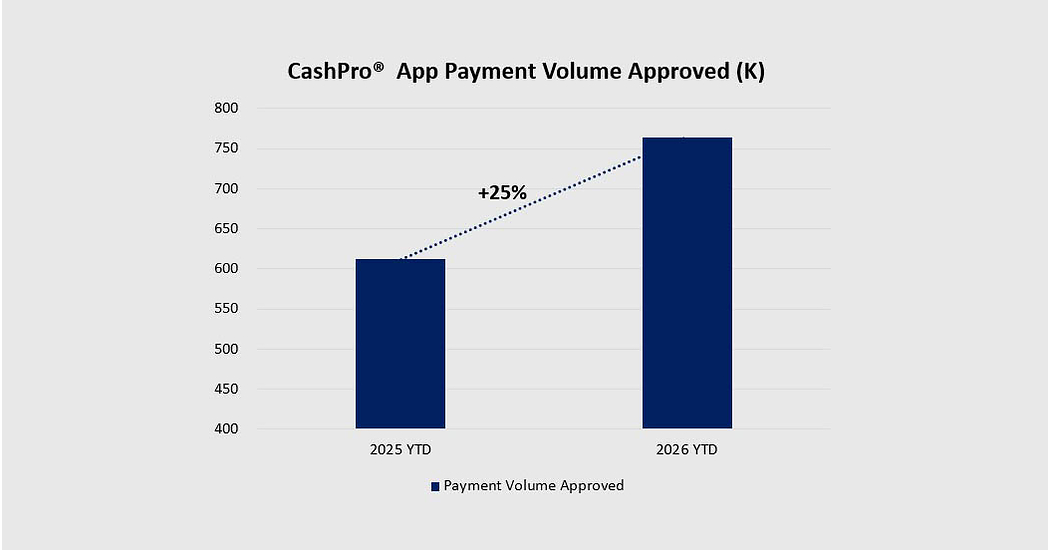
Bank of America said 74% of European CashPro users now select its mobile token as their preferred authentication method, reflecting increased mobile adoption in corporate treasury workflows. The bank enhanced mobile payment approvals based on client feedback and is developing digital identity verification for corporate administrators. CashPro serves more than 35,000 companies globally and incorporates AI tools for client service, capital-markets insights and cash forecasting.
Analysis
This is strategically positive for BAC’s Global Payments Solutions franchise, but too incremental to change near-term earnings. The value lies in reducing operational friction for treasury users while increasing platform stickiness: authentication, payment approval and administrator identity are high-frequency control points that make a later switch to JPM, C, WFC or a treasury-management-system overlay more costly. Over 6-18 months, stronger digital engagement can defend operating-deposit balances and payment flows—more valuable to BAC than modest software-cost savings, particularly if corporate liquidity becomes more mobile and less relationship-manager-led.
The more important second-order issue is fraud and liability. Moving high-value approvals to personal devices broadens the attack surface to SIM swaps, malware and social-engineering-driven push approval; a material incident would damage transaction-banking credibility disproportionately because treasury clients prioritize control over interface convenience. Digital identity verification is therefore a risk-control investment, not an AI monetization catalyst. Watch for disclosures on corporate payment fraud losses, client retention, treasury deposits and Global Payments Solutions fee growth rather than app-adoption statistics.
Consensus may overread digital awards and user-preference metrics as evidence of a revenue step-up. Corporate treasury platforms tend to be bundled into broader lending, deposits, FX and payments relationships, so competitive gains monetize slowly and are often offset by implementation and cyber-security spend. FFIV’s presence is commercially illustrative rather than a read-through: there is no basis here to infer a material revenue contribution or procurement win for FFIV; GPN has no direct economic linkage.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.32
Ticker Sentiment
Key Decisions for Investors
- No standalone event trade in BAC: the disclosed adoption signal is insufficient to alter FY estimates. Maintain BAC only within a broader large-bank view; reassess if quarterly Global Payments Solutions fee growth accelerates by >200bp year/year while wholesale deposits stabilize or grow.
- For a 6-12 month relative-value expression, prefer BAC over C if evidence emerges that BAC is gaining European multinational operating balances; use a 1:1 beta-adjusted BAC/C pair. Falsify on two consecutive quarters of BAC payments-fee underperformance versus C or a meaningful BAC cyber/fraud disclosure.
- Set a risk alert around BAC’s next earnings: elevated fraud-loss provisions, higher technology expense without fee/deposit traction, or commentary that mobile approvals require materially higher client-support costs would challenge the margin/stickiness thesis and favor reducing exposure.
- Do not buy FFIV or GPN on this development. Require independently disclosed contract value, integration designation, or payments-volume linkage before treating either as a beneficiary.
More News
- Biweekly Investment Insights: Markets swirl
- Warsh says AI’s hyperscalers are part of why your borrowing costs are rising: ‘The competition for capital is real’
- Meta's AI chips and Meta One strengthen Bank of America's outlook
- BofA Securities maintains Apple stock rating on carrier incentives
- Stocks, Treasuries Rally on Optimism Around Fed Inflation Fight
- Why Investors Were Hitting the Brakes on J.B. Hunt Stock This Week
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- What a Concept From Nature Tells Us About How C-Suite Executives Actually Think About AI
- How to Track Earnings Call Sentiment Across Companies