
India, China and the US Head Into a September of Summits
Source: Bloomberg
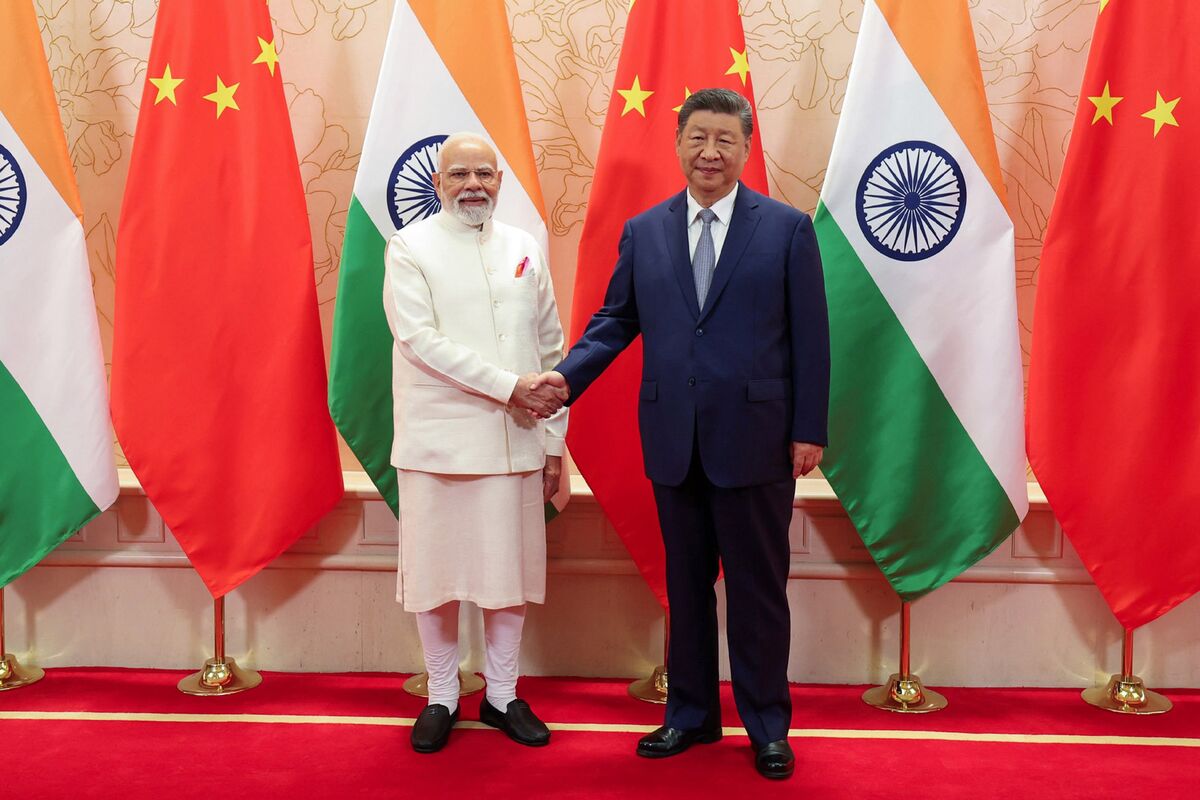
The article is primarily a preview of upcoming geopolitical and policy-focused coverage for September summits involving India, China, and the US, emphasizing the importance of improved China relations for border peace. It also references commentary that proposed changes to US H-1B visa fees are not expected to materially worry Indian IT firms. No specific data, policy figures, or market-moving outcomes are provided in the excerpt.
Analysis
The only real marketable mechanism here is geopolitical risk premium compression, and that matters more for India beta than for Visa. For V, the read-through is indirect at best: modestly calmer India/China/U.S. relations can support cross-border spend and travel over time, but it is too small and too diffuse to move near-term estimates or multiples. In other words, this is not an earnings event for V; it is a sentiment event for Indian assets.
The H-1B angle is more interesting for Indian IT than the street may be pricing. If the policy pressure rises, the first-order hit is to onsite delivery economics, but the second-order effect is acceleration of offshore mix and GCC buildout in India, which disproportionately helps the larger, higher-quality exporters with lower U.S. labor dependence. That argues for relative outperformance in large-cap IT versus U.S.-based services names if the fee proposal becomes real, but not necessarily a sector-wide air-pocket.
Contrarian view: the consensus may be overestimating how much summit season changes fundamentals in 1-3 months. Most of the move, if any, will come from headline-driven de-risking and factor flows, not from actual trade, border, or visa policy implementation. The key falsifier is the absence of concrete policy language by month-end; if the meetings produce no enforceable change, the market will likely give back the geopolitical premium quickly.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.05
Key Decisions for Investors
- Maintain a neutral stance on V; do not force a trade off this headline because the earnings linkage is too weak and any cross-border spend benefit is likely immaterial.
- Relative-value idea: long INDA / short FXI into the September summit window, targeting geopolitical-risk premium compression over 1-3 months; cut if India underperforms China by more than ~3% after the meetings without policy follow-through.
- If H-1B fee headlines intensify, buy weakness in large-cap Indian IT exporters such as INFY or TCS versus shorting U.S.-based services exposure like CTSH on a 1-3 month horizon; the thesis is offshore substitution, not demand destruction.
- Use the actual policy text as the trigger, not the press cycle: if fees apply broadly to renewals or new filings, reassess the IT basket; if it stays narrow, fade any selloff in Indian IT within days.
More News
- Nvidia GPUs are everywhere. Here are the ways companies are accessing them
- Why is US turning to Russia for diesel despite sanctions?
- Trump's Russian Diesel Deal Draws Ukraine Criticism
- Stocks were up this week. Here are the names that are now overbought
- As companies pour billions into Earth-based AI infrastructure, Google is taking the data center race off-planet
- How U.S. know-how is fracking Australia into a gas boom, from Texas oilmen to Trump’s energy secretary
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Alternative Data Due Diligence for Institutional Investors
- Introducing AllMind: A New Data & AI Workspace for Institutional Investors