
JLL advises on $856M in financing across The Millennium Residences and The Offices at Winthrop Center
Source: PR Newswire
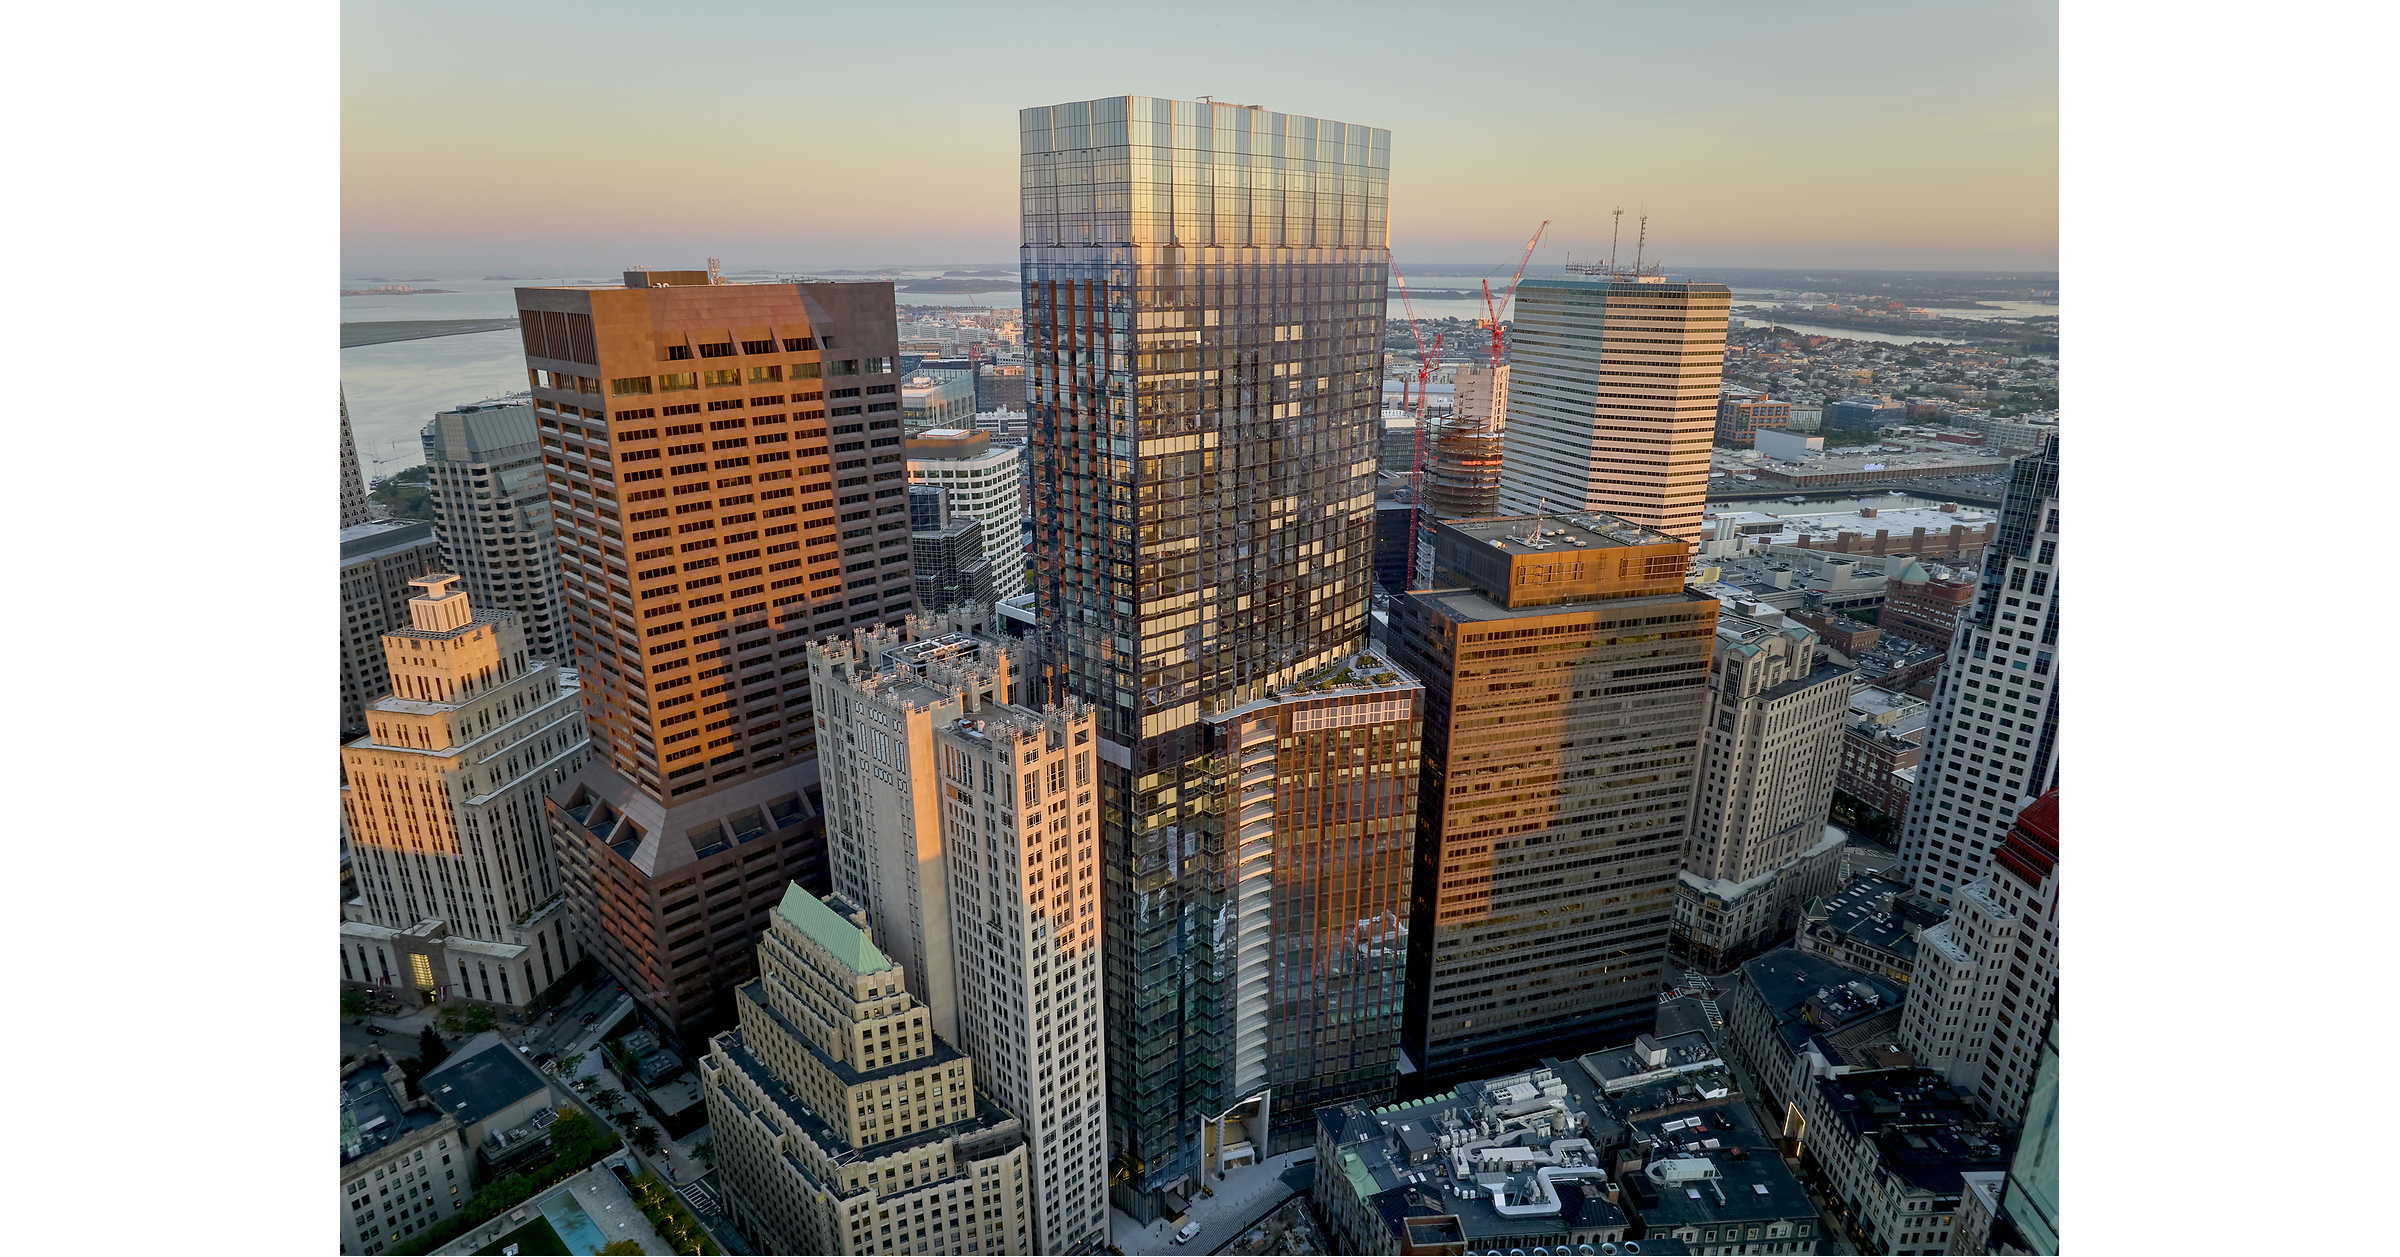
Nuveen Green Capital and co-lenders closed $281M of 20-year residential inventory C-PACE financing plus a $575M five-year securitized office loan for Boston’s Winthrop Center / Millennium Residences (total financing: $856M). The deal supports an 823,856 sq ft Class A Passive House office component and 317 luxury residential units, positioning it as New England’s largest C-PACE-financed transaction. The article frames the financing as strong institutional appetite for high-quality, sustainable “irreplaceable” assets, with proceeds intended to recapitalize the residences and fund the trophy office portion.
Analysis
This is more important as a signal for capital formation than for office fundamentals. JLL benefits from being a toll collector on rare, complex financings; the fee stream is high-margin and balance-sheet light, so even a handful of similar mandates can move sentiment faster than earnings. The second-order effect is a deeper bifurcation in CRE liquidity: the top tier of office/resi assets can still clear, while subscale or commodity office collateral remains effectively shut out, which should keep cap-rate dispersion wide and punish weaker landlords.
For MS and BCS, the direct P&L contribution is modest, but the transaction matters as a proof point that large banks can still syndicate prestige CRE risk without taking meaningful hold exposure. The bigger beneficiary may be private CRE credit and C-PACE providers, because these structures lower sponsor WACC and can crowd out plain-vanilla bank lending on sustainability-linked projects. If that template repeats over the next 1-3 months, it argues for a slower-than-expected recovery in traditional bank CRE balances.
Contrarian take: the market may misread this as a broad office thaw when it is really an underwriting exception for an irreplaceable asset with exceptional sponsorship. The falsifier is simple: if comparable downtown office refinancings do not follow within 1-2 quarters, this remains an isolated liquidity event rather than a regime change. A widening in office CMBS spreads or a renewed rate backup would quickly reverse any optimism spillover.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.45
Ticker Sentiment
Key Decisions for Investors
- Long JLL on any 2-3% post-news pullback; 1-3 month horizon. Thesis: capital-markets share gains and advisory pipeline expansion are the cleanest monetization of this theme. Risk/reward is favorable because the downside is limited if the event proves one-off, while a few more trophy financings can re-rate the stock.
- Relative-value pair: long BXP / short SLG for 1-3 months. The trade captures the bifurcation implied by trophy financing: best-in-class office should keep access to capital, while weaker office names remain funding-constrained. Falsify if office cap rates compress broadly or refinancing volume accelerates across lower-tier assets.
- No immediate standalone trade in MS or BCS; treat as a watch item. Only lean long if office CMBS issuance and CRE underwriting data confirm a sustained thaw over the next quarter, because one marquee deal is too small to justify a directional bank call.
- Set an alert on office CMBS spreads and trophy office refinancing volume over the next 30-60 days. If spreads fail to tighten, fade any broad-office optimism and use rallies in office REITs to reduce exposure.
More News
- French yields are near levels not seen since 2002. Why that could give U.S. Treasurys a boost
- Wall Street sees buying opportunity in banks as shares tank ahead of earnings
- Milos Maricic: listen for the AI number on next week’s bank calls
- DA Davidson cuts Amrize stock price target on guidance concerns
- Stocks making the biggest moves midday: T-Mobile, Verizon, AT&T, Crown Castle, Teva & more
- Inside Brooklyn’s WNBA Boom and Barclays Revamp