
Blackstone Sees India Nearing Tipping Point for Foreign Capital
Source: Bloomberg
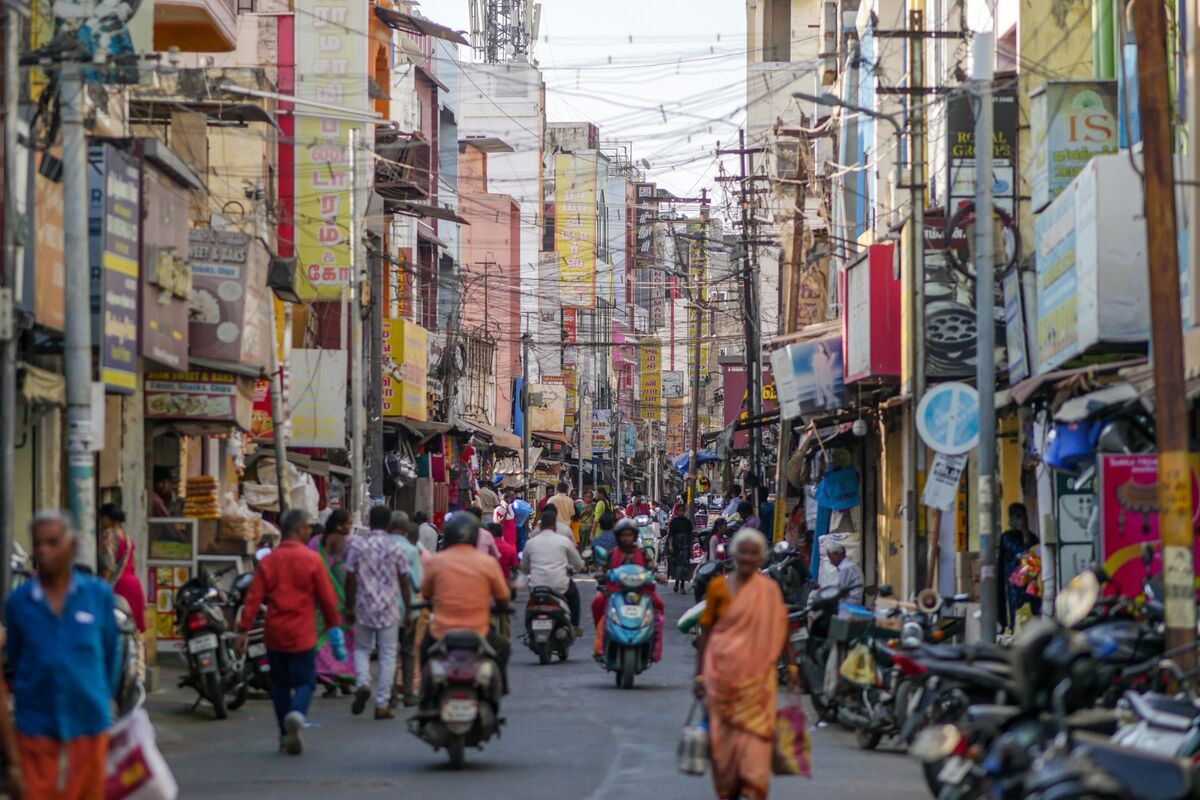
Blackstone President Jon Gray said India is nearing a tipping point for foreign capital, signaling a more favorable investment backdrop for global private-market investors. He contrasted this with Blackstone's early India efforts, when an undefined strategy and the global financial crisis prevented the firm from completing investments.
Analysis
The investable implication for BX is less near-term realization income than a potential extension of its fee-earning AUM runway. India offers a deeper pool of deployable real estate, infrastructure, credit, and growth-equity opportunities than many developed markets, but competition from KKR, Brookfield, Apollo, sovereign funds, and domestic managers will likely bid down gross returns before it materially changes BX's earnings power. The key differentiator is whether BX can recycle capital through listed vehicles and institutional partnerships, preserving management-fee growth without materially increasing balance-sheet exposure.
This is not yet a standalone trading catalyst: India deployment typically creates fee-bearing capital over quarters, while realized performance fees and valuation marks arrive on a multi-year lag. A 1-3 month positive rerating in BX would require disclosed fundraising, a large India transaction with attractive financing, or evidence that India commitments are incremental rather than diverted from other regional strategies. The contrarian risk is that foreign-capital enthusiasm compresses cap rates and private-market entry yields; in that outcome, headline deployment rises but future realizations and carried-interest conversion disappoint.
For 6-18 months, the second-order beneficiary could be listed Indian financial and infrastructure assets if private capital increases monetization, refinancing, and IPO pipelines. Conversely, rising local funding costs, rupee depreciation, capital-control changes, or weaker exit markets would make foreign managers reluctant to commit despite favorable long-duration growth narratives. The thesis is falsified if BX's net inflows and fee-related earnings fail to accelerate despite higher Asia-Pacific deployment, indicating that the opportunity is reallocative rather than additive.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Ticker Sentiment
Key Decisions for Investors
- Maintain BX as a watch-list long rather than initiate on this signal alone; reassess after the next two reporting periods for incremental Asia/India fundraising, deployment, and fee-related earnings growth. Upgrade only if management demonstrates that commitments are net new and not replacing slower fundraising elsewhere.
- For investors seeking India-capital-market exposure, monitor INDA or EPI versus BX: a sustained relative breakout in Indian equities alongside improving IPO and credit issuance would validate the exit-and-recycling mechanism more directly than BX's stock price.
- If BX rallies materially ahead of disclosed fundraising or earnings revisions, consider a tactical relative-value hedge of long INDA / short BX rather than chasing BX; this isolates India beta from the risk that private-market fee economics lag public-market enthusiasm.
- Set a thesis-risk alert around rupee stress, widening Indian corporate credit spreads, or a slowdown in Indian IPO volumes over the next 3-6 months; any of these would impair exit liquidity and reduce the value of additional private-capital deployment.
More News
- Wall Street Week | India’s Growth Test, Bangalore’s Infrastructure Problem, Cricket Attracts Capital
- Bolivia’s Congress approves $1.9bn IMF loan amid protest threats
- Flock Offers Employees Buyouts as Customers Flee
- Anthropic’s Claude Takes Bigger Role in Building AI
- Iranians rally in biggest show of defiance against US since war began
- Anthropic and OpenAI hunt for smaller data center deals, sources tell CNBC, in race to deploy AI capacity
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Tools for CFA Charterholders: An Evidence Standard
- Weekly Update: Unstructured Data Search, Ask AI, and Advanced Futures Data