
JLL arranges $463M bridge financing for 8-property multifamily portfolio
Source: PR Newswire
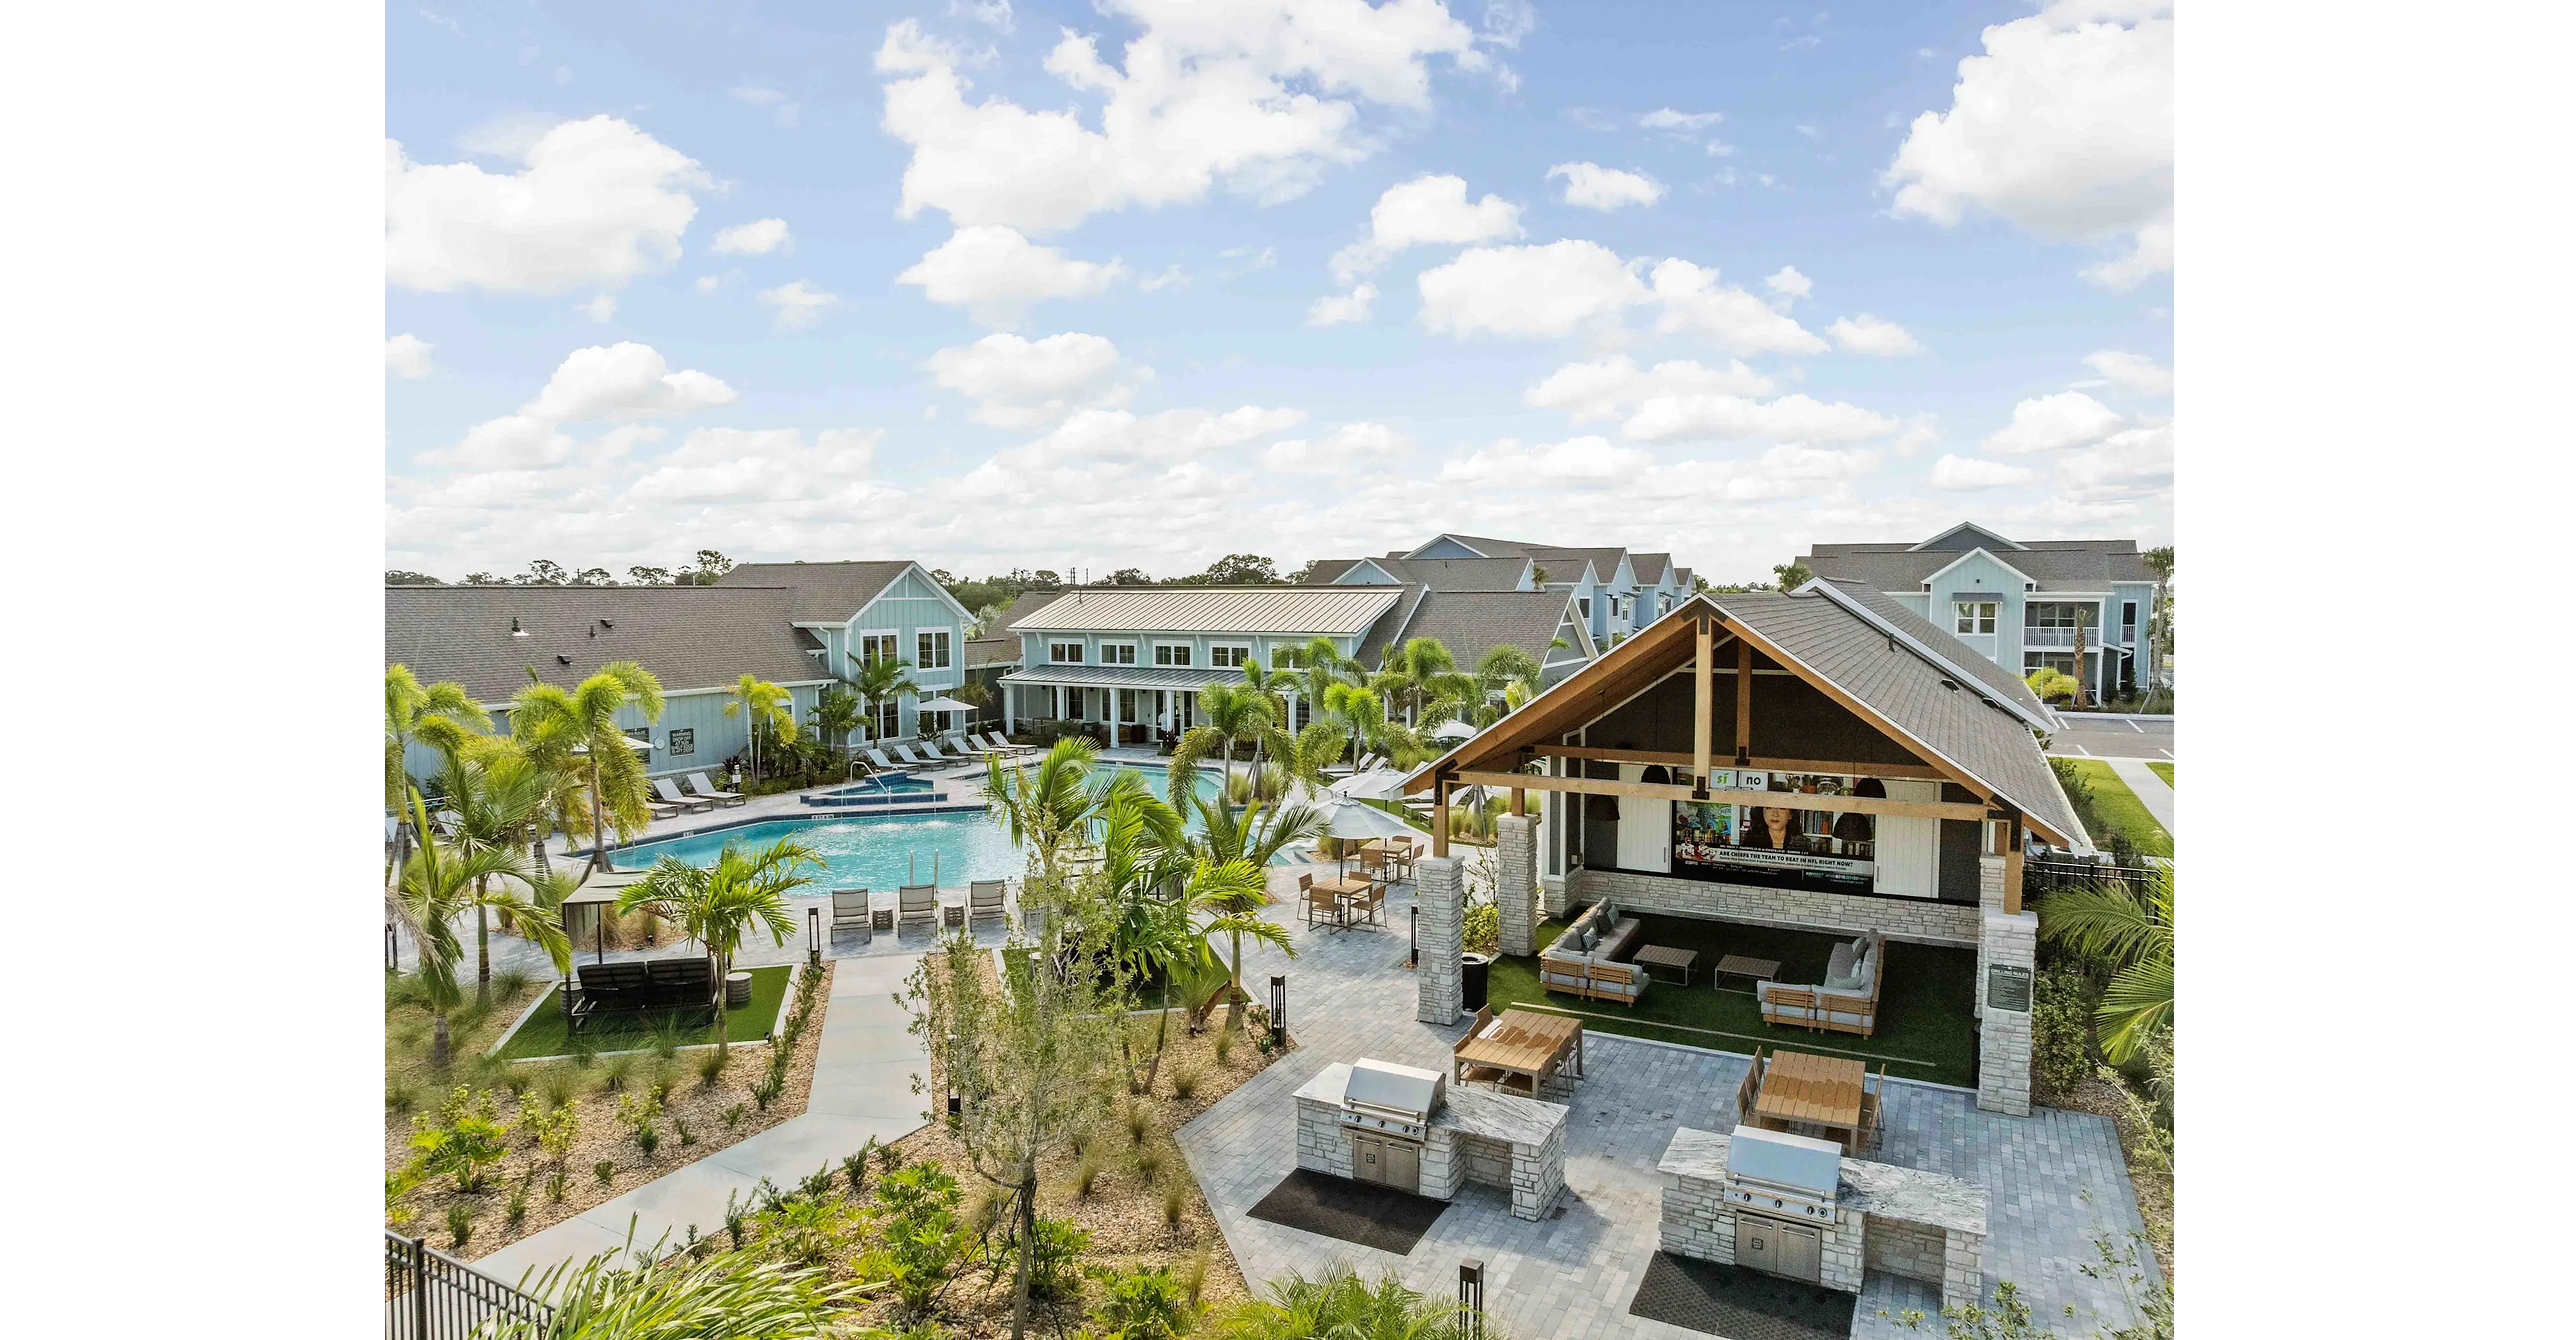
JLL arranged $463 million in floating-rate bridge financing from Barings for Thompson Thrift’s eight-property, 2,412-unit Class A multifamily portfolio across Florida, Georgia and Arizona. The loan proceeds retired construction debt on properties delivered in phases during 2025 and 2026; the portfolio spans seven MSAs. The transaction is a notable real-estate financing deal but does not report pricing or broader market effects.
Analysis
A useful signal for private real estate credit, but not a material standalone catalyst for JLL equity. The financing suggests a lender was willing to replace construction debt with floating-rate bridge capital on newly delivered assets; it does not prove the properties have completed lease-up or secured durable, lower-cost financing. The key underwriting question is whether rent collections can cover debt service as floating rates reset, especially if concessions or insurance costs pressure net operating income.
Second-order risk is market-level rather than portfolio-wide: several Florida markets face exposure to insurance costs and new apartment supply, while Phoenix and Atlanta also warrant monitoring for rent competition. Geographic spread reduces single-market concentration but does not remove correlated Sun Belt supply and financing risks. For JLL, the transaction may support confidence in debt-advisory activity, but one arranged loan is too small a signal to infer a meaningful change in consolidated earnings.
Over the next 1–3 months, watch regional rent concessions, occupancy/lease-up disclosures, floating-rate benchmarks and multifamily lending terms. Over 6–18 months, the test is whether bridge borrowers can refinance into permanent debt without relying on aggressive rent growth or cap-rate compression. Contrarian read: financing availability is not the same as recovery in property values; a floating-rate take-out can defer, rather than resolve, refinancing risk.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.10
Ticker Sentiment
Key Decisions for Investors
- No trade in JLL on this announcement alone; treat it as a small positive read-through for transaction activity, not an earnings revision catalyst.
- For multifamily credit exposure, favor lenders and borrowers with demonstrated lease-up and debt-service coverage over assets whose refinancing case depends on rent growth; this deal alone does not establish those metrics.
- Set a watch alert for concessions, occupancy and insurance-cost trends in the named Florida markets, plus floating-rate debt costs. Deterioration in these measures would weaken the bridge-loan thesis.
- Falsification: the constructive financing signal fades if comparable Sun Belt properties report rising concessions or weaker collections, or if tighter lending terms and higher refinancing costs prevent bridge borrowers from moving to permanent financing.
More News
- South Korean carmaker Hyundai plans 'strategic' investment of $15.5 billion in India by 2032
- Applied Materials’ $5 billion AI lab aims to cut chip development time in half—and restore Silicon Valley’s edge
- Wells Fargo CFO on Earnings, Deals, Consumer Strength
- Bank of America hit with more than $1.2 billion in penalties over money-laundering violations
- Meta’s Muse models reach the AI frontier—and kill any hopes to ‘pace’ it
- In charts: How one of the world's biggest economies got trapped by debt