
Dahua Technology prezentuje na targach IFA Berlin 2026 zintegrowane rozwiązania dla inteligentnego domu oraz nowe technologie
Source: PR Newswire
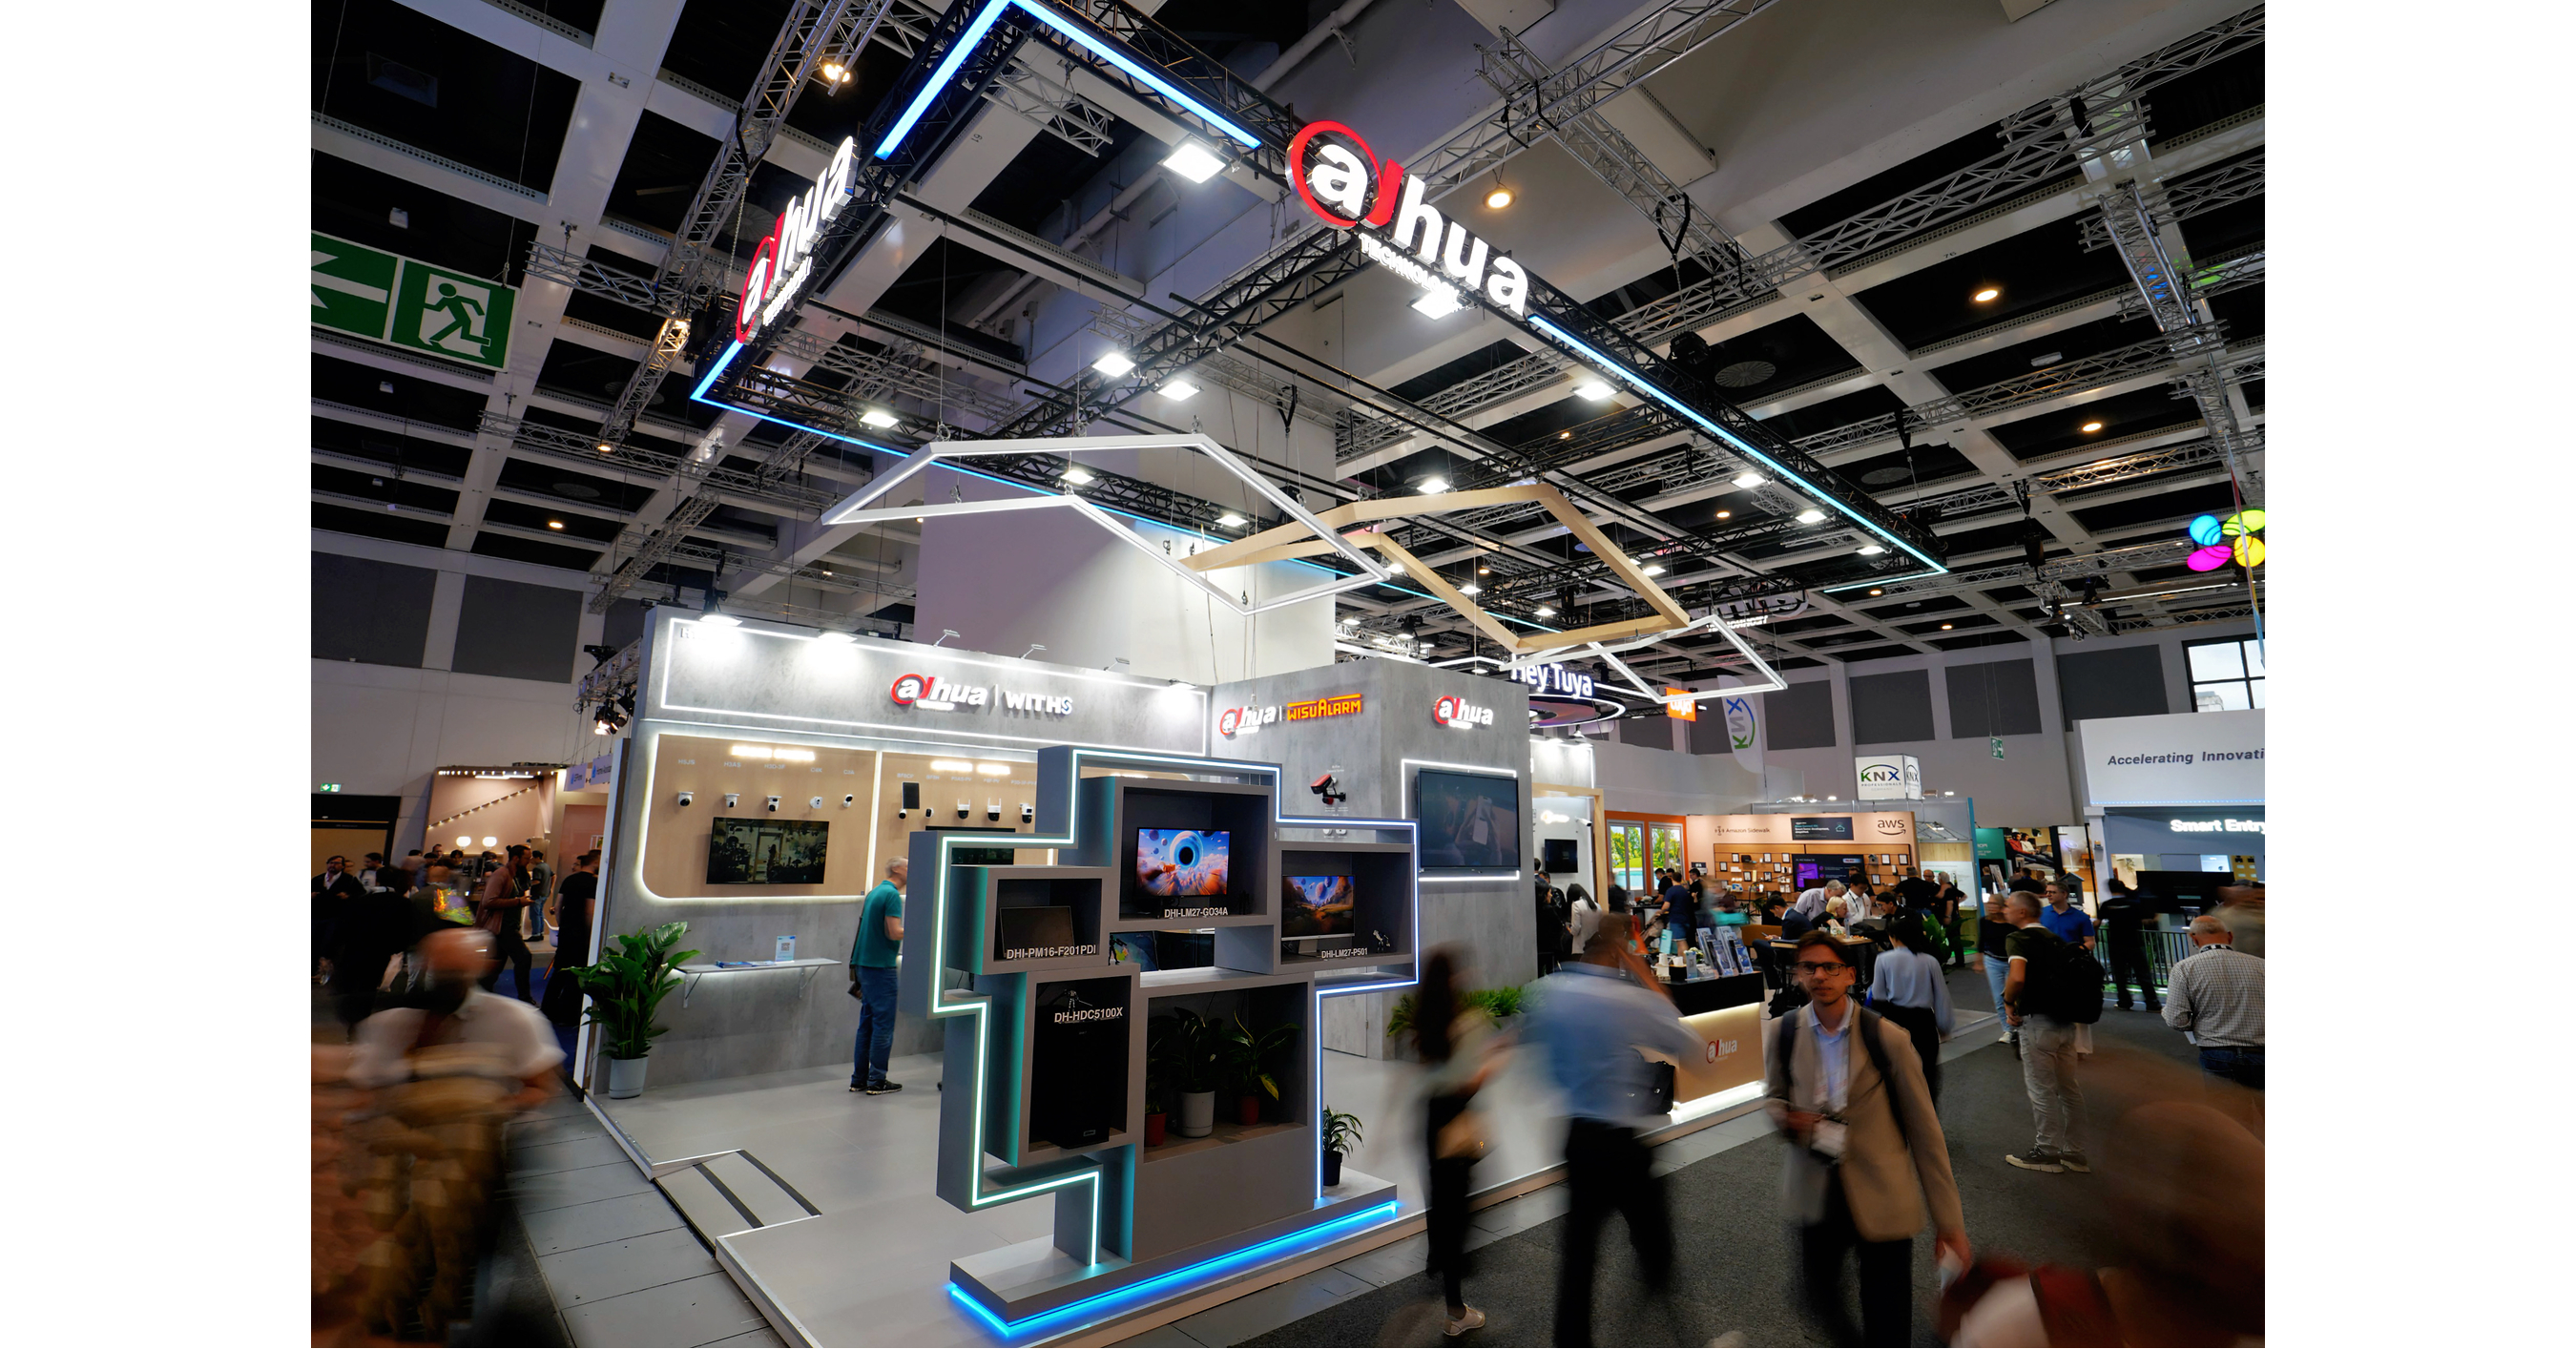
Dahua Technology showcased an expanded AIoT smart-home and security portfolio at IFA Berlin 2026, including WITHS wireless surveillance, AirShield intrusion protection, WizTalk IP video intercoms, AI-assisted fire detection and gaming monitors. New products feature Wi-Fi/4G connectivity, solar and battery-powered options, cloud management, and AI functions such as person, vehicle, pet, gesture and face detection. The announcement signals broader product expansion beyond Dahua's core video-security business but provides no financial guidance, sales figures or material commercial commitments.
Analysis
This is strategically more relevant to channel economics than to near-term earnings. A unified installer/cloud workflow can increase attachment rates for cameras, alarms and access control, but it also shifts value from hardware ASPs toward recurring software, monitoring and support revenue. The key diligence item is whether European distributors report incremental orders, active cloud endpoints and installer adoption; exhibition announcements alone provide no evidence of any of these.
Competitive pressure is most acute in the value-oriented SMB security segment, where Hikvision (002415.SZ) and Dahua's local channel partners compete on bundled functionality rather than premium pricing. That can constrain gross margins for standalone consumer-security vendors such as Arlo (ARLO), while potentially raising the cost of customer acquisition for Alarm.com (ALRM) and Resideo (REZI) if installers can offer a lower-cost integrated alternative. Conversely, premium European enterprise vendors such as Axis Communications/Canon (7751.JP) retain an advantage where cybersecurity certification, data sovereignty and government-procurement eligibility matter more than upfront equipment cost.
The contrarian point is that product breadth may increase, rather than reduce, execution risk. Combining security, fire, displays and smart-home control requires separate distribution, certification and service capabilities; absent a visible recurring-revenue model, breadth can dilute working capital turns and trigger channel inventory discounts. Over the next 1-3 months, watch EU regulatory or public-sector restrictions on Chinese surveillance equipment and reseller commentary on compliance; these would matter far more to valuation than product specifications. Over 6-18 months, verified cloud adoption could support a multiple re-rating, while privacy/security incidents or sanctions expansion would impair international addressable market and channel access.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.28
Key Decisions for Investors
- No immediate directional trade: treat this as a channel-data watch item, not an earnings catalyst. Require evidence of European sell-through, cloud subscriptions or distributor backlog before underwriting revenue impact.
- Monitor ALRM and REZI for 1-3 months for installer churn, reduced hardware attachment or weaker international guidance; consider a tactical short only if management identifies pricing pressure or elevated customer-acquisition costs. Falsifier: stable/improving recurring-revenue growth and gross margin despite competitive bundling.
- Prefer long Canon (7751.JP) versus a China-video-surveillance proxy only if EU procurement restrictions or cybersecurity-certification requirements broaden; the pair expresses a shift toward trusted premium infrastructure. Falsifier: no regulatory escalation and evidence that low-cost vendors sustain enterprise wins without margin concessions.
- Set alerts for EU data-sovereignty enforcement, sanctions/entity-list changes, or a reported cyber incident involving Chinese surveillance supply chains. These are asymmetric downside catalysts for international channel expansion and could emerge faster than any product-led revenue benefit.
More News
- OpenAI Trims Target Value & Volvo Cars Cuts 2,500 Jobs
- PG&E’s CEO says AI is ‘the best thing that could’ve ever happened to the grid’
- The mobile ambitions of SpaceX see telecom stocks get hit again. What the latest developments mean.
- Wake up! The long bond’s up two points!
- US tech stocks tumble as investors fret over AI spending
- Mark Zuckerberg owns 13% of Meta but controls 61% of its votes. California’s wealth tax would bill him on the 13%