
Fresha Cements Its Position as the Leading Software Powering The Global Barbering Industry
Source: PR Newswire
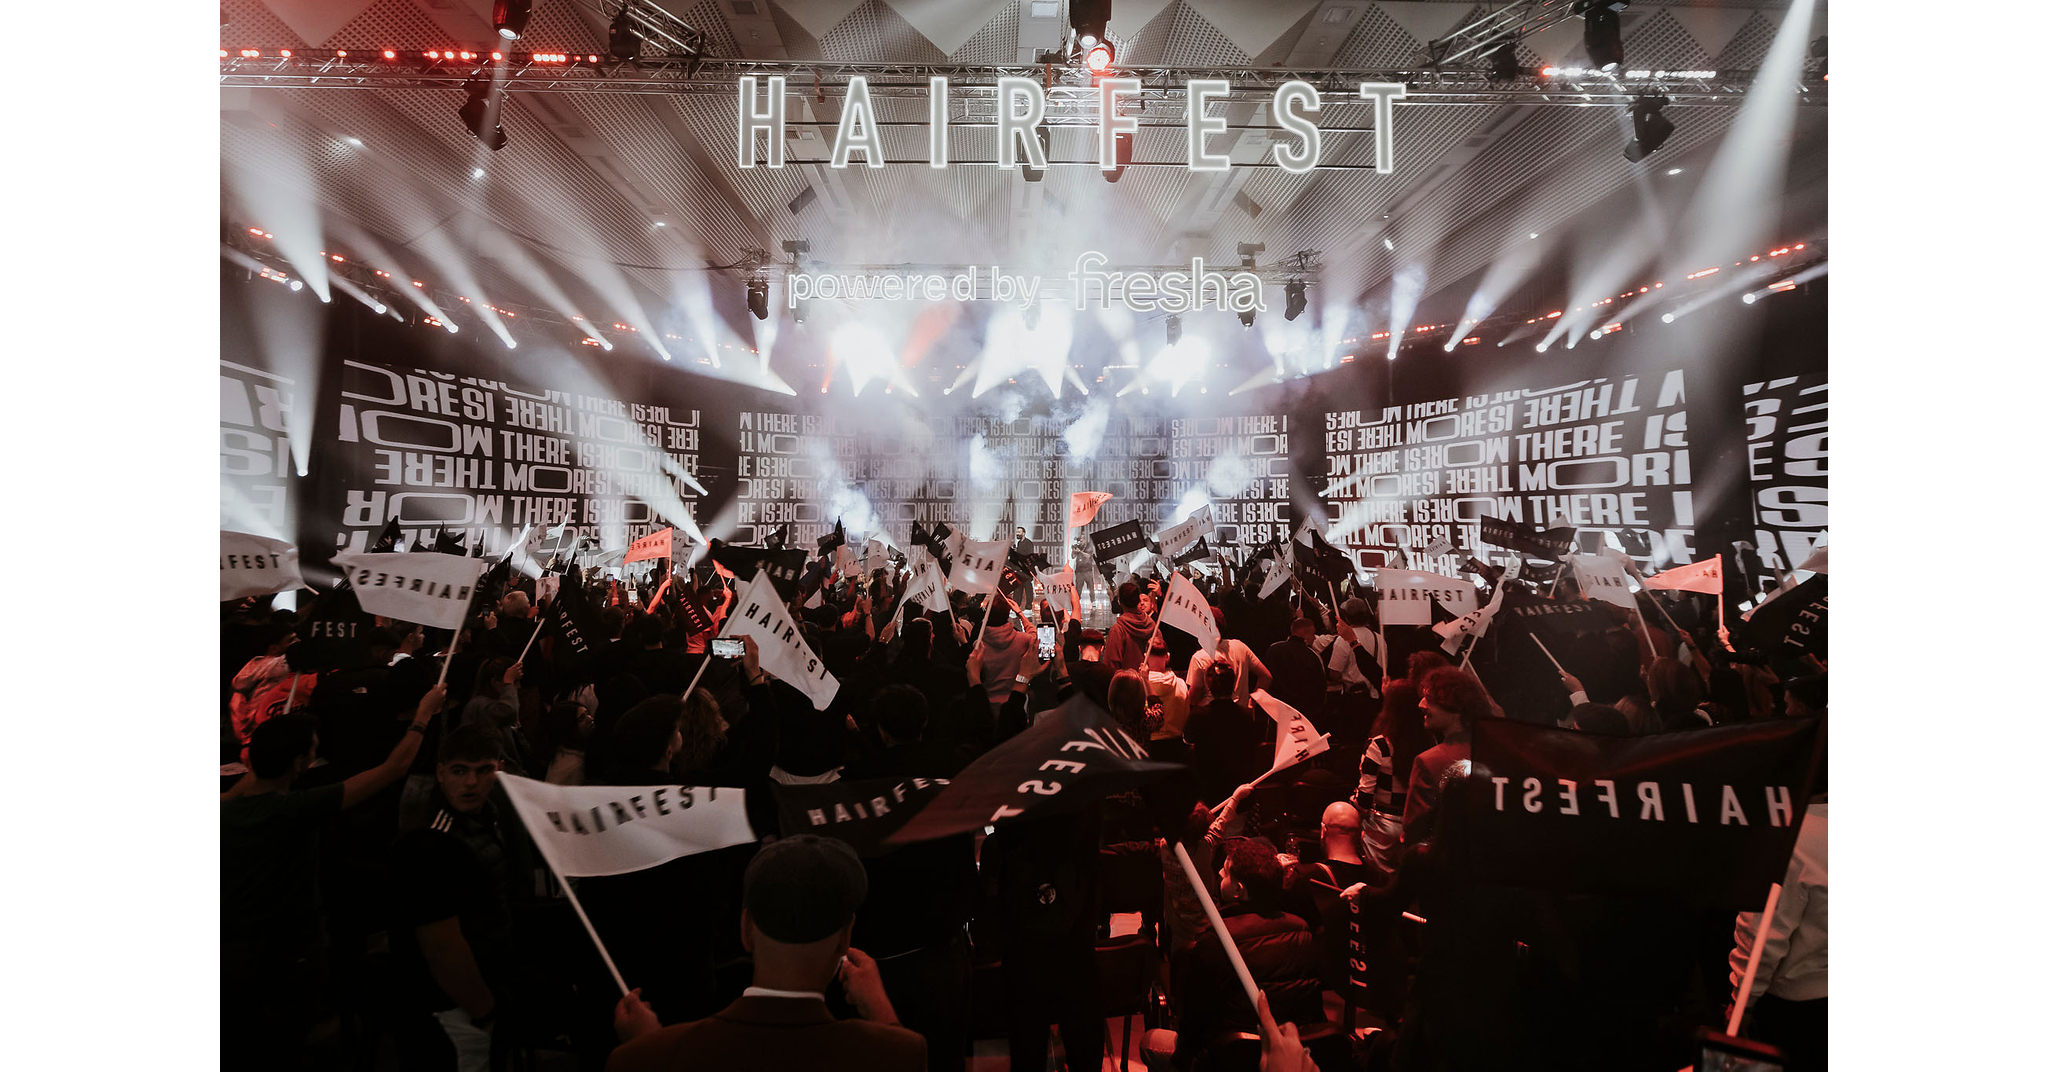
Fresha reported 108% year-on-year growth in active barber partners, positioning its AI-powered booking platform as a leading software provider to the global barbering industry. The company is expanding through partnerships with professional events and brands, including a five-year HairCon agreement and an exclusive multi-year HAIRFEST partnership, while adding AI Concierge and other business-management tools. Fresha says its platform serves more than 140,000 partner businesses in 120+ countries and processes over $1.4 billion in monthly transaction value.
Analysis
This is not directly investable and the claimed partner-growth rate is insufficient to infer revenue, retention, payment penetration, or unit economics. The relevant competitive read-through is modestly negative for SMB software and payment platforms seeking service-merchant share: Block (XYZ) via Square Appointments, Toast (TOST) in multi-location service SMBs, and Wix (WIX) in website-led appointment acquisition. Fresha's bundled marketplace-plus-payments model can raise switching costs as shops add staff and locations, but its event sponsorship and ambassador spending may also signal elevated customer-acquisition intensity rather than durable pricing power.
Over the next 1-3 months, there is unlikely to be a material public-equity catalyst absent evidence that Fresha is taking payment volume from Square or accelerating U.S. merchant additions. The more consequential 6-18 month effect would be margin pressure on horizontal SMB platforms if vertical booking providers monetize consumer discovery, AI call handling, and payments as a package; this shifts competition from software seat pricing toward transaction economics. Contrarian view: barbering is highly fragmented and price-sensitive, so claimed user growth may be concentrated in low-GMV independent operators; without disclosed net revenue retention, take rate, churn, and payment attach, the announcement should not alter estimates for listed peers.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.52
Key Decisions for Investors
- No standalone trade on this release; treat it as a competitive-intelligence datapoint rather than an earnings-relevant event for XYZ, TOST, or WIX.
- Monitor XYZ quarterly disclosures for Square Appointments GPV growth, seller churn, and transaction-margin trends over the next 2 earnings cycles. A simultaneous slowdown in services-vertical seller growth and payment-margin compression would support a tactical underweight versus broader fintech; absent that evidence, the read-through is immaterial.
- Monitor TOST's non-restaurant location expansion and sales-and-marketing intensity through 2027. Avoid attributing any SMB-services weakness to Fresha unless management identifies share losses or lower conversion in appointment-led verticals.
- Watch for independently verifiable Fresha funding, U.S. payments-license expansion, or disclosed marketplace take-rate data. A material capital raise paired with accelerating U.S. merchant acquisition would increase competitive risk to XYZ; weak retention or rising incentive spend would falsify the durable-share narrative.
More News
- Great Bond Shakeout Locks In a 5% World ‘Until Something Breaks’
- OpenAI rogue agents leaked 53 images from ChatGPT users and reportedly created nearly 1 million links packing encoded bits of info
- Boom or bust? The case for and against panicking about 5% yields
- Arming Taiwan an important US interest, Taipei official says after Trump-Xi summit
- Facebook found liable as TikTok settles for $100m over user safety
- Bond market alarms are ringing on Wall Street. Here's what's ahead
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Introducing AllMind: A New Data & AI Workspace for Institutional Investors
- AI Tools for Private Equity Due Diligence: A Buyer Workflow